Medicare coverage for dermatology can be quite limited. If you or your loved one needs treatment NOW, take a look at your coverage before it’s too late and you’re stuck with a big bill!
Medicare Part B can cover some dermatology services. If your condition is medically necessary, Part B will cover doctor services relating to evaluating, diagnosing, or treating skin conditions. Medicare will not cover cosmetic treatments, and it will only cover skin cancer screenings if you are showing symptoms.
How Does Medicare Cover Dermatologist Visits?
Dermatologist and Patient | Medicare Plan Finder
For dermatology-related services, you will have to meet your Part B deductible first. For most people in 2019, the deductible will be $185.
Then, Medicare will usually pay 80% of the service cost. You will be responsible for the remaining 20%. For Medicare to cover that 80%, your dermatologist or physician must accept Medicare assignment. Your doctor should be able to tell you whether or not they accept assignment, but if you’re not sure, your insurance carrier or insurance agent can help you.
Some Medicare Supplement (otherwise known as Medigap) plans can cover the rest of your costs, like your deductible and the remaining 20%. If you’re interested in investing in a Medigap policy, one of our agents can help. Click here to get started on setting up your free Medicare Plan Finder appointment.
Uniquely, Medicare plans are now able to cover MyPath, a genetic test for malignant melanoma.
How Much Does It Cost to Go to a Dermatologist With Medicare?
Dermatology costs vary based on what insurance you have, where you live, and what services you need. If you have Medicare (demonstrated above), you will likely be responsible for 20% of services. Some dermatologists accept Medicaid as well.
Keep in mind that in the cases of Medicare and Medicaid, your care will most likely not be covered unless it is determined to be medically necessary. For example, acne care is not generally considered a medically necessary treatment plan, but skin cancer removal is.
Thankfully, dermatology visits are not typically wallet-breaking. Depending on what doctor you see, where you live, and what services you require, The Law Dictionary says you may only need to pay between $100 and $200, which is a low cost compared to other health services, like hospital stays.
Do You Need a Dermatologist?
We’re not doctors, but chances are that if you’re asking this question, you should go and see a dermatologist.
Some skin conditions that you may start to notice as you age are dry and itchy skin, benign growths, loose skin (especially around the eyes, cheeks, and jawline), transparent or thin skin, spotting, wrinkles, and easy bruising.
While those are all certainly typical signs of aging, there are steps you can take to keep your skin healthy and prevent further damage, like:
Don’t stay in direct sunlight for long periods of time.
Always use a sunscreen with SPF 30 or higher when spending time outdoors.
Stay away from tanning beds.
Check your skin or have a loved one check your skin for new growths or moles that appear to be changing in color or size.
See a dermatologist whenever you face a new concern!
Questions to Ask Your Dermatologist
Patient Asking Dermatologist Questions | Medicare Plan Finder
Knowing what questions to ask your doctor can be a challenge, especially if you are really unsure of what’s wrong. We searched the internet and compiled this list of questions you may want to ask your dermatologist:
What foods should I avoid for my skin health? What should I be eating more of?
How can I slow down signs of aging, like wrinkles and dark spots?
How can I check my own moles and how do I know when to call you?
What lotions and sunscreens do you recommend?
These are the skin products I use now (list sunscreens, lotions, exfoliators, makeup, etc.). Are they damaging?
How to Find a Dermatologist
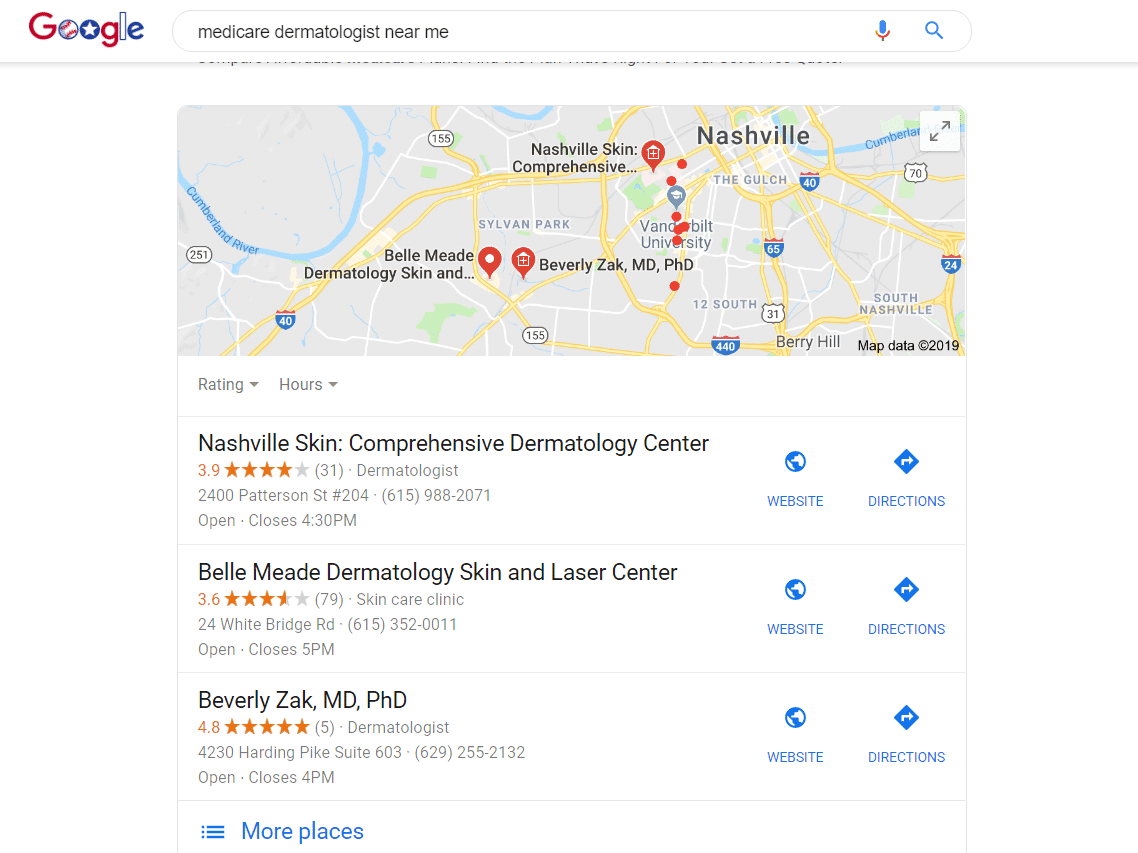
To find a dermatologist near you, you can visit a site like “doctor.com” or perform a Google search. Usually, searching for “dermatologist near me” pulls up reasonable results. For example, these are the results when we searched from our office in Nashville.
Once you’ve looked at reviews and found some good dermatologists in your area, make sure they accept Medicare. If you have another plan that you’re using, like Medicare Advantage, make sure the dermatologist is in your plan network.
Dermatologists are specialists. If you have an HMO (Health Maintenance Organization) plan, you may need a referral from your primary physician before you can see a dermatologist. If you aren’t sure whether or not you need a referral or if you need help finding a dermatologist that is in your network, call your insurance agent!
A highly trained, licensed insurance agent can help you walk through the process of finding providers in your network and can help you make sure you have all the coverage you need. Don’t have an insurance agent? To set up an appointment with your new agent, give us a call at 844-431-1832.
Contact Us | Medicare Plan Finder
*This post was originally published on June 28, 2018, and updated on July 3, 2019.
Get Middle Tennessee Dental Care with Medicare and Interfaith Dental
Nashville and Middle Tennessee residents don’t have to suffer from a lack of affordable dental coverage. In 1994, Dr. Tom Underwood founded Interfaith Dental with the help of the Nashville Dental Society and the Outreach Commission of West End United Methodist Church.
Interfaith Dental makes it possible for low-income families to access the dental care they need without having to pay full price.
Low Income Dental Clinics in Middle Tennessee
Middle Tennessee has quite a few public health clinics, and many specialize in dental care for low-income families and individuals. We work closely with Interfaith Dental, located both in the Fesslers Lane/Elm Hill Pike area of Nashville and near the St. Thomas Rutherford Hospital campus in Murfreesboro. Below are some of the low-income dental clinic options you have in Middle Tennessee.
Not located in Middle TN? That’s ok – there are plenty of low income dentists throughout the country. This government website is operated by the Bureau of Primary Health Care, a part of the Health Resources and Services Administration. You can use their tool to find a federally-funded community health center that offers dental services.
Additionally, you can search through the American Dental Association or the American Dental Hygienists’ Association to find supervised, low-cost care that is part of the training program for dental students. Your care will be supervised by licensed and experienced dentists. If you have Medicare, we can help you make sure you have the best Medicare plan to get you the dental services you need and help you find the best dentist that accepts Medicare.
Who is Interfaith Dental (IFD)?
Interfaith Dental is a low income dental clinic with a mission to “create a healthier community by providing transformational oral health care for those experiencing poverty.” They envision a Middle Tennessee community where every resident “has the opportunity to achieve and sustain a healthy smile,” regardless of income status.
When it began in 1994, IFD only had two chairs and one employee, operating out of the West End United Methodist Church basement. By 1998, they were able to move their operation to 1721 Patterson Street (just off West End, near the St. Thomas Midtown campus).
In 2012, they opened another clinic in Murfreesboro, expanding their reach into Rutherford County. In even bigger news, this past year (2019), the clinic was able to expand into a new office at 600 Hill Avenue (near the Fesslers Lane/Elm Hill Pike intersection).
They’ve come along way from their two-chair operation, now owning 26 state-of-the-art dental operatories.
How to Become an Interfaith Dental Patient
Since the Interfaith Dental Clinic offers such low-cost dental care, there is an application process before you become eligible for services. To be eligible, you must be legally considered low-income (living below the poverty line), uninsured, and suffering from a devastating dental disease.
To get more information or to schedule your first appointment, call 615-329-4790 for the Nashville office, or 615-225-4141 for the Murfreesboro office.
Your Interfaith Dental journey will begin with a phone questionnaire. You’ll be asked for some basic information which will determine if you are eligible for Interfaith Dental Clinic services and what services you need.
Next, the Patient Care Coordinator that you speak with will tell you when the next “Application Day” is. On that day, you’ll come into the office to complete your application. Both the Nashville and Murfreesboro locations have the same office hours in 2019, which are:
Monday through Wednesday, 8 AM to 4 PM
Thursdays, 1 PM to 7:30 PM
Fridays, 8 AM to 12 PM
Be sure to bring the following items with you on “Application Day”:
Current Year Tax Return
Two current pay stubs for anyone working in your household.
If you are paid in cash, provide written documentation from your employer on a business letterhead that contains the business name, address, phone number, and owner information as well as your hire date, hours worked per week, pay rate, and hourly income.
College students, bring your class schedule
Work training program participants, bring proof of enrollment.
65+, provide social security/pension/retirement proof of income.
Proof of address (utility bill, bank statement, etc.)
TN driver license
Referral from medical professional, social worker, or employer (if you have one)
Due to high demand, there may be a waiting period for your services. There are a limited amount of applications that are handed out on a first-come, first-serve basis every month.
While walk-ins are generally not accepted, please call Interfaith Dental if you have a dental emergency. Some emergency services are offered on a first-come, first-serve basis.
What to Expect from Your First Interfaith Dental Appointment
At your first Interfaith Dental Clinic appointment, you’ll begin by meeting the team members. Then, someone will sit with you to review your medical and dental history and discuss all of your dental concerns.
Interfaith Dental care is comprehensive – they want to know how your dental health has affected your career, your family, and even your self-confidence. Is your goal to have a beautiful smile again, or to eliminate pain? Your care providers will hear all of your concerns and follow up with the best possible care.
The next step of your first appointment is a series of full diagnostic X-rays and oral exams that will help the doctors determine a treatment plan. Phase one will usually include fillings, cleanings, and extractions, and phase two will include crowns, root canals, and even partial dentures, if necessary.
If that sounds like a lot, it’s because it is. Your first appointment with Interfaith Dental can take up to two hours, in some cases – so be sure to allow that much time out of your day.
Original Medicare only covers dental services when they are part of a hospital stay.
For example, if you go to the St. Thomas emergency room with a fractured jaw and need emergency dental care in the hospital, those services may be covered by Medicare Part A. However, common dental services and treatments such as annual exams, cleanings, root canals, dentures, implants, etc. are not covered by Original Medicare.
To get Medicare dental coverage, you’ll need to either enroll in a private, individual dental plan or a Medicare Advantage (Part C) plan. Medicare Advantage plans, even though they are Medicare health plans, are operated by private insurance companies, which allow them to add benefits that the Original Medicare program does not cover. This can include not only dental benefits but also benefits like fitness programs, vision, meal delivery, etc.
Medicare Plan Finder and Interfaith Dental, Bringing Change Together
Medicare Plan Finder works with Interfaith Dental by helping their patients fill the gaps in their dental coverage. Interfaith Dental is not always able to provide free or very low-cost care. For example, there may be times where a $10,000 dental procedure costs $5,000 at Interfaith Dental. You’d still be paying $5,000 less than if you went to a regular dentist, but that $5,000 may be more than you can handle. At Medicare Plan Finder, we try to match you up with a low-cost insurance plan that can cover those extra out-of-pocket costs.
Start by scheduling your appointment at the Interfaith Dental Clinic located nearest to you. Call 615-329-4790 for the Nashville office, or 615-225-4141 for the Murfreesboro office.
Then, if your doctor determines that you need a series of procedures that you can’t afford (even with Interfaith Dental’s help), give us a call at 844-431-1832. We can help you determine whether or not you are eligible for Medicare (did you know you don’t have to be 65?). If you’re eligible, we’ll help you find low-cost coverage so that you can go back to Interfaith Dental to get the services you need.
Father’s Day 2019: Healthy Gifts for the dad who Wants Nothing
Are you one of the millions of people looking for gifts for the dad who wants “nothing?” Maybe this is the year that you can finally give him something other than a new tie. As dad ages, consider gifting him the education, care, and technology he needs to stay healthy.
Sometimes the best gift is not a physical object. Consider gifting your dad with:
Bringing him healthy meals or taking him out to healthy lunches
Fitness Gifts for Dad
One of the easiest ways to get dad a gift that encourages him to practice healthy habits is by looking at the fitness industry. These gifts not only say, “I love you,” but also allow you to be proactive for his health:
A gym membership (if he qualifies for Medicare, you can get him a gym membership by helping him sign up for certain Medicare Advantage plans).
List of Male-Specific Diseases
The best gift you can give your aging father is education and readiness for what life may throw at him next. Even if dad is healthy now, help him learn about diseases that he may be susceptible to. Is he nearing or over age 65? Help him also learn about different insurance options that he may not have heard about yet!
These are some male-specific diseases and diseases that are more likely to affect aging men than women. Remind your dad to look for the signs.
According to the Centers of Disease Control and Prevention (CDC), cancer is the 2nd leading cause of death for people over the age of 65. It’s extremely important for seniors and Medicare eligibles to remain proactive when it comes to their health. If cancer is caught early enough through screenings, it may be treatable. The most common cancers found in men are:
Prostate cancer
This type of cancer generally grows slowly and is initially found in the prostate gland where it may not cause extreme harm. However, prostate cancer can grow quickly and create bigger issues. If your dad is over 50 years old, African American, or if prostate cancer runs in your family, he has a higher risk of developing prostate cancer.
Colorectal cancer
Did you know colorectal cancer is the second leading cause of cancer-related deaths in the US? Colorectal cancer develops from abnormal growths called precancerous polyps. These growths can be removed before they turn cancerous, so it is vital to stay alert and proactive.
Medicare Coverage for Men
If your dad is eligible for Medicare, Medicare covers a digital rectal exam and a prostate-specific antigen (PSA) test once a year. In addition to these tests, Medicare covers numerous colorectal screenings like the fecal occult blood test, flexible sigmoidoscopy, and colonoscopies. Screenings are extremely important. The CDC says that close to 1,000 colorectal cancer deaths could be prevented each year if even 70.5% of people attended regular screenings.
Are you interested in exploring Medicare insurance available for you? Our agents can explain your coverage options and help you find a plan that best fits your needs and budget. If you are interested in arranging a no-cost, no-obligation appointment with an agent, complete this form or give us a call today at 844-431-1832.
*Originally published on August 16, 2018, and updated on June 13, 2019.
3 Heart Health Resources you Should use
It’s never too late to start making good decisions regarding your heart health. As you age, your risk of developing heart disease dramatically increases.
You can help manage the risk by taking an active role in maintaining your heart health, and using the free resources you have at your disposal, including:
1. Medicare Preventive Services for a Healthy Heart
Man at Medicare Wellness Visit | Medicare Plan Finder
Your doctor may be your best resource for keeping your heart healthy. Did you know you can get a free wellness exam every year if you have Medicare insurance?
The Medicare Annual Wellness Visit (AWV) may include measurements of your height, weight, BMI and blood pressure, which can help identify your risk of developing heart disease. During your AWV, your doctor can discuss action plans for your diet and exercise in order to help minimize your risk of developing a heart condition.
Medicare will also cover blood tests for cholesterol once every five years. The heart screening will measure your cholesterol, triglyceride and lipid levels. An electrocardiogram (EKG or ECG) will give your doctor a picture of your heartbeat. EKGs fall under medically necessary diagnostic testing. Medicare will pay for an EKG if your doctor orders one.
Work with your doctor to develop a diet and exercise plan. Medicare will cover medically necessary obesity screenings and nutrition counseling.
Some private health insurance policies called Medicare Advantage plans will cover fitness classes along with all of the wellness services Original Medicare covers. Talk to an agent about finding a Medicare Advantage plan that will allow you to keep your doctor and access every service you need.
2. Risk Tracking for an Accurate Picture of Heart Health
The American College of Cardiology offers CardioSmart for free. The website features a BMI calculator, a Heart Disease Risk Assesment, and a Cholesterol Calculator online (as well as a “Med Reminder” app to remind you to take your medication).
As you age, it becomes more important to track your weight, your cholesterol levels, and your overall diet. Additionally, you should look at your family medical history. Find out what kind of genetic risk you have for developing heart disease. If you have immediate family members with a history of heart conditions, that may indicate that you have a greater risk of developing cardiovascular disease.
3. Take Control of Your Diet and Exercise
Heart-Healthy Foods and Exercise Equipment | Medicare Plan Finder
Your risk for heart disease is closely linked to your weight. If you’re overweight or obese, you have a much greater chance of developing heart disease, and losing weight is one of the most effective ways to help prevent heart disease.
A 10 percent weight loss significantly reduces your heart disease risk. Consistent calorie tracking is one of the most important steps in losing weight successfully. It may seem difficult to track what you eat, but there are hundreds of tools out there that can help you. If you are at risk for heart disease, you’ll want to focus on eating lean proteins while cutting down on fats and sodium and increasing your fiber intake (whole grains, fruits and vegetables).
You can create your own tracking system by writing down what you eat every day, or you can try using an app that will store your information and help you figure out your caloric intake. MyFitnessPal is one example of a free app that is easy to use.
All you have to do is enter the foods you eat and any exercise you complete throughout the day. It’ll track your nutrition and your calories and tell you if you’re eating too much or not eating enough of any specific food group. The MyFitnessPal mobile app even has a feature that allows you to scan a package’s barcode and upload the food’s nutritional information.
Let us Help
A comprehensive health insurance plan is a great resource to help you stay healthy. Medicare Plan Finder agents can help you find a plan that covers the services you need while fitting your budget and lifestyle. Call us at 844-431-1832or contact us here to learn more.
Contact Us | Medicare Plan Finder
This post was originally published on October 12, 2017, by Anastasia Iliou and was updated on June 13, 2019, by Troy Frink.
A Guide to Hospital Indemnity Insurance
Medicare is a great resource for covering your healthcare costs, but it doesn’t cover everything. Are you spending more on hospital visits than you can afford? Are you or a loved one going to need assisted living or nursing home care soon?
Those services can be extremely expensive, and additional insurance coverage can provide the safeguard you need. Consider discussing ancillary products for short-term care and hospital indemnity insurance with your licensed agents
What Is Short-term Care Coverage?
Short-Term Care in Hospital | Medicare Plan Finder
Short-term care insurance is designed to provide hospital coverage for one year or less. Short-term plans are recommended for people who may become severely ill or injured or for anyone over 80.
These policies are especially beneficial for anyone staying in a nursing home or using an assisted living program. It can also help if you missed open enrollment and have to wait another year to apply for Medicare.
Pre-existing conditions will usually not affect your short-term care insurance. Premiums will rise with your age, so it’s important to get coverage early. Short-term coverage works fast; you can start receiving benefits as soon as the day after purchase.
Make sure to speak with an agent about your health conditions and your current coverage to determine if you need the extra coverage that short-term care insurance provides.
What Is Hospital Indemnity Coverage?
The word indemnity means protection from financial liability such as hospital expenses. Ancillary hospital indemnity policies are the best, cheapest way to save your piggy bank in the event of a hospital stay.
The average cost for one night in the hospital is between $1500-$3000 before any additional drugs or procedures that may be a part of your stay. The average hospital stay for seniors is 5.5 days.
Hospital indemnity plans can help make up for hundreds of dollars that you may be charged in the hospital. Your plan will have a set limit on the length of time you can spend in the hospital.
Hospital indemnity coverage can cost you as little as $12 per month depending on your financial needs and your potential for lengthy hospital stays. If you have or are eligible for a $0-premium Medicare Advantage plan with a high deductible, hospital indemnity insurance will help you cover those deductibles.
Everyone is eligible for hospital indemnity coverage, and your pre-existing conditions will not affect your ability to extend your coverage. One important note about hospital indemnity insurance is that you may have to wait for benefits used towards illnesses, but you most likely will not have to wait for accidental injury coverage.
How Does Hospital Indemnity Coverage Work?
To receive your benefits, you will need to make a claim immediately following your hospital stay, stating your expenses. You will receive a check directly in the mail from your carrier for a predetermined cash value (per hospital day).
For example, if your hospital copay is $400, you will need to pay $400 directly to the hospital. Your insurance carrier will then reimburse up to a certain amount, say, $250 depending on the specifics of your plan.
Since your reimbursement comes in the form of a check, you can use your hospital indemnity coverage for any services that you may need. Hospital costs are not limited to what shows up on your overnight bill. Consider the following additional costs:
Laboratory and radiology tests
Ambulance transportation
Emergency room costs
Outpatient surgeries
Hospital parking for you and any visitors
Post-hospital skilled nursing facilities
You can purchase hospital indemnity coverage at any time, but the closer you are to your Initial Enrollment Period (within the seven months surrounding 65th birthday), the lower your costs will be.
Start by setting up an appointment with your agent to discuss your options for ancillary insurance products that your Medicare plan does not cover.
Hospital Indemnity Insurance for Medicare Advantage
Private insurance carriers offer Medicare Advantage (MA) plans to cover many services Original Medicare does not. MA plans can offer coverage for services such as vision, dental and hearing in addition to hospital coverage and doctor’s appointments.
Hospital services, however, can still come with expensive copayments. You can use an indemnity policy to help relieve your out-of-pocket expenses and stay within your budget. Hospital indemnity coverage gives you a safety net to use in the event of a medical emergency.
Indemnity plans are different from PPOs because indemnity plans are not primary health insurance. For example, your PPO or HMO will often come with preventive services such as an annual wellness visit. Hospital indemnity insurance plans only reimburse all or part of your costs related to short-term care.
We Can Help You Find Hospital Indemnity Insurance Coverage
Hospital insurance can mean the difference between having huge hospital bills or paying a manageable premium and a deductible if you use hospital services.
A licensed agent with Medicare Plan Finder can help you find the policy you need to cover your healthcare needs. Call 844-431-1832or contact us here to arrange a meeting today.
This post was originally published on April 06, 2017, by Anastasia Iliou and was updated on May 30, 2019, by Troy Frink.
Prescription Help for Medicare Beneficiaries
For many people, prescription drugs are the most expensive part of health care. Some medications are so expensive that many people stop taking their prescriptions, and their health problems get worse. Thankfully, there are options for prescription help for Medicare beneficiaries.
Apply for LIS
You might be qualified for Extra Help, or Low Income Subsidy (LIS). Extra Help is a Medicare savings program based on income level. If your yearly income and total assets are at or below 150 percent of the federal poverty level, you may qualify for LIS. Some beneficiaries have saved nearly $4,000 per year by enrolling in LIS. If you’re not sure if you’re qualified, speak to your agent! We can help you look over the qualifications and go through the application process.
If you qualify for LIS, you might also qualify for Medicaid. If you’re eligible for both Medicare and Medicaid, you qualify for Dual Special Needs Plans (DSNP), which are a type of Medicare Advantage plan. DSNPs typically provide coverage for doctor appointments, hospital services and prescription medications.
If you have a DSNP, you will also qualify for a Special Enrollment Period (SEP), which allows you to enroll in new plans or make changes to your existing coverage at any time throughout the year, rather than having to wait for certain times.
Special Needs Plans | Medicare Plan Finder
Change Your Medicare Plan
If you don’t qualify for a SEP, you will have to wait for the Annual Enrollment Period (AEP) to make changes to your coverage or enroll in a new plan. Original Medicare does not provide prescription drug coverage. However, Medicare Part D or certain private insurance policies called Medicare Advantage plans cover medications and provide prescription help for seniors on Medicare.
Private insurance carriers offer Medicare Advantage (MA) plans to pick up where Original Medicare falls short. Along with prescription drugs, some MA plans can provide coverage for vision, dental, transportation and even fitness classes. Talk to your licensed agent to find a plan that fits your budget and lifestyle.
Medicare Advantage | Medicare Plan Finder
Consider a Plan With Gap Insurance
The donut hole is a limit on what your prescription drug plan will cover, and it applies to all Medicare clients who don’t have Extra Help. The donut hole will be going away in 2020, but for now, here’s a cost breakdown for 2019:
You will pay for 100 percent of your drug costs until you hit your deductible, which is $435 in 2020. Once you meet your deductible, you will only pay a small percentage of your drug costs until you’ve spent $4,020. At that point, you enter the you will pay up to 25 percent for brand-name drugs and up to 25 percent of generic drugs until you reach $6,350. At that point, you will only be responsible for five percent of your drug costs for the rest of the year.
Some Medicare plans offer additional coverage to protect you from the donut hole. That’s something you can ask your agent about when you meet to discuss your coverage options!
Rx Discount Card | Medicare Plan Finder
Request Generic Drugs
Most drugs that your doctor prescribes will have a generic counterpart that works just as well. In fact, the FDA requires that generic drugs have the same level of quality and performance as their brand name counterparts. Brand name drugs are more expensive because the companies that manufacture them had to pay for research and development. They pass those costs onto the consumer.
Ask your doctor if he or she prescribed a name-brand or a generic drug. If your doctor is willing to switch from a brand name to a generic, you might be able to save hundreds of dollars every year!
Let Us Help
Prescription help for seniors on Medicare can come from changing your Medicare Plan, Extra Help or from buying cheaper prescriptions. A highly trained licensed agent with Medicare Plan Finder can help you find a plan that’s right for you. To set up an appointment, call us at 844-431-1832 or contact us here today.
Find Medicare Plans | Medicare Plan Finder
This post was originally published on October 26, 2017, by Anastasia Iliouand was updated on May 23, 2019, by Troy Frink.
Can you get Medicare Overseas Coverage?
Are you planning a summer trip to Europe? Finally going on an African safari now that you’re retired? We hope you have some great vacation time planned, but we really hope you stay safe while you’re out there enjoying yourself! For the most part, Original Medicare will only cover your care that occurs within the United States (including Puerto Rico, The U.S. Virgin Islands, American Samoa, Guam, and The Northern Marina Islands), so it’s important to think about your healthcare options before you head abroad.
Original Medicare overseas coverage is extremely limited, but you will be covered if:
If you are in the U.S. during a medical emergency but a foreign hospital is closer
If you are in Canada on a direct route to Alaska (and far from an American hospital)
If you’re on a cruise ship and less than six hours from an American port
If you have a Medicare Advantage plan with foreign coverage
If you have a Medicare Supplement with foreign travel insurance
Do you have the coverage you need in case you get sick or injured while you’re out of the United States?
Medicare Advantage Foreign Travel Coverage
Private insurance carriers offer Medicare Advantage (MA) plans to add additional benefits to your Medicare coverage (and may include coverage abroad). Original Medicare only covers hospital and limited medical expenses, but MA plans can include dental, vision, meal delivery, fitness classes, and even foreign travel coverage.
There are thousands of MA plans to choose from, but not all of them include Medicare overseas coverage. MA plans are different in every state, county, and zip code. Reach out to us for more information on what’s available in your area.
Medicare Advantage | Medicare Plan Finder
Medicare Supplements Foreign Travel Insurance
Like MA plans, Medicare Supplement (Medigap) plans also offer coverage beyond Original Medicare. The difference is that MA plans cover medical expenses, but Medigap plans cover expenses such as deductibles and coinsurance. You cannot have a Medicare Supplement plan if you have a MA plan, so it’s smart to talk to a licensed agent to find out which type of plan is best for your budget and lifestyle.
Find Medicare Supplements | Medicare Plan Finder
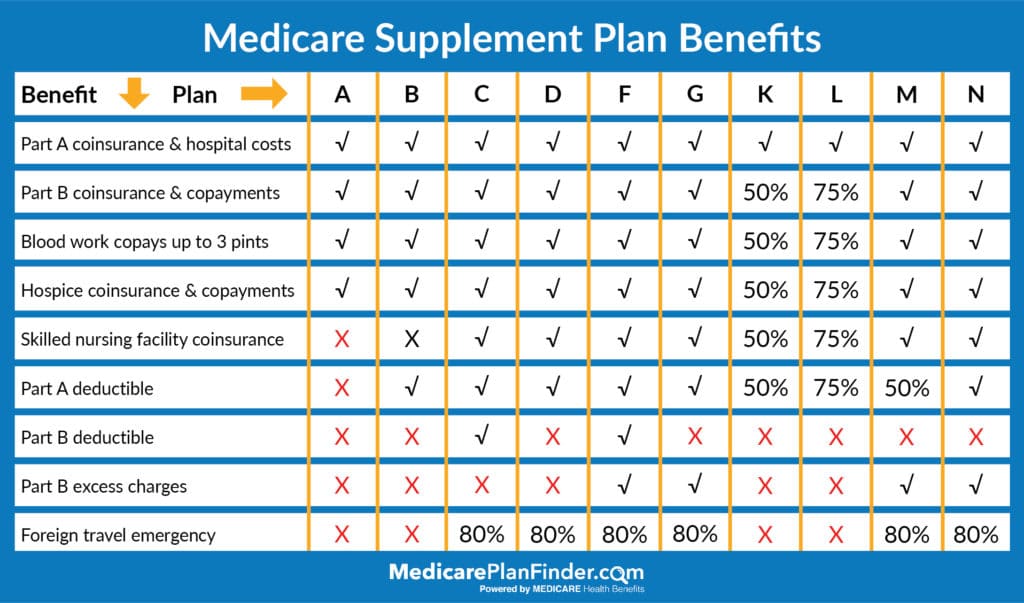
Medigap plans D, E, G, H, I, J, M, and N may cover up to 80 percent of your overseas costs if you meet the plan’s foreign travel deductible (plans C and F include this benefit as well but will be removed from the market in 2020). The expenses will only be covered if they occur within the first two months of your stay overseas, provided Original Medicare doesn’t already cover them. These Medigap plans come with a $50,000 lifetime limit on overseas travel insurance benefits.
Medicare Supplement Plans Comparison Chart | Medicare Plan Finder
How to Prepare for Traveling Abroad
Unfortunately, our planet is covered in bacteria and viruses that can harm our bodies. Those bacteria and viruses don’t live everywhere, though, which means our immune systems haven’t been exposed to them. Therefore, our bodies don’t know how to fight foreign diseases. That’s why you need vaccinations for foreign diseases before you leave the country.
Visit your primary care physician and tell them where you’re going and how long you’ll be there. Medicare will cover your pre-vacation doctor visit where he or she will give you a list of vaccinations to consider.
Along with getting the proper vaccinations before you travel, your doctor may recommend you bring medications for common illnesses you may find at your destination, or for other things that may ail you during your trip. For example, let’s say you’re going on a tropical cruise. Your doctor may recommend you bring mosquito repellant, sunscreen, and motion sickness medicine.
If you have concerns about serious injuries or illnesses during your vacation, consider purchasing a Medicare Advantage or Medigap plan that has coverage for foreign healthcare. You’ll have peace of mind knowing your treatment will be covered.
We Can Help
If you’re planning on traveling to an area where Original Medicare won’t cover your medical treatment, you might want to consider purchasing a plan with foreign travel insurance. If you have questions about Medicare overseas coverage, call an agent at 844-431-1832 or contact us here. We hope you stay safe and enjoy your travels!
Contact Us | Medicare Plan Finder
This post was originally published on June 01, 2017, and was updated by Troy Frink on May 20, 2019.
Mother’s Day Health Tips to Share with Your Senior Mother
Your mother has dedicated her life to caring for you, and as she ages, it’s time for the roles to reverse. The best gift any mother could ask for is for her children to be wonderful, caring adults! As you plan to celebrate this Mother’s Day with your mother, consider giving the gift of your support throughout the rest of her life.
Healthy Ways to Celebrate Mother’s Day
Whether your mom is at home, in a living facility, or a hospital, you can still enjoy a beautiful Mother’s Day with her. If the weather is nice and she is able, take her for a walk! Sunshine strengthens the bones and the immune system and reduces stress while inducing feelings of happiness. You can also take her to a healthy brunch. Skip the sugary, syrupy pancakes and take your mom to a place where she can enjoy some fresh fruit with oatmeal or yogurt or opt for eggs and toast.
Top Women’s Health Concerns
Even if you don’t want to think about your mother’s aging and her health on Mother’s Day, think about selecting a day to discuss these topics with her. The top concerns that aging women face are:
Look for symptoms of these ailments in your mother, and educate her on what to look out for. Certain things, like breast swelling, brittle bones, muscle pain, and memory loss can be easy to spot. Depression is one of the ailments that is hardest to notice, especially when you don’t see a person often. Some people are really good at hiding their depression symptoms. When you don’t see your mother for a few weeks or even months, she might act like her normal self around you and then go home and sleep all day because she’s mentally exhausted. Keep your mother’s spirits up and help her fight depression by ensuring that she is engaging in hobbies and activities, keeping some sort of a social life, and keeping some sort of responsibility, like keeping a garden or a pet, or even just keeping the house clean.
Top Aging Women’s Health Tips
The best things your mother can do (and you, too!) as she ages are:
Eat healthy
Stay smart about medications
Manage existing health conditions
Get screened
Stay active
Eating healthy is always easier said than done as we are tempted by the snack aisle in the grocery store and the beautiful pastry display at Starbucks. Remind your mother to enjoy everything in moderation and keep superfoods like leafy greens, berries, and avocados in her diet.
Pay close attention to her doctor’s or pharmacist’s instructions regarding medications. Help your mother avoid being one of the statistics for senior opioid abuse. On the same token, make sure your mother is taking her medications and properly managing her preexisting health conditions. Help her out by purchasing vitamins and supplements that she can take, making sure she is comfortable at home, and watching her sugar intake.
Seniors are likely to avoid trips to the doctor because they don’t have an easy way to get there or they simply forget to book their yearly appointment. Some don’t want to pay for it – but guess what? Medicare covers one yearly wellness exam at no cost to the patient. This is a good time for your mother to ask questions and a good time for her doctor to perform or schedule screenings for common ailments. Those screenings are usually covered, too, so there’s no excuse!
Lastly, make sure your mother is regularly taking walks and engaging in household chores to stay active.
Get Support While you Take Care of Mom
Providing care for a loved one is no easy task, but you are not alone. Caregiver support groups throughout the country can answer your questions, give you advice, and allow you to interact with other caregivers just like you. Consider reaching out to the Family Caregiver Alliance, a group that has worked since the late ’70s to support people like you. You can also reach out to the Caregiver Action Network. They are located in D.C. and spend a lot of time advocating for caregiver rights and laws.
We’ve put together information on caregiver networks and some of our own advice for taking care of your loved ones, here. We specialize in Medicare plans, so if your mother or someone else you know needs help finding a plan, don’t hesitate to reach out to Medicare Plan Finder. We work with all of the major plans so there is no bias and you are never obligated to buy. If you are the “Power of Attorney” for your mother, we can speak directly to you about her healthcare plans.
We hope you enjoy a beautiful Mother’s Day this year and we hope to speak with you soon regarding your or your mother’s care.
Preparing to Meet with an Insurance Agent
If you’re about to turn 65, or if it’s time for the Annual Enrollment Period, you’ve probably been inundated with marketing materials from insurance agents. You may wonder why all these people want to talk to you, or why you need them in the first place. Simply put, Medicare is confusing. There are thousands of options to choose from depending on your location, and enlisting the help of a licensed agent can help ensure that you have the best plan to fit your needs.
Why Licensed Agents who sell Medicare Plans Aren’t Door-to-Door Salespeople
Licensed insurance agents who sell Medicare cannot legally show up at your door or contact you unexpectedly. Medicare guidelines state that you, the client, has to know everything that’s going to happen ahead of time. Agents must schedule appointments with you in advance and clarify exactly what they will talk about with you in the meeting.
Licensed agents will not ask you for money. Rather, the insurance carrier you enroll with pays the agent a commission. You get the same insurance benefits at the same price whether you use a broker or not. However, using a broker comes with a host of benefits you won’t get if you enroll on your own.
Contact Us | Medicare Plan Finder
Benefits of Using a Broker for Medicare
Even if you already know what plan you want to sign up for, or even if you’ve already enrolled in a plan, it’s wise to talk to an insurance agent who knows what else may be out there for you. The world of Medicare is saturated with plans and policies, and you might be missing out! Your agent might be able to find a plan that covers a service you didn’t even consider such as fitness classes.
Not only will you see more plan options, you get a qualified professional who is an expert in Medicare. Your agent will only talk to you about plans that will work for you, so you’ll only get the coverage you need at a price you can afford. The broker will show up at your house already having vast knowledge about the plans that you can enroll in, saving you lots of time.
Should I use a Broker to get Health Insurance?
Agents legally need to be qualified to sell insurance before they can take action, which means they will have gone through months of training to know all there is to know about Medicare. Their job is to talk about several different options for you based on what kind of coverage you need, then help you select the best one.
All senior citizens must enroll in Medicare within their Initial Enrollment Period (IEP), which is the seven-month period surrounding their 65th birthday. If you miss that window, you may be charged a 10 percent penalty fee when you eventually do enroll. If you don’t enroll at all, you could spend hundreds of thousands of dollars more than you should on healthcare.
After your Initial Enrollment Period, you can make changes during the Annual Enrollment Period (AEP), which is every year from October 15 through December 7. If you haven’t met with a broker yet, this is a good time to do so. If you already have a broker, this is a good time to meet and discuss whether or not there is a better plan for you for the following year.
What Can I Expect to Happen During the First Meeting?
The agent will come prepared with materials that are loaded with information on different carriers and their policies. He or she will go over that information with you, and let you make a decision. He or she may also bring an enrollment form for your convenience in case you decide on a plan that day, but you are under no obligation to enroll.
The agent is not allowed to discuss plan options that you didn’t previously agree to discuss in the meeting. For instance, if you agree to speak about Medicare Advantage plans only, the agent will not try to sell you a vision plan. You will need to sign a “scope of appointment” form prior to the meeting that outlines what the agent can speak to you about.
How can I Prepare for the Meeting?
First, compile a list of your healthcare costs and needs, like what prescriptions you take and which doctors you like to see. Do you need coverage for specific medical conditions such as heart disease or have a family history of stroke or heart attack? Write that down. Also, think about your monthly budget. How much can you afford to spend on premiums? How much do your medical bills typically cost? Your meeting will run as quickly and smoothly as possible if you go in prepared.
Why You Should Choose Medicare Plan Finder
Everything we do at Medicare Plan Finder is geared toward our mission to serve the underserved. We want you to understand your coverage, so we provide you with valuable information on our social media pages and on this website. We put our agents through extensive training so they can better serve you. We work with a wide variety of Medicare insurance carriers so our agents can give you multiple quotes to choose from. We take the guesswork out of finding Medicare coverage so you can receive the best possible care.
Contact Us Today
It can be nervewracking to have someone come into your home and talk to you about your healthcare, but it really is the right decision. A licensed agent will take you through the enrollment process step by step and help make sure you have the right plan for you. Call 844-431-1832 or fill out this form to set up a no-obligation appointment today.
Contact Us | Medicare Plan Finder
This post was originally published on April 20, 2017, by Anastasia Iliou and was updated by Troy Frink on May 09, 2019, by Troy Frink.
Life and Final Expense Insurance
Though it may be unsettling to think about, your Medicare plan does not cover the high costs that come with death. It is important for you to figure out your life insurance plan now. That way, your loved ones won’t have to break their piggy banks to pay for your final expenses.
Your Insurance Options to Consider
Life insurance can be used either to help your loved ones after you die or to give you extra money to fall back on if you are diagnosed with a chronic or terminal illness. The right life insurance policy will give you peace of mind by minimizing your family’s financial burden.
Life insurance comes in two forms:
Whole Life: valid for your entire life and potentially the days following your death
Term Life: valid for a set amount of time, typically up to 30 years
There are two types of whole life insurance policies. If you’re 60 or older, a universal life insurance policy (a lifelong policy that gathers cash value as it endures) may be your best option, because you can make changes to the money you leave behind based on your ever-changing needs. If you’re 70 or older, you might need your insurance policy to cover medical expenses, and you may want to leave a set amount for your loved ones. In that case, a guaranteed universal life (a universal life insurance policy that gathers a guaranteed amount over time) will be your best option.
You may want to consider a term life plan if you are suffering from a temporary illness or injury and will not need the same amount of coverage for the next year or decade. Speak to an agent to determine which form of life insurance is best for you and your needs.
Contact Us | Medicare Plan Finder
Difference Between Final Expense and Life Insurance
Final expense policies are solely for covering costs associated with funerals, burials/cremations, and sometimes medical bills for your final hours. Having final expense insurance means that when you die, your appointed beneficiary (typically a spouse or close relative) will receive reimbursement for your expenses. You will usually have the ability to change your beneficiary after your policy has been active for a year.
While final expense insurance will help cover final medical and burial or cremation costs, life insurance will help to support the family members you leave behind who may have been counting on your paycheck. It can pay for any outstanding debt, such as a mortgage.
Essentially, life insurance provides more coverage and can be used for far more than final expenses. Remember the differences between the two types of policies:
Though final expense and life insurance are very similar, they do come in the form of two separate policies. Original Medicare does not cover either one. However, you can set up a Medicare Advantage Health Savings Account (HSA), which is like a bank account for medical expenses. You can make sure that unused funds go towards your final expenses for a loved one.
Costs of Life and Final Expense Insurance for Seniors
Final expense insurance can cost anywhere from $5,000 to $50,000 depending on your age and health at the time of purchase. Life insurance will cost more or less depending on how high you want to set your policy value. The cost of life insurance depends on your age – basically, the younger you are, the cheaper your policy, so you’ll want to act as soon as possible. Policies can cost as little as $14 per month. Term life insurance can be the most affordable for seniors, but remember that the policy will not provide any benefit to your loved ones after you pass away.
Does Medicare Help Pay for Funeral Expenses?
No, Original Medicare doesn’t pay for funeral expenses or either burial or cremation costs when a beneficiary passes away. Medicare is only for medical expenses, so you’ll want additional insurance to make sure all of your final expenses are taken care of. While Medicare Parts A and B do not allow for your loved ones to receive money after you die, you can set up a high-deductible Medicare Advantage plan called a Medicare Medical Savings Account and dictate that your beneficiary gets any unused funds.
Social Security Benefits
When someone who collects Social Security benefits dies and leaves a spouse or child (usually a minor under 18) behind, the surviving beneficiary receives a one-time lump sum of $255. That money – called a death benefit – can be applied to funeral or burial/cremation expenses. Funerals usually cost much more than $255, so you won’t be able to rely on Social Security to take care of your family. A final expense policy can more than make up the difference and cover the cost of your funeral.
Final Expense Carriers We Work With
Medicare Plan Finder plan finder benefits advisors are here for you. We work with a variety of final expense insurance carriers so we can provide you with options and help find the best policy for your situation, including:
Aetna
AIG
American Amicable
Cigna
Foresters
Gerber
Great Western
Mutual of Omaha
Prosperity Life
Renaissance Life
TransAmerica
Contact Us Today
You don’t want your loved ones to be faced with a tremendous financial burden on top of losing you. Talk to a Medicare Plan Finder benefits advisor about not only finding the right Medicare plan for you, but also the right life and final expense policies for you. Call us at 844-431-1832or contact us here to arrange a no-obligation meeting today.
Contact Us | Medicare Plan Finder
This blog was originally published on March 30, 2017, by Anastasia Iliou and was updated by Troy Frink on May 06, 2019.