Medicare Advantage and Medicare Supplement Insurance, also called Medigap, are two different ways to manage your Medicare coverage and healthcare costs.
Medicare Advantage may be a good fit if you want lower monthly premiums, prescription drug coverage, and additional benefits such as dental, vision, and hearing. Medicare Supplement insurance may be a better fit if you want more flexibility when choosing doctors and more predictable out-of-pocket costs for Medicare-covered services.
Neither option is automatically better. The right choice depends on your healthcare needs, budget, preferred doctors, prescription medications, and how often you travel.
Let’s compare how they work, what they cost, and the important differences to consider before choosing a plan.
Medicare Advantage vs. Medicare Supplement: Key Differences
Feature
Medicare Advantage
Medicare Supplement (Medigap)
How coverage works
Private plan provides your Part A and Part B benefits
Works alongside Original Medicare
Monthly premiums
Some plans have $0 premiums
Separate monthly Medigap premium
Medicare Part B premium
Generally still required
Still required
Doctor networks
Often uses HMO or PPO networks
Generally any provider nationwide who accepts Medicare
Prescription drugs
Included in most plans
Requires separate Part D coverage
Dental, vision, and hearing
Often includes additional benefits
Generally not covered
Out-of-pocket costs
Copays, coinsurance, and deductibles vary by plan
Helps pay certain Original Medicare cost-sharing expenses
Annual out-of-pocket limit
Yes, for covered Part A and Part B services
Depends on the Medigap plan; Plans K and L have specific limits
Referrals and prior authorization
May be required
Original Medicare generally does not require prior authorization
Travel within the U.S.
Coverage rules and networks vary
Broad access to Medicare-accepting providers
Foreign travel
Limited; some plans offer emergency benefits
Some plans cover limited foreign travel emergencies
Compare Plans from All Carriers in 1 Minute!
The biggest difference is how you receive your Medicare benefits.
With Medicare Advantage, a private insurance company administers your Medicare coverage. With Medigap, you keep Original Medicare and purchase additional insurance to help pay certain costs Medicare leaves behind.
You cannot use Medicare Advantage and Medigap together to cover the same healthcare expenses.
What Is Medicare Advantage?
Medicare Advantage plans, also known as Medicare Part C, are offered by private insurance companies approved by Medicare.
To enroll in Medicare Advantage, you must have Medicare Part A and Part B. Once enrolled, you receive most of your Medicare-covered healthcare services through your Medicare Advantage plan rather than through Original Medicare.
Medicare Advantage plans must cover medically necessary services covered by Original Medicare, with certain exceptions such as hospice care, which remains covered by Original Medicare.
Many Medicare Advantage plans also offer benefits beyond Original Medicare.
Depending on the plan and your eligibility, additional benefits may include:
Not every Medicare Advantage plan includes these benefits. Coverage amounts, restrictions, and eligibility requirements vary.
Types of Medicare Advantage Plans
Two common types of Medicare Advantage plans are HMOs and PPOs.
Health Maintenance Organization (HMO):Medicare Advantage HMO plans generally require you to use doctors and hospitals within the plan’s network, except in certain circumstances such as emergencies. You may also need referrals to see specialists.
Preferred Provider Organization (PPO):Medicare Advantage PPO plans generally provide greater flexibility to see out-of-network providers, although you may pay more for those services.
Other Medicare Advantage options include Private Fee-for-Service plans and Special Needs Plans.
Plan availability depends on where you live.
How Much Does Medicare Advantage Cost?
Some Medicare Advantage plans have monthly premiums as low as $0. However, a $0 plan premium does not mean healthcare is free.
You generally must continue paying your Medicare Part B premium, although some Medicare Advantage plans may help pay part or all of that premium.
You may also pay deductibles, copayments, or coinsurance when receiving medical services.
One important protection is that Medicare Advantage plans have an annual out-of-pocket maximum for covered Part A and Part B services.
Once you reach your plan’s applicable limit, you generally pay nothing for covered Part A and Part B services for the remainder of the year.
Prescription drug costs and monthly premiums do not count toward this medical out-of-pocket maximum.
Compare Plans from All Carriers in 1 Minute!
What Is Medicare Supplement Insurance (Medigap)?
Medicare Supplement Insurance, commonly called Medigap, is private insurance designed to help pay certain out-of-pocket expenses associated with Original Medicare.
Original Medicare covers many hospital and medical services, but beneficiaries may still be responsible for deductibles, copayments, and coinsurance.
Medigap helps pay some of these remaining expenses, depending on the policy you select.
For example, Original Medicare generally pays 80% of the Medicare-approved amount for covered Part B services after you meet the deductible.
Certain Medigap plans can pay the remaining 20%, reducing your out-of-pocket expenses.
Unlike Medicare Advantage, Medigap does not replace the way you receive your Original Medicare benefits.
You keep Medicare Part A and Part B, and your Medigap policy supplements that coverage.
What Does Medigap Cover?
Medigap benefits depend on the standardized plan you purchase.
Depending on the plan, coverage may help pay:
Medicare Part A hospital coinsurance
Medicare Part A deductible
Medicare Part B coinsurance or copayments
Skilled nursing facility coinsurance
Hospice care cost sharing
Certain foreign travel emergency expenses
Medigap policies generally do not cover routine dental care, vision care, hearing aids, long-term care, or private-duty nursing.
They also do not cover your monthly Medicare Part B premium.
Understanding Medigap Plans
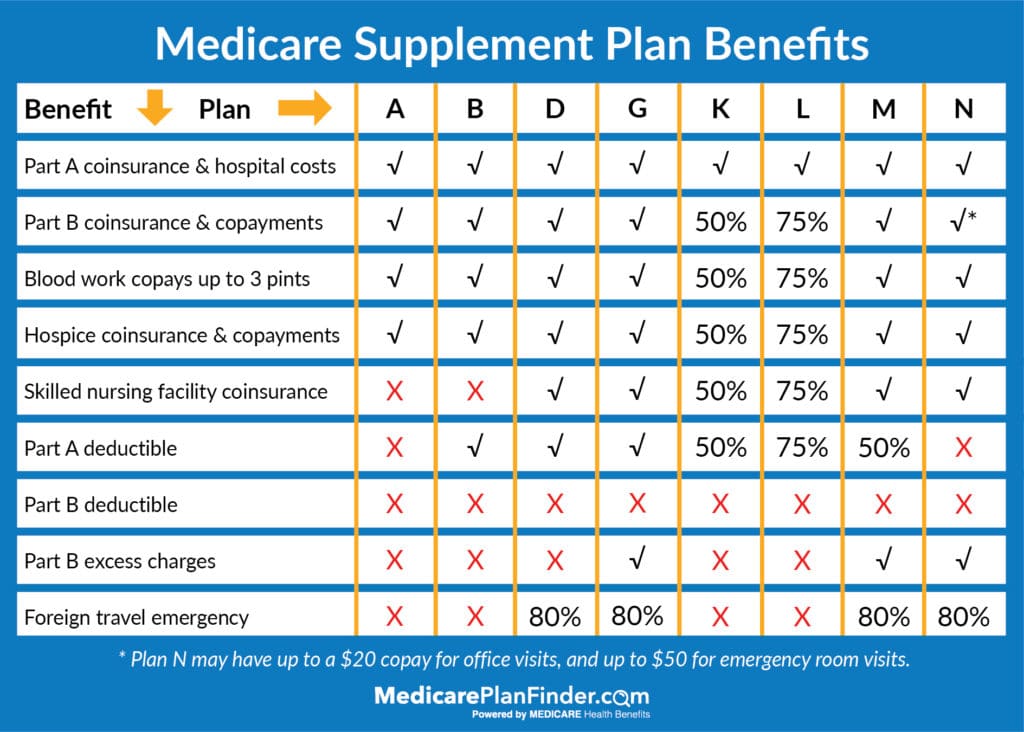
In most states, Medigap policies are standardized using letters such as Plan A, Plan B, Plan G, and Plan N.
For example, a standard Medigap Plan G from one insurance company provides the same basic medical benefits as a standard Plan G from another insurance company.
However, the monthly premiums can be very different.
Massachusetts, Minnesota, and Wisconsin use different Medigap standardization rules.
Two popular options to compare are Plan G and Plan N.
Plan G provides extensive coverage of Original Medicare cost-sharing expenses, although you remain responsible for the Part B deductible.
Plan N also provides substantial coverage but may require certain office visit and emergency room copayments, and it does not cover Part B excess charges.
Medigap Plan F is another comprehensive option, but it generally is not available to people who became eligible for Medicare on or after January 1, 2020.
How Much Does Medigap Cost?
With Medigap, you generally pay three separate premiums or costs:
Your monthly Medicare Part B premium.
Your monthly Medigap policy premium.
Your separate Medicare Part D prescription drug plan premium, if you enroll in one.
You may also have certain deductibles or other out-of-pocket costs depending on your Medigap policy.
Although Medigap generally involves higher monthly premiums than many Medicare Advantage plans, it can make expenses for Medicare-covered healthcare services more predictable.
Medigap premiums vary by insurance company, location, age, pricing method, and other factors. Premiums may also increase over time.
Compare Plans from All Carriers in 1 Minute!
Is Medicare Advantage Cheaper Than Medigap?
Medicare Advantage often has a lower monthly premium than Medigap, but that does not necessarily mean it will cost less over an entire year.
Consider two hypothetical situations.
Example 1: Someone who rarely visits the doctor
A relatively healthy Medicare beneficiary might choose a Medicare Advantage plan with a $0 monthly plan premium.
If they only need preventive care and a few doctor visits, their total annual medical expenses could be relatively low.
In this situation, paying a separate monthly Medigap premium might cost more.
Example 2: Someone who needs frequent medical care
Another beneficiary might see multiple specialists, receive ongoing treatments, and require regular outpatient procedures.
With Medicare Advantage, copayments and coinsurance could add up throughout the year, subject to the plan’s annual medical out-of-pocket maximum.
With Original Medicare and a comprehensive Medigap policy, many of those Medicare-covered expenses could be paid by the supplemental policy.
In this situation, paying a higher monthly premium might result in more predictable healthcare expenses.
Neither example guarantees that one option will be less expensive.
The important comparison is your total expected annual cost, including premiums, prescription medications, and out-of-pocket expenses.
Which Offers More Freedom to Choose Doctors?
Doctor access is one of the most important differences between Medicare Advantage and Medigap.
With Original Medicare and most Medigap policies, you can generally visit any doctor or hospital in the United States that accepts Medicare.
This can be particularly valuable if you travel frequently, spend part of the year in another state, or receive treatment from multiple specialists.
Medicare Advantage plans often operate through provider networks.
An HMO may require you to use network providers for most non-emergency services. A PPO may allow out-of-network care, but your costs can be higher.
Medicare Advantage plans may also require prior authorization for certain services.
Before enrolling, confirm that your preferred doctors, hospitals, and specialists participate in the plan and that your prescriptions are covered.
Which Is Better for Someone With Chronic Health Conditions?
If you have a chronic medical condition, your decision deserves additional attention.
Someone managing diabetes, heart disease, cancer, or another ongoing condition may need regular appointments, specialized treatments, medications, or hospital services.
Medigap may appeal to someone who wants broad access to Medicare-accepting providers and predictable cost sharing.
Medicare Advantage may appeal to someone who wants coordinated care, additional benefits, or access to a Special Needs Plan designed for certain qualifying conditions.
The best choice depends on the actual plans available to you and the providers and services you need.
It’s also important to consider future coverage flexibility.
Can You Switch From Medicare Advantage to Medigap?
You may be able to switch from Medicare Advantage back to Original Medicare during an applicable Medicare enrollment period.
However, that does not necessarily mean you can purchase any Medigap policy you want.
In most states, your best opportunity to purchase Medigap without medical underwriting is your six-month Medigap Open Enrollment Period, which begins when you are both 65 or older and enrolled in Medicare Part B.
Outside that period, insurance companies may be able to consider your health history when deciding whether to issue a policy or how much to charge.
Certain federal and state guaranteed issue protections provide exceptions.
This is an important consideration for someone thinking about enrolling in Medicare Advantage now and purchasing Medigap later.
Medicare Advantage vs. Medigap: Which Should You Choose?
Medicare Advantage may be worth considering if:
You want to keep your monthly plan premium low.
Your preferred doctors participate in the plan’s network.
You want prescription drug coverage included in the same plan.
You value additional dental, vision, hearing, or fitness benefits.
You are comfortable with the plan’s provider network and cost-sharing rules.
Medigap may be worth considering if:
You want broad access to doctors who accept Medicare.
You frequently travel or spend time in multiple states.
You prefer more predictable expenses for Medicare-covered services.
You are comfortable paying a separate monthly supplemental insurance premium.
You want to minimize certain deductibles, copayments, and coinsurance.
Remember that your health needs and financial circumstances can change over time.
The least expensive option today may not be the most appropriate option several years from now.
Frequently Asked Questions About Medicare Advantage vs. Supplemental Plans
Is Medicare Advantage better than Medigap?
Neither is universally better. Medicare Advantage may offer lower premiums and additional benefits, while Medigap can provide broader provider access and more predictable cost sharing for Original Medicare services.
Can I have both Medicare Advantage and Medigap?
No. Medigap cannot be used to pay Medicare Advantage deductibles, copayments, or coinsurance. These are different coverage arrangements.
Does Medigap cover prescription drugs?
Medigap policies sold today do not include prescription drug coverage. You can generally purchase a separate Medicare Part D plan while enrolled in Original Medicare.
Do Medicare Advantage plans have a maximum out-of-pocket limit?
Yes. Medicare Advantage plans have annual limits on out-of-pocket expenses for covered Part A and Part B services. The limits vary by plan and do not include all healthcare expenses.
Can I see any doctor with Medigap?
With Original Medicare and most Medigap policies, you can generally see any doctor nationwide who accepts Medicare. Medicare SELECT policies are an exception and may have network requirements.
Is Medigap worth the monthly premium?
It depends on how much you value predictable healthcare expenses, provider flexibility, and protection against certain Original Medicare cost-sharing obligations. Comparing your total annual costs can help you decide.
Compare Medicare Advantage and Medicare Supplement Plans in Your Area
Choosing between Medicare Advantage and Medigap is an important decision, but you don’t have to make it based on general information alone.
Plans, premiums, provider networks, and benefits vary by location and insurance company.
At Medicare Plan Finder, you can explore your coverage options and compare plans available in your area.
Before enrolling, review your doctors, prescriptions, expected healthcare needs, and total potential costs.
Compare Medicare plans in your ZIP code or call (833)-567-3163 to discuss your options.
Compare Plans from All Carriers in 1 Minute!
Original Medicare vs. Medicare Advantage
Original Medicare and Medicare Advantage are two ways to receive Medicare coverage. Both provide Medicare Part A and Part B benefits, but they differ in how you receive care, what you pay, and whether you use provider networks. Understanding those differences can help you choose coverage that fits your doctors, prescriptions, budget, and travel needs.
Original Medicare vs. Medicare Advantage: At a Glance
Feature
Original Medicare
Medicare Advantage (Part C)
Who provides coverage?
Federal Medicare program
Private insurance companies approved by Medicare
Hospital and medical benefits
Part A and Part B
Includes all medically necessary Part A and Part B services, except hospice care, which Original Medicare generally covers
Doctors and hospitals
Generally any provider nationwide that accepts Medicare
Often uses provider networks; rules vary by plan type
Prescription drugs
Usually add a separate Part D plan
Many plans include Part D coverage
Additional benefits
Generally does not cover routine dental, vision, or hearing services
Some plans offer additional dental, vision, hearing, or fitness benefits
Monthly premiums
Part B premium and Part A premium if applicable; optional Part D and Medigap premiums
Continue paying Part B premium and any additional plan premium
Out-of-pocket limit
No annual limit for Part A and Part B costs without supplemental coverage
Annual limit for covered Part A and Part B services under the plan
Medigap eligibility
May be paired with a Medigap policy
Cannot use Medigap to pay Medicare Advantage costs
What Is Original Medicare?
Original Medicare is the federal health insurance program that includes Part A (hospital insurance) and Part B (medical insurance). Medicare generally serves people age 65 and older and some younger people with qualifying disabilities or conditions.
Part A generally helps cover qualifying inpatient hospital stays, skilled nursing facility care, hospice care, and certain home health services. Part B generally helps cover medically necessary doctor services, outpatient care, preventive services, and durable medical equipment.
With Original Medicare, you can generally visit any doctor or hospital in the United States that accepts Medicare. You typically pay deductibles and coinsurance. For many Part B services, your share is 20% of the Medicare-approved amount after the deductible, although cost sharing varies by service.
Pros and Cons of Original Medicare
Broad provider access: You can generally see any provider nationwide who accepts Medicare, without a plan network.
Supplemental coverage options: You may be able to purchase a Medicare Supplement (Medigap) policy to help with certain out-of-pocket costs.
Separate drug coverage: You usually need a stand-alone Part D plan if you want Medicare prescription drug coverage.
No annual out-of-pocket maximum: Original Medicare alone does not cap your annual Part A and Part B spending.
Compare Plans from All Carriers in 1 Minute!
What Is Medicare Advantage?
Medicare Advantage, also called Medicare Part C, is an alternative way to receive your Medicare Part A and Part B benefits through a private insurance company approved by Medicare. You must have both Part A and Part B to join a Medicare Advantage plan.
Many Medicare Advantage plans include Part D prescription drug coverage and may offer extra benefits, such as routine dental, vision, hearing, or fitness services. Availability, benefits, costs, and provider networks vary by plan and location. You generally continue to pay your Part B premium, even if the Medicare Advantage plan has a $0 additional monthly premium.
Common Medicare Advantage Plan Types
HMO: A Health Maintenance Organization plan generally uses a provider network and may require referrals for certain specialist visits. Emergency and urgent care rules differ from routine care. Learn more about Medicare Advantage HMOs.
PPO: A Preferred Provider Organization plan generally lets you see providers outside its network, although your costs may be higher. PPOs generally do not require specialist referrals. Learn more about Medicare PPO plans.
Pros and Cons of Medicare Advantage
Predictable annual limit: Plans have an annual out-of-pocket maximum for covered Part A and Part B services. This limit does not include every expense, such as premiums or Part D drug costs.
Potential extra benefits: Some plans include services that Original Medicare generally does not cover.
Provider network considerations: Depending on your plan, you may need to use in-network doctors or obtain prior authorization for certain services.
Annual changes: Premiums, copays, drug formularies, networks, and benefits can change from year to year.
How Does Medigap Fit Into the Comparison?
Medicare Supplement Insurance, also called Medigap, is different from Medicare Advantage. Medigap is private supplemental insurance designed to help pay certain out-of-pocket costs under Original Medicare, such as deductibles and coinsurance. You cannot use a Medigap policy to cover costs under a Medicare Advantage plan.
Medigap policies sold today do not include prescription drug coverage. People who want drug coverage with Original Medicare and Medigap can generally consider a separate Part D plan. Eligibility to buy a Medigap policy, and whether an insurer can use medical underwriting, depend on enrollment timing and applicable state and federal rules.
Which Option May Be Better for You?
Original Medicare may appeal to people who value broad access to doctors nationwide or want to pair Medicare with a Medigap policy. Medicare Advantage may appeal to people who prefer an all-in-one plan with an annual medical out-of-pocket limit and potentially additional benefits, provided their preferred doctors, hospitals, and medications are covered.
Compare the total annual cost, not just the monthly premium. Review your prescriptions, preferred pharmacies, doctors, hospitals, expected medical needs, and how often you travel. There is no single best option for everyone.
Compare Plans from All Carriers in 1 Minute!
When Can You Change Medicare Coverage?
Medicare’s annual Open Enrollment Period runs from October 15 through December 7. During this period, eligible Medicare beneficiaries can generally switch between Original Medicare and Medicare Advantage or make changes to Medicare Advantage and Part D coverage for the following year. Other enrollment periods may apply depending on your circumstances.
Before switching from Medicare Advantage to Original Medicare, check whether you can obtain a Medigap policy on acceptable terms. Outside certain guaranteed-issue situations, Medigap insurers may be allowed to use medical underwriting, depending on your state and circumstances.
Frequently Asked Questions
Is Medicare Advantage the same as Original Medicare?
No. Original Medicare is administered by the federal government. Medicare Advantage plans are offered by private insurers approved by Medicare and provide your Part A and Part B benefits through the plan.
Can I have both Medicare Advantage and Medigap?
You cannot use a Medigap policy to pay Medicare Advantage plan costs. Medigap is designed to work with Original Medicare.
Do Medicare Advantage plans replace my Part B premium?
No. You generally must continue paying your Part B premium, even if your Medicare Advantage plan has a $0 additional premium. Some plans may offer a Part B premium reduction.
Do all Medicare Advantage plans include prescription drug coverage?
No. Many do, but not all. Check each plan’s drug coverage and rules before enrolling.
Need help reviewing your options? Compare plans available in your area and speak with a licensed insurance agent about your coverage needs.
Originally published September 20, 2018. Revised October 2026.
Additional Benefits with Medicare Advantage Plans: What You Need to Know
When exploring Medicare options, Medicare Advantage plans stand out due to their potential to offer benefits beyond what Original Medicare covers. These additional benefits can significantly enhance your healthcare coverage, but it’s important to remember that not all Medicare Advantage plans are the same. Each plan varies in the additional benefits offered, making it crucial for beneficiaries to compare plans carefully based on their health needs and preferences.
Understanding Medicare Advantage Plans
Medicare Advantage plans are offered by private insurance companies approved by Medicare. They provide all the benefits of Medicare Part A and Medicare Part B, often combined with other health services that Original Medicare does not cover. The inclusion of additional benefits is one of the primary reasons these plans have gained popularity among Medicare beneficiaries.
Types of Additional Benefits
Dental, Vision, and Hearing Care
Most notably, many MA plans include coverage for dental, vision, and hearing care—services not covered by Original Medicare. Dental benefits might cover routine check-ups, cleanings, x-rays, and even some types of dental surgery. Vision care often includes eye exams, glasses, or contact lenses, while hearing care might cover hearing aids and auditory exams.
Wellness Programs
Many plans incorporate wellness programs such as fitness memberships or discounts on health and wellness services. These benefits are designed to promote a healthy lifestyle among seniors, which can help prevent or manage common diseases associated with aging.
Over-the-Counter Allowances
Some MA plans offer allowances for over-the-counter (OTC) products such as vitamins, pain relievers, and first aid supplies. This benefit can be particularly helpful as it reduces out-of-pocket costs for everyday health items.
Telehealth Services
With the growing popularity of digital health services, many MA plans now include telehealth benefits, allowing beneficiaries to consult with healthcare providers from the comfort of their homes. This is especially beneficial for those with mobility challenges or those living in remote areas.
Transportation Benefits
Transportation to and from healthcare facilities can be a significant hurdle for many seniors. Some MA plans offer transportation benefits, which can be a deciding factor for those who do not have easy access to transportation or who are unable to drive.
Nutritional Support
Recognizing the importance of nutrition in health, some plans provide benefits aimed at nutritional support, including meal deliveries, especially after hospital stays, or nutritionist consultations to help manage dietary needs.
Choosing the Right Plan
When selecting a Medicare Advantage plan, consider the following steps:
Assess Your Health Needs: Understand your specific health requirements—do you need regular vision or dental services, or are you managing a chronic condition that might benefit from wellness programs?
Compare Plans in Your Area: Not all plans are available in every location, and benefits can vary widely between plans. Use the Medicare Plan Finder tool or consult with a licensed insurance advisor to compare the plans available in your area.
Read the Fine Print: Once you’ve narrowed down your choices, look closely at the plan’s summary of benefits to understand what is and isn’t covered, and at what cost. Pay attention to any specific limitations or rules regarding how you can use the benefits.
Check Provider Networks: Ensure that your preferred doctors and hospitals are included in the plan’s network. Medicare Advantage plans often have network restrictions, and going out of network can result in higher out-of-pocket costs.
Review Star Ratings: Medicare rates plans based on quality and performance. These ratings can help you understand the quality of care and customer service you can expect from different plans.
Conclusion
Medicare Advantage plans can offer a range of additional benefits that enhance your healthcare experience, but the key is to choose wisely based on your personal health needs and circumstances. By doing thorough research and understanding the specifics of each plan, you can find a Medicare Advantage plan that not only meets your health needs but also enhances your quality of life through additional benefits.
Does Medicare Cover the Cost of Hip Replacement Surgery?
An estimated 2.5 million Americans have undergone total hip replacements. Conditions such as osteoarthritis and rheumatoid arthritis can cause the hip joint to wear down so much that a hip replacement may be the only course of action to improve your mobility.
The total cost of hip replacement surgery can be staggering if you don’t have help from insurance. How much does a hip replacement cost with insurance?
A total hip replacement costs anywhere from $32,000 to $45,000, based on general coverage guidance from healthcare.gov. The total cost usually includes everything from the surgeon’s initial evaluation to post-operation hospital care.
Increases in year-to-year costs are small under stable economic conditions. There was only a small increase in hip replacement 2019 costs compared to medicare hip replacement 2018 costs.
If you’re one of the millions of Americans who needs a hip replacement, you may wonder, “Does Medicare cover hip replacements?” Yes, but you have to meet certain eligibility requirements, and you may still have some out-of-pocket costs even with Original Medicare.
You may also be asking, “How much does Medicare pay for hip replacement surgery?” The good news is that it will cover at least some of all types of costs.
Find Medicare Plans | Medicare Plan Finder
How Much Does Medicare Pay for Hip Replacement Surgery?
Cost of Hip Replacement Surgery with Medicare | Medicare Plan Finder
The likelihood of needing hip replacement surgery increases with age. Seniors 65 and older, people with ALS or ESRD, or people who have received SSDI for at least 25 months qualify for Medicare.
Original Medicare (Parts A and B) will help cover the cost of hip replacement surgery if your doctor determines it’s medically necessary because other treatments have failed. The answer to how much Medicare pays for hip replacement surgery will depend on whether it is medically necessary and what types of coverage you have.
Medicare Hip Replacement Costs With Medicare Part A
Medicare Part A is hospital insurance. This Medicare coverage helps pay for a semi-private room, meals and nursing care during your stay.
Part A will only cover a private room if your doctor says it’s medically necessary or it’s the only room available.
Medicare hip replacement reimbursement includes skilled nursing care after your surgery. Part A helps cover the first 100 days of in-patient care including physical therapy.
The Medicare Part A deductible can apply, and you may be responsible for copays or coinsurance.
Part B Coverage for Hip Replacement Surgery
Medicare Part B will help cover medical expenses such as doctor’s fees for the initial evaluation and post-op visits, surgery in an outpatient surgical facility, and outpatient physical therapy.
You may be responsible for paying the Part B deductible, which was $185 in 2019, and 20% of the Medicare-approved costs. Medicare Part B may also cover your post-operative durable medical equipment (DME) such as a cane or in-home grab bars.
Medicare Part D Coverage
Original Medicare does not cover post-op prescription drugs, but Medicare Part D includes prescription drug coverage. Your doctor may prescribe blood thinners to prevent clotting or painkillers to take during your recovery.
You can use Medicare Part D or private health insurance plans to cover prescription drugs.
Will Medicare Help Pay for a Knee Replacement?
Medicare Part A and Medicare Part B each cover a different aspect of joint replacement surgery. Medicare Part C will cover knee replacement, including both knees at once, only if your doctor considers it necessary.
Medicare Part D prescription drug program will cover the cost of painkillers, antibiotics, and anticoagulants required for the surgery.
What Medicare Advantage and Medicare Supplements Cover
Private insurance plans offer Medicare Advantage (MA) plans, and they are a great way to get all of the Part A and Part B benefits along with some unexpected offerings such as meal delivery, non-emergency transportation, vision and dental insurance.
Certain MA plans even cover prescription drugs! You will pay a monthly premium with MA plans, but some are as low as $0. Coverage varies depending on your location and the plans available, so look for a qualified professional to help you sort through the plans in your area and find the right one.
Medicare Supplement (Medigap) plans pick up where Original Medicare leaves off. Like MA plans, private insurance companies offer Medigap plans.
The difference is that Medigap Plans only cover your financial responsibilities such as coinsurance and deductibles. You cannot have both a Medicare Supplement and a Medicare Advantage plan at the same time, so it’s important to find out which one is best for you.
Medicare Supplement Insurance plans work with Medicare Part A and Medicare Part B to cover out-of-pocket costs for Medicare hip replacements.
Post-Hip Replacement Surgery Costs
Does medicare cover rehab after hip replacement? Yes. Sometimes, after hip replacement surgery, you may need some help.
For example, throughout your recovery, you might need orthotic devices or other equipment to help you get around. Medicare may cover those devices if your doctor says that they are medically necessary.
Some Medicare Advantage plans may provide extra coverage, and Medicare Supplement plans may cover your copayments for devices.
You also might be interested in Medicare Advantage plans that have an OTC or over-the-counter benefit. This can help offset some of your costs related to pain medication and other items you need to pick up from your pharmacy for your recovery.
Additionally, some people may need physical therapy to recover from surgery or other hip injuries. Medicare Part B may cover your physical therapy by as much as 80%, as long as it is deemed medically necessary.
Why You Might Need a Hip Replacement
Several conditions can cause the hip to deteriorate to the point of needing surgery including:
Hip replacement surgery can restore the hip joint and full range of motion. The type of replacement you receive depends on the doctor’s recommendation and your general health.
The surgery may use a cemented or uncemented prosthesis to connect the replacement parts to the healthy bone after the unhealthy cartilage is removed. The entire recovery process can take three to six months.
Understanding the Hip Replacement Procedure (Orthopedic Hip Arthroplasty)
Hip arthroplasty, also known as total hip replacement, is a common orthopedic procedure. During the surgery, your damaged bones and some soft tissue are removed.
The hip joint is replaced with an implant, which can be ceramic, plastic, or metal.
In a traditional replacement, a 10-12 inch incision is made on the side of the hip. In less-invasive procedures, the incision may only be three to six inches.
Some people may not be eligible for a minimally invasive procedure. Be sure to ask your doctor if you aren’t sure what your procedure will be like.
Man Discussing the Cost of Hip Replacement Surgery With Medicare With His Doctor | Medicare Plan Finder
Medicare Hip Replacement Scenario
To better understand how everything works together, let’s take the real-world example of a 75-year-old man who has osteoarthritis.
He’s been working with his doctor to manage his symptoms, and things have been going well. One day, the man takes a nasty fall and breaks his hip. This man’s Medicare hip replacement process involves several steps:
He doesn’t go to the hospital right away because the bruising around his hip looks like one of his routine injuries. The man makes another doctor’s appointment, and his doctor takes X-rays and determines the man will need a hip replacement.
His doctor will determine if the man is healthy enough for surgery, and then the doctor refers the man to an orthopedic surgeon. Until this point, everything falls under Medicare Part B.
The man decides to have his surgery in an outpatient facility. He’s responsible for his deductible if he hasn’t met it, or the out-of-pocket maximum for his plan.
The surgery is successful, so he has physical therapy appointments so he can recover as quickly as possible. The man has a Medicare Advantage Prescription Drug plan, so he collects his blood thinners and painkillers for only a small copayment at the pharmacy.
Along with prescription drugs, the man’s surgeon prescribes a cane and grab bars to help the man perform daily tasks. The man’s MA plan also covers those items, because his doctor determined they are medically necessary.
Contact Us Today
A comprehensive Medicare plan can help cover the cost of hip replacement surgery. If you need help finding coverage, we can help! Call us at (833)-567-3163 or contact us here today.
Contact Us | Medicare Plan Finder
This post was originally published on May 15, 2019, and updated on March 24, 2020.
Assistive Devices for the Elderly: Feel Comfortable With Independent Living
As you age, simple tasks like buttoning your shirt, getting out of your chair, and putting on your shoes can become increasingly difficult. Assistive devices can help restore your confidence, improve mobility, and increase safety in your home.
The first step in making your day-to-day life easier is understanding assistive technology, durable medical equipment, and the role of Medicare.
What Is Assistive Technology?
Assistive technology (AT) covers a wide platform of devices for older adults who may need just a little bit of help. Assistive, adaptive, and rehabilitative devices all fall under the assistive technology umbrella.
Assistive devices help seniors maintain their functional independence. This, in turn, promotes their well-being. Communication aids, pill organizers, spectacles, memory aids, prostheses, or wheelchairs assist family members with cognitive decline or physical challenges with their daily activities.
Caregivers can improve an elderly person’s range of activities of daily living by carefully selecting the most appropriate assistive devices for safe, independent living.
For instance, encouraging the use of personal care products for good hygiene, grooming, and dressing can help older people maintain their dignity, raise their self-esteem, and improve their mobility by allowing them to take care of themselves.
Assistive technology can be used in various settings, such as living at home, in a nursing home, or in an assisted living facility.
Common Assistive Devices
High-tech mobility devices, such as walking canes, stairlifts, power wheelchairs, and scooters, can help seniors maintain their mobility. Mobility aids may also include low-tech assistive devices like transfer benches and bed rails because they reduce the risk of falls.
Meanwhile, adaptive devices are designed to make an available technology more accessible. For example, adaptive switches will allow an elderly person to activate switch-adapted electronics.
There are also assistive listening devices, called Frequency Modulation systems, that connect hearing aids to media such as tablets, smartphones, computers, and music players. Additionally, screen magnifiers are software products that interface with the graphical output of a computer to enlarge content on a screen.
We’ll split assistive technologies into health, home, and comfort categories. You can purchase these products online and in-store from companies like Amazon, Walmart, and Target. Some health devices can be priced as low as five dollars.
Health Devices
Health devices act as an extra layer of protection and are a great way to prevent falls and accidents. For example, grab bars in the bathroom can help you get in and out of the shower and keep you stabilized and balanced. Consider purchasing:
Activator poles to keep you stabilized and balanced.
Grab bars to keep your balance in hallways, stairwells, bathrooms, etc.
A bed cane to help you get in and out of bed.
A shower bench so you can sit and avoid falling in the shower.
Toilet rails to help you sit down and keep your balance.
Stairlifts so you can go up or down stairs with ease.
Wheelchair ramps so you can easily get into and out of your home.
Slip-free stair strips to keep you from slipping on slick surfaces.
Home Devices
Home devices are a fantastic way to increase independence and confidence in your home and make it easier for you to be home alone. For example, if you need a walker or cane to get around comfortably, an automatic swing door opener allows you to open the door hands-free. Common home devices include:
Video doorbells so you can see who’s at the door before you get up.
Fall detectors to alert your friends and family if you take a tumble.
A power failure alarm to alert you of lost power and provide emergency lighting.
An automatic swing door opener so you can open doors hands-free.
A talking thermostat so you can hear the temperature settings.
Voice-activated lights to turn your lights on and off without getting up.
Comfort Devices
Sometimes the smallest tasks can cause the largest frustrations. For example, you may be easily annoyed if you can’t button your shirt yourself or hear the television well. Common comfort devices include:
A buttoning hook to help you button shirts and pants.
A zipper pull so you don’t have to fumble with small zippers.
A modified keyboard so you can see the letters on the keys more clearly.
Robotic vacuums so you can have clean floors without lifting a finger.
A table tray so you can eat anywhere in your home.
A mattress lift so you can get in and out of your bed with ease.
A sound amplifier to help you hear conversations, television shows, etc.
Assistive Technology Devices
Georgia Tech describes high-tech assistive technology gadgets for seniors who want to remain independent as complex devices with digital or electronic parts that can be computerized.
They point out that these devices are often expensive, usually require training, and take some effort to learn. Some examples of helpful things for elderly people that have a small learning curve are power wheelchairs, digital hearing aids, and voice-activated telephones.
Durable Medical Equipment
Durable Medical Equipment (DME) includes equipment like hospital beds, oxygen equipment, sleep apnea devices, glucose monitors, and some of the assistive devices mentioned above. DME devices are covered under Medicare Part B. You will be responsible for 20%.
The equipment must be durable, used for a medical reason in your home, and have an expected lifetime of at least three years for Part B to cover it.
Medicare Advantage (MA) plans can also cover DME and assistive devices. The difference is that MA plans are able to offer additional benefits that Original Medicare does not. This includes benefits like hearing, dental, and vision coverage.
Some MA plans even offer group fitness classes like Silver Sneakers or an over-the-counter monthly allowance. If you’re looking for additional coverage and benefits beyond Original Medicare, a Medicare Advantage plan may be perfect for you!
How to Choose an Assistive Device
With so many products for elderly people living alone, it can often be difficult for a caregiver or senior to make a decision on what to buy. For instance, a senior who asks, “How do I choose a walking aid?” has to select between wheeled frames, walking frames without wheels, folding frames, indoor trolleys, and outdoor trolleys.
Consequently, the right decision requires a clear assessment of needs and then matching those needs with available features.
If deciding on a walking aid is complex, imagine how much more bewildering it must be for caregivers to select the best smart device for elderly patients? For instance, when it comes to smartphones, GreatCall offers a variety of options, such as the Jitterbug Smart 2 and the Jitterbug Flip.
Again, it’s about matching needs with features. Some expert advice from someone familiar with technology is helpful.
What to Consider Before Purchasing
A family caregiver helping a loved one decide what assistive device to purchase must consider factors like independence, specific needs, personal goals, simplicity, and so on. Before making a purchase, it’s useful to talk to a professional or people who have purchased the device, consider the cost, and ask if a trial is available.
Implementing assistive technology in the home may require some structural modifications to a room. When considering interior home modifications, such as relocating switches, installing emergency alarms, or lowering bench heights, it’s usually practical and cost-effective to only modify necessary areas in an apartment or house.
Assistive technology devices for elderly people can be classified into two broad groups, high-tech AT, such as smartphone systems and sensors, and low-tech AT, such as pill organizers and canes. Usually, people who need assistive devices require both kinds.
In addition to mobility AT, personal care AT, and communication AT, there are a number of assistive technology devices for seniors with cognitive decline. For instance, seniors with Alzheimer’s or Parkinson’s disease with significant memory loss can benefit from wearable timers that have set and forget features for managing things like turning off the stove after cooking or running water in a bath.
They will also benefit from smartphone apps that remind them of to-do lists or appointments.
Where to Buy Assistive Devices
A caregiver or senior can buy assistive technology from online tech stores. In 5 Assistive Technology Stores for your Techie with Special Needs, author Lauren Lewis recommends five top online stores that sell assistive devices: EnablingDevices.com, Boundless Assistive Technology, Enable Mart, Infogrip, and Able Net. Her article covers each store’s specialty.
Assistive Technology and Devices Coverage
Assistive technology and devices can improve your life in several areas. If you are interested in learning more about things to help at home, such as increasing your independence, improving your quality of life, supporting your health, and restoring your confidence, let us help you!
We have licensed agents across 50 states that are contracted with all of the major insurance companies and can help you find a plan that makes it easier for you to afford assistive devices for elderly parents or patients. To get started, call (833)-567-3163 or click here.
Alzheimer’s Care Guide: Symptoms, Stages, Prevention, and Treatment
There are more than 5.7 million Americans living with Alzheimer’s. This number is expected to reach 14 million by 2050.
The complications from this disease make Alzheimer’s the sixth leading cause of death in the United States, so it’s important to educate yourself on the symptoms, signs, stages, prevention, and treatment.
Difference Between Alzheimer’s and Dementia
Dementia is a syndrome and used to describe symptoms that include memory loss, difficulty problem solving, and struggling with thoughts and language. Alzheimer’s is a disease and is a type of dementia.
In fact, there are over 100 types of dementia. Some forms of dementia can be temporary, reversed, or cured, however, Alzheimer’s disease cannot.
Alzheimer’s Symptoms and Stages
Alzheimer’s can cause changes in the brain long before any symptoms or signs start to show. Understanding the symptoms can help you detect Alzheimer’s early on and increase your chance of benefiting from treatment.
The risk of developing Alzheimer’s will vary per individual, but the following are the largest risk factors.
Age: Alzheimer’s is not a normal part of aging, however, your risk increases with age. Most people with Alzheimer’s are diagnosed after the age of 65. After 65, your risk doubles every five years.
Family History: If your parent or sibling was diagnosed with Alzheimer’s, you are more likely to develop the disease. This risk increases with the number of diagnosed family members.
Other Risks: There is a strong connection between our hearts and our brain. If you have heart disease, are overweight, or lack regular exercise, you’re at a higher risk of developing Alzheimer’s.
What Are the Very First Signs of Alzheimer’s?
Alzheimer’s is a slow progressing brain disease. If you notice any of the following warning signs, contact your doctor:
Forgetting recently learned information (dates, appointments, events, etc.)
Trouble following a recipe
Difficulty driving to a familiar location
Losing track of dates, seasons, and times
Difficulty reading
Trouble judging distances
Struggling with vocabulary
Misplacing things around the home
Paying less attention to hygiene needs
Avoiding social activities
Changing personality
What Are the 7 Stages of Alzheimer’s?
There are three general stages of Alzheimer’s – mild (early stage), moderate (middle stage), and severe (late stage). However, these stages can be broken down into seven more specific stages.
Keep in mind that the seven stages can overlap, and placing someone into a specific stage can be difficult.
Stage 1 – No Impairment: Alzheimer’s is not detectable in this stage. There are no signs of memory problems or other symptoms.
Stage 2 – Very Mild Decline: Minor memory problems may begin to surface. You would still perform well on memory tests, and Alzheimer’s will be difficult to detect.
Stage 3 – Mild Decline: At this stage, you or family members may start to notice small symptoms. Memory tests may be affected and doctors can detect impaired function. Someone in this stage may be unable to find the right words in conversation or remember new names.
Stage 4 – Moderate Decline: This stage is much more clear-cut. Someone in this stage may have difficulty with basic math problems, have short-term memory loss, be unable to manage bills, and may forget details of the past.
Stage 5 – Moderately Severe Decline: Those in this stage may begin to require assistance in day-to-day life. They may be unable to get dressed appropriately, be unable to recall details like their phone number, and demonstrate significant confusion.
Stage 6 – Severe Decline: People in this stage need constant supervision and may require professional care. They may be unaware of their environment, unable to recognize faces, and unable to remember most of their personal history. Loss of bladder control, personality changes, and wandering are also common in this stage.
Stage 7 – Very Severe Decline: This is the final stage of Alzheimer’s. People at this stage are unable to communicate and respond to their environment. Their speech may be limited to less than six words and they are unable to sit up independently.
How Quickly Does Alzheimer’s Progress?
The rate that Alzheimer’s symptoms progress can vary, but the average person lives four to eight years after diagnosis. However, early detection and a healthy lifestyle can help someone with Alzheimer’s live 20+ years after diagnosis.
Alzheimer’s Test
There is no single test that can diagnose someone with Alzheimer’s. Doctors use a combination of medical history, physical exams, neurological exams, mental status tests, and brain imaging when diagnosing.
Neurological exams address reflexes, coordination, eye movement, speech, and sensation. Mental status tests give an overall sense if a person is able to understand dates, times, locations, and simple instructions or calculations.
The Main Cause of Alzheimer’s
Although scientists don’t fully understand all the causes of Alzheimer’s, research suggests that this progressive disease is related to aging, genetics, and underlying health conditions.
Environmental and lifestyle factors may also contribute. Often the disease could be a combination of these factors.
Alzheimer’s Prevention
Complex factors like age, genetics, environment, lifestyle, and existing medical conditions play a role in developing Alzheimer’s. However, while you can’t change your genes or your age, there are plenty of steps you can take to help prevent Alzheimer’s.
Can Alzheimer’s Be Prevented?
There is strong evidence that shows changing your lifestyle promotes a healthy heart and lowers your risk of Alzheimer’s.
Prevention tips include:
Healthy Heart: There are several connections between our heart and brain. Studies have shown that about 80% of people with Alzheimer’s also have some form of heart disease. Manage your blood pressure, diabetes, and cholesterol levels to lower the risk of developing any heart conditions.
Exercise and Diet: Regular exercise and a healthy diet directly benefit your brain cells. Exercise increases blood flow and oxygen to the brain and a healthy diet limits your intake of sugars and saturated fats.
Social Activities: Staying social helps build and maintain strong connections. This can keep you mentally active. Researchers believe these connections can lower your risk of Alzheimer’s by increasing mental stimulation and reinforcing connections between nerve cells and your brain.
Alzheimer’s Disease Treatment
There is no cure for Alzheimer’s and no way to stop its progression. However, there are drug and non-drug options to help treat the symptoms. These include:
Medications for Memory: Cholinesterase inhibitors and memantine are common drugs used to treat memory loss and confusion. A doctor can prescribe these medications, so be sure to contact your health care provider.
Behavior Treatments: Some doctors may prescribe antidepressants, anxiolytics, or antipsychotic medications for people who demonstrate drastic behavior.
Alternative Treatments: Researchers believe that herbal remedies, dietary supplements, and certain foods can enhance memory and prevent Alzheimer’s. Some examples include coconut oil, coral calcium, and omega-3 fatty acids. To see an extended list, click here.
Alzheimer’s Care
Are you a caregiver? There are several options available to help a loved one diagnosed with Alzheimer’s. These options include:
Minor Assistance: You can help your loved one with simple tasks like removing objects that could cause injury, maintaining smoke alarms and fire extinguishers, and keeping dark areas, like stairwells, well lit.
Home Care: Home health services and adult day centers are two options that can help with more intensive health and well-being tasks, while the patient is still living in the home.
Residential Care: Residential care is common in the later stages of Alzheimer’s. Residential care can include assisted living, nursing homes, and Alzheimer’s special care units. These options can help with tasks like meal preparation, dressing, bathing, and other everyday tasks.
Alzheimer’s, like other forms of dementia, will often require long-term care. The type of care someone will need will change as the disease progresses; so, at some point, outside care will probably be necessary.
Outside care options include nursing home care, assisted living, adult care services, and respite care. Caring for Alzheimer’s patients in a nursing home is necessary when caring for your loved one at home has become overwhelming.
Alzheimer’s and Dementia Care: Tips for Daily Tasks
The Mayo Clinic organizes tips for caring for some with Alzheimer’s into two groups: things to do to reduce frustration and guidelines to follow to ensure a safe environment.
A care plan to reduce frustration could include the following:
Creating a daily routine for the patient.
Allowing the patient to take their time.
Doing tasks that involve the patient.
Offering the patient choices, such as offering finger foods if it’s time to eat but they are not hungry.
Providing instructions that are easy to understand and simple to follow. Establish eye contact to make sure the patient understands what has been said.
Reducing napping time so that the patient remains aware of whether it is day or night.
Reducing distractions when they are eating, such as turning off the television during mealtime to make it easier to focus on eating.
Some safety tips on dealing with Alzheimer’s patients could include the following:
Preventing falls by avoiding things that could trip a patient up, like extension cords, and installing handrails in places like bathrooms.
Putting locks on all cabinets that could contain dangerous equipment or materials, such as guns, power tools, utensils, cleaning detergents, and so on.
Checking water temperature before showers or baths to avoid scalding.
Avoid accidental fires by supervising smoking.
Making sure all carbon monoxide detectors and smoke alarms have charged batteries.
When applying these dementia caregiver tips, the caregiver needs to be patient and flexible and be open to changing routines as the symptoms of the disease progress.
Caring for the Caregiver
Family caregivers, such as a son or daughter caring for an Alzheimer’s parent, must prepare for a series of distressing experiences as they watch their mother or father forget favorite family memories and lose practical self-care skills.
It’s often challenging dealing with an Alzheimer’s parent because of the overwhelming emotions, the fatigue, the isolation, and the financial complications. Still, it’s rewarding to bond with a parent by providing them with care and service and solving their problems.
There are also new relationships with others they meet in a similar situation through support groups.
Getting Help With Caregiving
Initially, family caregivers can reduce stress by sharing their caregiving challenges with their support groups.
However, caregiver stress will increase as the disease progresses. While medications used for Alzheimer’s will control some symptoms, they can only provide a limited amount of memory care support before a patient experiences significant memory loss.
Eventually, it will become necessary to consider outside care options, such as respite care, senior care, or moving the patient to a skilled nursing senior center.
For information or support on what to do when caregiving for an Alzheimer patient becomes difficult, visit the Alzheimer’s Association at www.alz.org.
Coping With the Last Stages of Alzheimer’s
Alzheimer’s disease and related dementias affecting older adults get severe during the last stages of the disease. Patients will need considerable support because they will lose touch with what is going on around them.
It can be difficult to figure out how to talk to someone with Alzheimer’s when they don’t respond to what is happening in their environment, can’t communicate any discomfort or pain, and have difficulty controlling their movements.
Legal and Financial Planning
Legal and financial planning for someone with Alzheimer’s requires a specialized lawyer because any general powers of attorney will not work for asset protection planning. A skilled and experienced lawyer is also necessary if the patient needs a health care power of attorney document.
Role of Medicare and Alzheimer’s
Original Medicare (Parts A and B) cover inpatient hospital care and some doctor’s fees associated with Alzheimer’s. Plus, Medicare will pay up to 100 days of skilled nursing home care in certain circumstances.
Long-term custodial care, like a nursing home, is not covered. Medicare will pay for hospice care in-home or at a hospice facility.
Medicare Advantage plans are great options for coverage beyond Original Medicare.
Some people with Alzheimer’s may be eligible for a Medicare Special Needs Plan. SNPs are a different type of Medicare Advantage plan and generally provide coverage for doctor visits, hospital services, and prescription drugs. Some of these plans can coordinate care services to help you better understand your condition and your doctor’s plan.
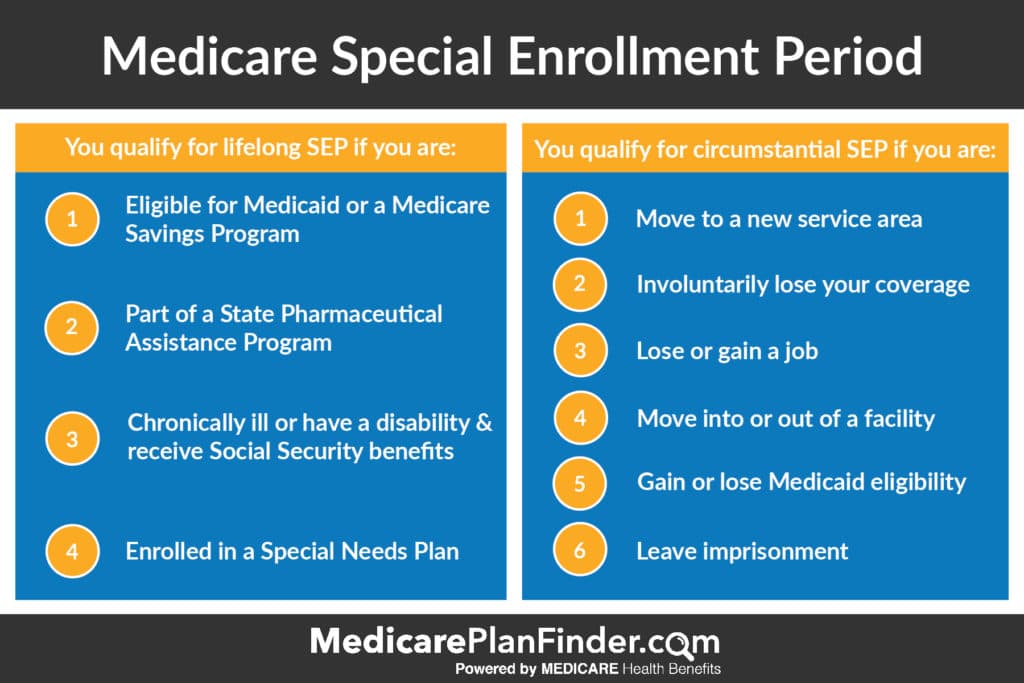
If you qualify for a Medicare Special Needs Plan, you may also qualify for a Special Enrollment Period. This means you can enroll or change Medicare plans throughout the year!
If you have any questions about Medicare Special Needs Plans or Special Enrollment Periods do not hesitate to contact us. Our licensed agents are contracted with all the major carriers across 50 states and can help you enroll in a plan that fits your needs and budget.
To schedule a no-cost, no-obligation appointment, click here or call us at (833)-567-3163.
Does Medicare Cover Alcohol Rehab and Substance Abuse?
Substance abuse costs the US more than $740 billion every year. Those costs are related to crime, healthcare, and lost productivity at work.
Overcoming addiction is a lot of work, and it takes a team of mental health and medical professionals to keep you on the right path. You might know that Medicare will pay for doctor visits for illness and injuries, but what you want to know is, “Does Medicare cover alcohol rehab?”
Medicare does cover many of the costs related to alcohol rehab and treatment if your provider says those services are medically necessary. You must get treatment at a Medicare-approved facility or from a Medicare-approved provider, and that provider must create a care plan.
Addiction Treatment for Seniors and Medicare Eligibles
Outpatient Addiction Counseling | Medicare Plan Finder
Treatment for addiction is a lot like treatment for any other disease. It starts small, often with preventive measures, and will progress according to the doctor’s recommendations.
Medicare pays for alcohol and substance abuse treatment for both inpatients and outpatients. Substance use disorders are drug addictions that influence a person’s thoughts, feelings, and behaviors.
These disorders aren’t just limited to illicit drugs, such as Cocaine, Ecstasy, GHB, Hallucinogens, and Heroin, among others. They can also include misuse of legal drugs like nicotine, marijuana, or alcohol as well as legal medications like fentanyl (Duragesic), hydrocodone (Vicodin), or oxycodone (OxyContin).
Level 0.5, Early Intervention Education and prevention for people who are at risk of developing an addiction fall under this level. Medicare can cover a conversation with your doctor about a prescription drug that may be habit-forming.
Level 1, Outpatient Treatment This level of addiction treatment refers to nine hours or less of weekly counseling services or recovery. Outpatient mental health services fall under Medicare Part B and certain Medicare Advantage (MA or Part C) plans.
Level 2, Intensive Outpatient and Partial Hospitalization
These treatment programs are categorized as having more than nine hours of counseling services a week, and/or short inpatient hospital care. Medicare Part A pays for hospital stays of up to 60 days. After 60 days, you will owe coinsurance.
According to the American Addiction Centers, “Part B covers partial hospitalization (PHP), which is an outpatient treatment” that a hospital or mental health center provides. A PHP provides more intensive treatment than standard outpatient programs.
A doctor must say that PHP is medically necessary, and your treatment plan must include at least 20 hours of treatment per week.
PHP services can include:
Individual and group therapy
Occupational therapy
Family therapy
Patient education
Activity therapies that are not chiefly recreational
Therapeutic drugs that can’t be self-administered
Medically necessary diagnostic services for mental health
Level 3, Inpatient Treatment
The next level involves up to 90 days in a rehab facility with a focus on behavioral therapy and staying away from substances. Medicare Part A covers the first 60 days of psychiatric hospital stays.
Days 61-90 will cost most people $335/day.
According to the American Addiction Centers, you can receive up to 190 days of treatment at a specialty psychiatric hospital, but no more. That is a lifetime limit. You may be able to receive treatment under Medicare Part A at:
Acute care hospitals
Critical access hospitals
Inpatient rehab centers
Long-term care hospitals
Inpatient care as part of a qualifying research study
People whose long-term addictions have caused them physical harm need this level of care. It not only involves drug and alcohol counseling but also access to nursing care, prescription drugs, and other medical services
In the event that you or someone you love suffers an overdose, Medicare covers some treatments. For example, most Medicare Part D plans cover Narcan, the drug used to reverse the effects of an opioid overdose.
Typical co-pays for most people with Part D and certain Part C plans for Narcan range from $19-$144.
Medicare Part A is hospital insurance, and it will cover your hospital stay, but not all services fall under Part A. Ambulance transportation is under Part B, and so is doctor observation until you are “officially admitted” into the hospital.
The Centers for Medicare & Medicaid Services (CMS) cover mental health treatment. Medicaid is a federal and state program to help you with your medical costs if you have limited income.
Mental health treatment services are based on screening, brief intervention, and referral to treatment (SBIRT). This is an evidence-based approach used in public health for early interventions and treatment services.
It’s designed to help someone at risk for a substance abuse disorder or who already has a substance abuse disorder.
For instance, after this comprehensive evaluation protocol, someone addicted to heroin might be administered methadone to reduce the intensity of withdrawal symptoms. If this patient does not benefit from outpatient treatment, then inpatient psychiatric care is another option. Such residential treatments provide a space for treatment, sleeping, bathing, recreation, and dining.
Addiction is a disease, and with the right treatment plan, it can be managed. A qualified professional can guide you through the thousands of Medicare plans out there and help you find one that will suit your needs.
Does Medicare Cover Opioid Treatment?
In 2027, the Medicare program includes paying for Opioid Treatment Programs (OTP). The Medicare-enrolled opioid treatment program is comprehensive, consisting of periodic assessments, intake procedures, toxicology testing, individual therapy, group therapy, and counseling for substance use.
It also includes FDA approved opioid treatments and medication-assisted treatment (MAT) medications as well as the dispensation and management of MAT medications. A search for “opioid treatment programs near me” will show you a map of addiction treatment centers in your neighborhood.
SAMHSA Helpline to Find Treatment
The Substance Abuse and Mental Health Services Administration (SAMHSA) National Helpline is a free, confidential service you can use 24 hours a day, seven days a week to find treatment for substance abuse disorders. You reach the helpline at 1-800-662-HELP (4357) or use SAMHSA’s online treatment finder tools.
What Is the SAMHSA Helpline?
The SAMHSA National Helpline offers assistance in finding local treatment facilities, support groups, and community-based organizations. You can also request free publications and other information.
Will My Medicare Plan Cover This Service?
The referral service is free. When you call, ask the representative to refer you to a facility that accepts Medicare. If you have a Medicare Advantage plan, ask your health insurance carrier for a list of participating healthcare providers.
How to Find Approved Medicare Alcohol Treatment and Drug Rehab Providers
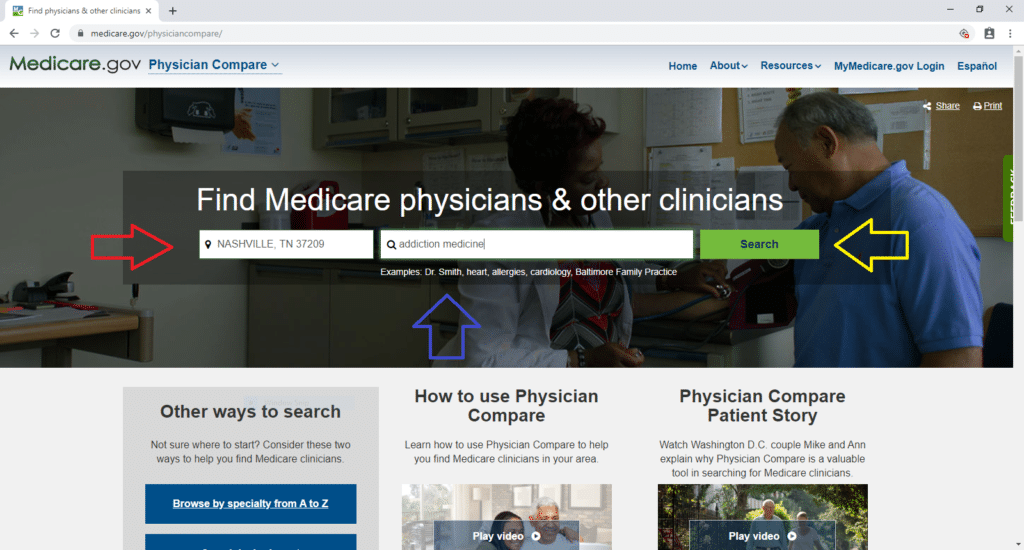
Medicare’s Physician Compare website is a great resource for finding addiction treatment in your area. Click here to get started.
You’ll reach a page that allows you to enter your zip code and what type of medical practice you want to find. We chose 37209, which is the zip code for our corporate offices in Nashville, TN.
For the practice type, we chose “addiction medicine.” Once you’ve entered that information, click “search.”
How to Find Approved Medicare Alcohol Treatment and Drug Rehab Step 1 | Medicare Plan Finder
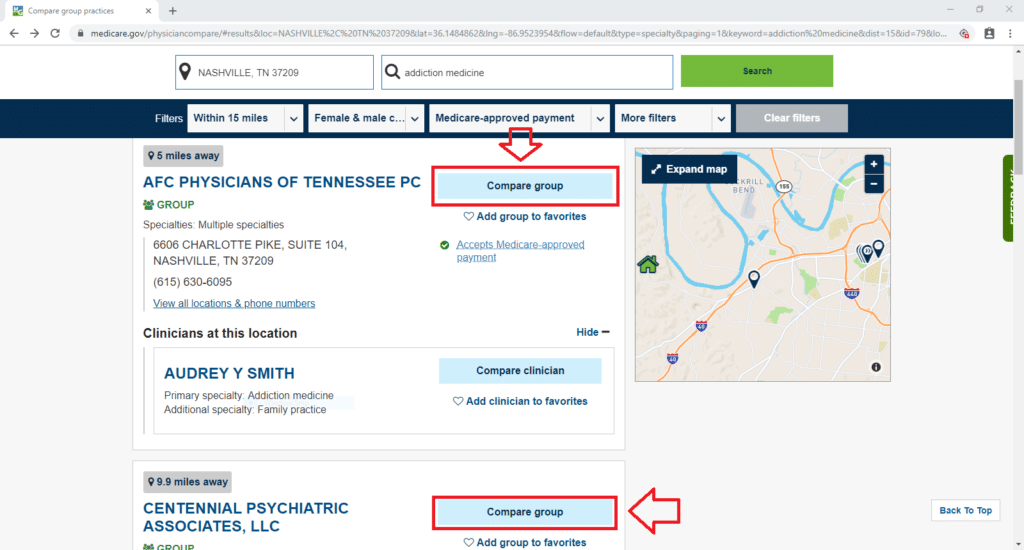
That will lead you to a list of local practices that specialize in addiction treatment. You can use the contact information to call the facilities and compare their services, or you can use Medicare.gov’s tool.
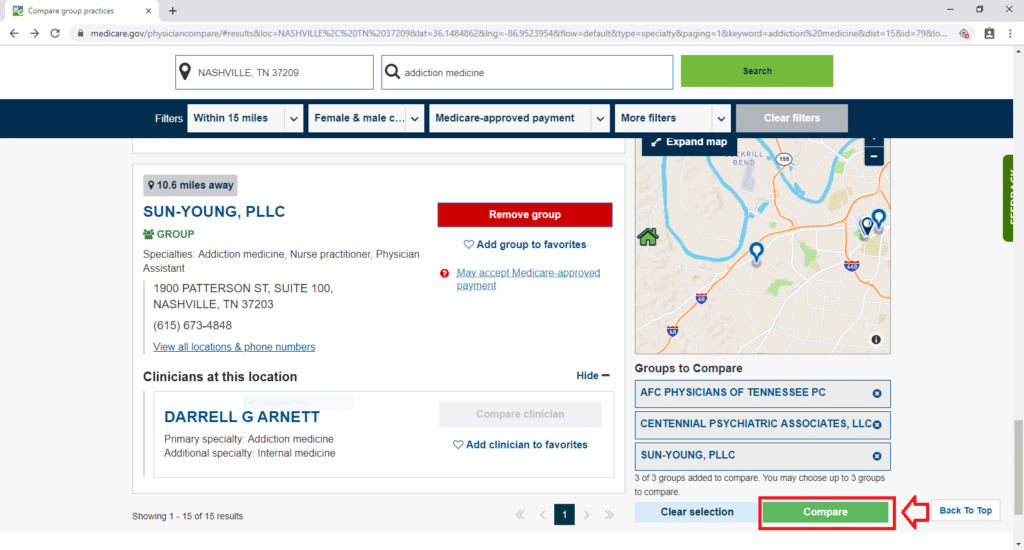
To use the tool, click on the practices you want to compare. For our purposes, we only chose the top three practices on the list.
How to Find Approved Medicare Alcohol Treatment and Drug Rehab Step 2 | Medicare Plan Finder
Then click “Compare” at the bottom of the page.
How to Find Approved Medicare Alcohol Treatment and Drug Rehab Step 3 | Medicare Plan Finder
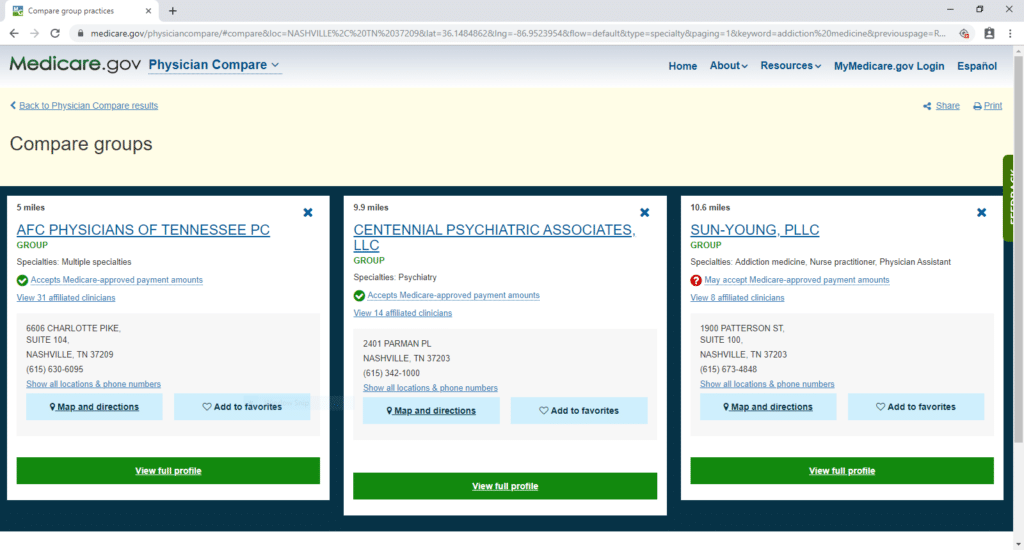
Then you will come to a page that allows you to view practice contact information on one screen. You can also look at the practices’ full profiles and get directions to each location.
How to Find Approved Medicare Alcohol Treatment and Drug Rehab Step 4 | Medicare Plan Finder
Prevalence of Substance Abuse in Older Adults
Older adults (defined as 65 and older in the United States) most commonly abuse alcohol, but many also abuse prescription and illegal drugs. The percentage of older adults who met the criteria for having an addiction problem was 11.7 percent.
Drug abuse in adults older than 65 years is mainly limited to alcohol despite the prevalence of so many illicit drugs and mood-altering prescription drugs.
Substance Abuse in the Elderly: Unique Issues and Concerns
The elderly population accounts for 25% of the prescription drugs sold in the US, and this population faces unique issues when it comes to substance abuse. Because addiction symptoms look like other common senior health disorders such as dementia, diabetes, and depression, addiction often goes ignored.
According to the National Institute on Alcohol Abuse and Alcoholism (NIAAA), drug addiction in adults over 60 years primarily arises from alcohol and prescription drugs. This creates a risk of harmful interactions between the two.
Medicare Help for You or Someone You Love
If you or someone you love struggles with drug or alcohol addiction, you don’t have to face it alone. A licensed agent with Medicare Plan Finder may be able to help you find a Medicare plan with the right care team to lead your or your loved one’s recovery.
To set up a no-cost, no-obligation appointment with an agent call (833)-567-3163 or contact us here today.
Contact Us | Medicare Plan Finder
This post was originally published on April 22, 2019, and updated on January 15, 2025.
Does Medicare Cover Dental Implants?
Sometimes plaque and tartar can build up to the point where the accumulation irritates the gums and cause damage to your teeth. The irritation and damage can even result in tooth loss. A dentist might recommend a dental implant to solve the problem.
If you’re one of the many people who need dental implants and you have Medicare insurance, you probably have a lot of questions such as, “What are dental implants,” and, “Does Medicare cover dental implants?”
What Are Dental Implants?
A dental implant is an artificial tooth with a titanium post that’s surgically attached to your jaw. About 450,000 people have dental implants every year.
Does Medicare Cover Dental Implants? | Medicare Plan Finder
Original Medicare and Medicare Advantage Dental Coverage
Does original Medicare cover dental implants?
No. Original Medicare (Part A and Part B) does not cover dental implants or routine dental care.
Are dental implants covered by Medicare advantage plans?
Sometimes. This means some plans do and some plans don’t.
Private insurance policies called Medicare Advantage (MA) plans can offer coverage for additional services Original Medicare does not, including dental services. Sometimes the dental services offered include implants and sometimes they only include routine cleanings and x-rays.
If you need dental insurance, an agent with Medicare Plan Finder can work with you to find a Medicare Advantage plan in your area that offers dental implants. Some plans also offer coverage for vision, hearing and even fitness classes along with all of the services that Original Medicare covers.
Some people may find that their Medicare Advantage plan does not cover all of their dental needs. Those people may need additional dental coverage from private policies called commercial dental insurance plans to cover major procedures such as dental implants.
How to check if your Medicare Advantage plan covers dental implants.
In order to determine if your current plans covers dental implants, you’ll need to check the summary of benefits you received when you first enrolled in your plan.
There should be a section in your summary of benefits that will specifically address the dental benefits included as well as specifically covered benefits such as implants, dentures, cleanings, and x-rays.
As mentioned, every plan offers different benefits, so you should always verify with your plan summary benefits to be sure. If you do not know how to find your summary of benefits, you should call your insurance company or speak to a licensed agent.
Does Medicare Supplement Cover Dental Implants?
No. Medicare supplement plans do not cover dental implants.
Medicare Supplement (Medigap) plans can help pay for financial items such as copays and coinsurance that can come with Original Medicare.
Unlike Medicare Advantage plans, Medigap policies do not offer additional benefits. That means that a Medicare Supplement plan will not pay for routine dental care or dental implants. You cannot have both a Medicare Advantage policy and a Medigap plan at the same time, so it’s a great choice to learn the difference between the two.
A licensed agent with Medicare Plan Finder can help you determine what you need, and what’s available in your area. To learn more, call (833)-567-3163.
Does Medicaid Pay for Dental Implants?
Medicaid is both federally and state-funded. The program helps people who qualify to pay for their health insurance. Every state has different rules about dental coverage. While most states provide at least emergency dental services for adults, not all states provide comprehensive dental coverage.
If you qualify for Medicaid and have questions about what services your state covers, contact your local Medicaid office.
Elderly Dental Problems and Their Solutions
Tooth loss is not an inevitable part of aging, but many seniors can develop diseases which can make dental implants or other solutions a necessity. Conditions that affect older adults include dry mouth, gum disease, and oral cancer.
Dry Mouth
Many medications that treat common senior conditions have dry mouth as a side effect. Dry mouth can lead to cavities, which ultimately lead to gum disease. If you have dry mouth as a medication side effect, talk to your doctor about what drugs you take and the dosages.
Your doctor may change your prescriptions or recommend over-the-counter oral moisturizers or drinking more water. In order to further prevent cavities, your dentist may apply fluoride treatments.
Gum Disease
Periodontal, or gum disease results from bacteria in plaque irritating the gums. The gums become swollen and are more likely to bleed. Periodontal disease is widespread among older adults because it’s often painless until it becomes severe and many people don’t have regular dental exams.
If gum disease goes untreated, the gums can recede from the teeth and form spaces that can collect food particles and more plaque. Advanced periodontal disease can destroy the gums and the bones and ligaments that support the teeth. Your dentist can treat or help you prevent gum disease, so it’s important that you have regular check-ups.
Oral Cancer
Oral cancer is an uncontrollable growth of invasive cells that causes damage to the mouth, tongue, and throat. It can be life-threatening if it’s not treated early. Along with regular dental visits, you can prevent oral cancer by avoiding tobacco or heavy alcohol use.
Other risk factors include a family history of cancer, excessive sun exposure and having HPV. About 25 percent of oral cancer cases are people who don’t smoke or who only drink occasionally. Treatment for oral cancer involves surgery to remove the cancerous cells, or radiation and chemotherapy.
Does Medicare Cover Dentures or Other Alternatives to Traditional Dental Implants?
Dental Exams | Medicare Plan Finder
Some people may not be able to receive dental implants. For example, if your jaw cannot support a dental implant, a dental specialist will have to find an alternative.
Dental Implant Alternatives
Bridges: This alternative uses artificial teeth supported by crowns that attach to the natural teeth to solve the dental issue.
Full or Partial Dentures: Full dentures are a dental implant alternative for people who have lost most of their natural teeth. They are removable artificial teeth secured to a support piece in the mouth. Partial dentures are for people who have most of their natural teeth still, and they attach to natural teeth with metal clasps.
“Teeth in a Day”: Traditional dental implants require a lengthy recovery period that can last up to two years. “Teeth in a Day” is a procedure that uses computer-guided technology to find the best placement for implants and accurately insert new posts in an hour.
If you take care of your teeth, you can avoid many of the issues that contribute to tooth decay, gum disease, tooth loss, and ultimately avoid needing assistance with dental implants. A strong oral hygiene routine includes:
Brushing twice daily with fluoride toothpaste
Flossing between your teeth every day to remove plaque
Limiting alcoholic beverages
Refraining from smoking or chewing tobacco
Regular dental visits even if you have no natural teeth or you have dentures
Visiting your doctor or dentist if you experience abrupt changes in taste or smell
Working to control diabetes, which will decrease the risk of gum disease and other conditions
Many older adults will need assistance with everyday grooming and self-care. If you’re a caregiver, you can help the people you care for avoid gum disease by flossing and brushing their teeth every day and bringing them to their dentist visits.
Let Us Help You Find Dental Plans That Cover Dental Implants
Even though Medicare does not cover dental implants, the right Medicare Advantage plan or commercial dental insurance plan can help pay for the treatments your dentist recommends. Call (833)-567-3163 or contact us here to arrange an appointment with a licensed agent.
This post was originally published on June 12, 2019, and updated on January 15, 2025.
7 Important Things You Never Knew About Medicare
What is Medicare? Most people are familiar with short answer: Medicare is a federal health insurance program that covers people over the age of 65, people with certain disabilities, or those who suffer from either ESRD (end-stage renal disease) or ALS (Lou Gehrig’s Disease).
While this is probably the easiest way to explain Medicare, most people don’t know how complicated it can be once you dive below the surface. Here we’ve broken down the 7 most important facts about Medicare that you may have never heard before!
1. There are multiple parts of Medicare
Perhaps the biggest misconception about Medicare is that it’s one gigantic program. In truth, what we refer to as Medicare actually has four distinct components, or “parts.” You might hear some different names used but usually these parts will be designated as A, B, C, or D.
The Original Medicare program consists of Part A and Part B. Part A primarily covers inpatient hospital care, while Part B handles outpatient services like doctor visits. These two components of Original Medicare represent the basic coverage that is available to you when you turn 65.
Part C, often called Medicare Advantage plans, are offered by private health insurance companies. These allow recipients of parts A and B to also receive benefits like dental, vision, and prescription drug coverage depending on the plan they choose.
Medicare Advantage | Medicare Plan Finder
Part D, sometimes called a prescription drug plan (PDP), offers prescription drug coverage to beneficiaries enrolled in Medicare. These are offered by private insurance companies as an addition to the Original Medicare benefits, as Original Medicare does not include any drug coverage.
2. You can’t enroll whenever you want
Unfortunately, Medicare is not a program you can just enroll in at any time. It’s true that you are eligible for Medicare when you turn 65, but unless you qualify for automatic enrollment, you will need to sign up during one of the five designated enrollment periods.
The Initial Enrollment Period (IEP) is usually your primary opportunity for Medicare enrollment. If you are aging into the program, this IEP begins three months before your 65th birthday and extends to three months after, giving you seven months in total to enroll.
There is actually a second IEP, sometimes called IEP2, available for those who are eligible for Medicare before they turn 65, such as those with disabilities. This period also lasts seven months and gives these beneficiaries an opportunity to make changes to their plan.
The General Enrollment Period (GEP) is offered for first-time Medicare enrollees who did not join during their IEP. This period occurs every year from January 1 to March 31. Coverage applied for during this period begins on July 1st.
The AEP, or Annual Enrollment Period, starts every 10/15 and runs until 12/7. This period provides an opportunity for those already enrolled in Medicare to make changes to their coverage, such as adding a Part D plan or converting your Original Medicare to a Medicare Advantage plan.
Special Enrollment Periods (SEPs) allow Medicare beneficiaries to make changes to their coverage outside of AEP. During these periods, people who are enrolled in a Special Needs Plan or who have recently lost a job can add to or switch their coverage. Check out the handy graphic below to see if you qualify for one of these SEPs.
Special Enrollment Period | Medicare Plan Finder
In 2019, a new enrollment period was introduced, called the Open Enrollment Period, or OEP. This period lasts from 1/1 to 3/31, and lets those who enrolled in Medicare Advantage during AEP make changes in their coverage without having to wait for the next AEP.
3. You may have to pay if you delay
If you do miss your IEP, you may have to pay penalties when you finally do enroll. The amount you will pay and the duration you will have to pay depends on which part of Medicare you enroll in and how long you waited.
The Part A penalty is incurred if you do not qualify for free, automatic enrollment and you fail to sign up for it when you are eligible. This penalty will be added to your premium to the tune of 10%, which you will have to pay for twice the number of years that you neglected to sign up.
If you enroll late in Part B, your premium will go up by about 10% for every year you were eligible but didn’t sign up. You will then have to pay this increased premium for the entire time you have Medicare Part B. You may also have to pay a penalty if you do not enroll in a Part D plan within the first three months that your Parts A & B are active. However, some of these penalties may be avoided if you qualify for a Special Enrollment Period.
4. Original Medicare only covers 80%
Once you are finally enrolled, you might wonder: “How much does Medicare cover?” The unfortunate truth is that it will not fully cover your medical expenses. Parts A & B will only cover up to 80% of the cost of Medicare-covered services, leaving you to pay the remaining 20% coinsurance.
This might not be too much trouble for routine doctor visits, but in the case of a medical emergency or hospital stay, the amount you pay out-of-pocket can skyrocket quickly. To cover that last 20%, consider purchasing a Medicare Supplement plan to add on to your Original Medicare coverage.
5. Original Medicare doesn’t cover dental, hearing, or vision
Many people might not realize that Medicare covers very little in the way of dental and hearing expenses, and virtually nothing when it comes to vision. Part A will sometimes pay for specific dental services if you have to get them while you are staying in a hospital, but will not pay for cleanings, fillings, dentures etc.
Medicare will sometimes cover diagnostic hearing exams if your physician orders it as part of their treatment, but will not cover hearing aids under any circumstances. For vision coverage, your options with Original Medicare are even more limited, as it will not pay for eye exams, glasses, or contact lenses.
There are some options that can provide vision, hearing, and dental coverage for seniors. A DVH (or Dental, Vision, Hearing) plan can be purchased to add to your Original Medicare benefits, or you might look to a Medicare Advantage policy to consolidate all of that coverage into one plan.
If you think Part C might be the best coverage option for you, click here or give us a call at (833)-567-3163 to have a licensed agent help you compare Medicare Advantage plans!
6. Original Medicare will not cover you abroad
Aside from a few very specific circumstances, Medicare Parts A and B will not cover your health care while you are traveling outside the United States. Medicare Part D plans are also invalid once you are more than 6 hours away from a U.S. port.
But there are some Medicare coverage options available for foreign travel, primarily in the form of Medicare Supplement (Medigap) plans.
7. Supplement plans have the same coverage, different cost
Medicare Supplement, or Medigap, insurance can be used to cover the out-of-pocket costs you may have to pay with Parts A and B. Insurance carriers offer many different types of Medigap plans, often sorted alphabetically, but they all must follow the same government regulations.
This means that Plan G from one carrier must provide the same benefits as Plan G from another carrier. Below is a quick breakdown of all the benefits covered by the different Medigap plan types.
Medicare Supplement Comparison Chart
Once you have found a Medigap plan type that meets your needs, you must consider the price. Insurance carriers must cover what is mandated by the government guidelines, but may charge very different rates for that coverage.
To find the best price, reach out to one of our licensed agents here or call us at (833)-567-3163 to have them run a personalized quote.
3 Easy Steps to Making New Friends After Retirement
It’s always tough adjusting to big life changes and, as we get older, those changes seem to come faster and faster. Retiring, moving to a new city, or the death of a spouse can all be overwhelming and foster social withdrawal and isolation.
In fact, a recent survey of retirees showed that 11% of those questioned said they felt lonely and isolated, and almost half of those had recently moved to a new home. The AARP estimates that 42.6 million Americans over age 45 suffer from loneliness, which has been established as a risk factor for early illness and death, especially among seniors.
Fortunately, staying social is easier than ever in our modern age. Read on and learn some awesome methods for making and maintaining new friendships!
1. Follow Your Passions To Find Friends
It’s not easy knowing how to make friends when you are older. Stanford researchers have even suggested that baby boomers are withdrawing from social relationships more than any other group.
But finding new friends doesn’t have to be a guessing game. Just ask yourself a few simple questions: what do you like to do? What are you passionate about? What would you like to learn more about? Finding people with mutual interests and passions is the best place to start forging new friendships.
Social Networking for Seniors
More than ever, technology is helping us form and sustain new friendships. A quick Google search will bring you to senior friendship sites like Silversurfers or Buzz50, which feature forums and chat rooms tailored to older adults.
You can also find countless senior social media groups on platforms like Facebook, which have an increasingly large userbase over the age of 55. Here you can get connected with people online or even find a group that meets in real life. You can look for clubs, classes, or other hobby groups in your area and you’re sure to meet other like-minded social seniors.
2. Getting Out and About
In the social media age, congregating with people who have shared interests can be done from the comfort of your own home. But if you’re feeling cooped up, there are countless ways to meet new senior friends while staying active!
Senior Meetups
A senior meetup is a great place to meet seniors in your area that share your interests or passions. You may find these meetups at churches, gyms, retirement communities, or other places senior citizens hang out. There are even dedicated websites like Meetup.com, which connect you to in-person events based on your location and preferred activity. This helps provide a built-in ice breaker, as you can discuss your common interests.
If you are into photography or arts & crafts, find a workshop at a senior community center where you can advance your skills. If you enjoy cooking but are getting bored of the same old recipes, join a cooking class like the ones offered at Sur La Table. If you’re more of an outdoorsy type, there are groups that go for nature outings. Or you may prefer to find a group that gets together simply to eat, drink, and socialize.
Volunteer Opportunities for Seniors
Another great solution for the social isolation elderly people face is volunteering. This can be a great way to form social connections and do something good for others at the same time.
Organizations like Senior Corps offer programs that allow retirees to mentor young people, be a companion to other seniors who are less mobile, or share their expertise in community projects like building housing.
The AARP also has a program called the AARP Foundation Experience Corps, where those over the age of 50 can tutor young children to help improve their reading comprehension. This mentoring has an impressive impact on the students, improving their literacy skills by up to 60%.
Senior Fitness Classes
Working up a sweat is a tried-and-true strategy for staving off some of the side effects of isolation, such as depression and anxiety. But it can also be a terrific way to meet new people!
Active older adults can join a senior fitness program to help keep an exercise routine and chat with other seniors looking to stay in shape. Many of these programs, like Silversneakers®, may be covered by your insurance. If you have Medicare and are considering purchasing a Medicare Advantage plan to cover fitness programs, click here or give us a call at (833)-567-3163 to speak with a licensed agent.
Medicare Advantage | Medicare Plan Finder
3. Get To Know Your New Friends
Once you have made some new acquaintances, it can be difficult to form a closer bond. Plus, as we get older, we usually have less interest in maintaining superficial or casual relationships. Getting organized and keeping to a routine can help tremendously in developing old and new friendships alike.
Keep A Schedule To Stay In Touch
The best way to uphold and develop a relationship is to keep in contact on a regular basis. As your social group grows, start a calendar.
A well-organized calendar can ensure you never miss a meetup or social event that you want to attend. You can also use your calendar to keep track of birthdays and anniversaries. A simple “happy birthday” can go a long way in strengthening a burgeoning friendship.
Just as modern technology can help us meet new people, it can also help us stay in touch with friends and family alike. On social media platforms like Facebook, you can stay engaged with your social groups, old and new, by liking or commenting on statuses and pictures, as well as posting a few of your own! Emails and phone calls can also keep you in the loop with new friends.
Whichever way you choose to find your new social group, remember that forming long-lasting bonds takes time. If a new acquaintance does not respond to your efforts, try not to take it personally. There are plenty more people out there looking for the same connections you are. Keep searching and don’t get discouraged!