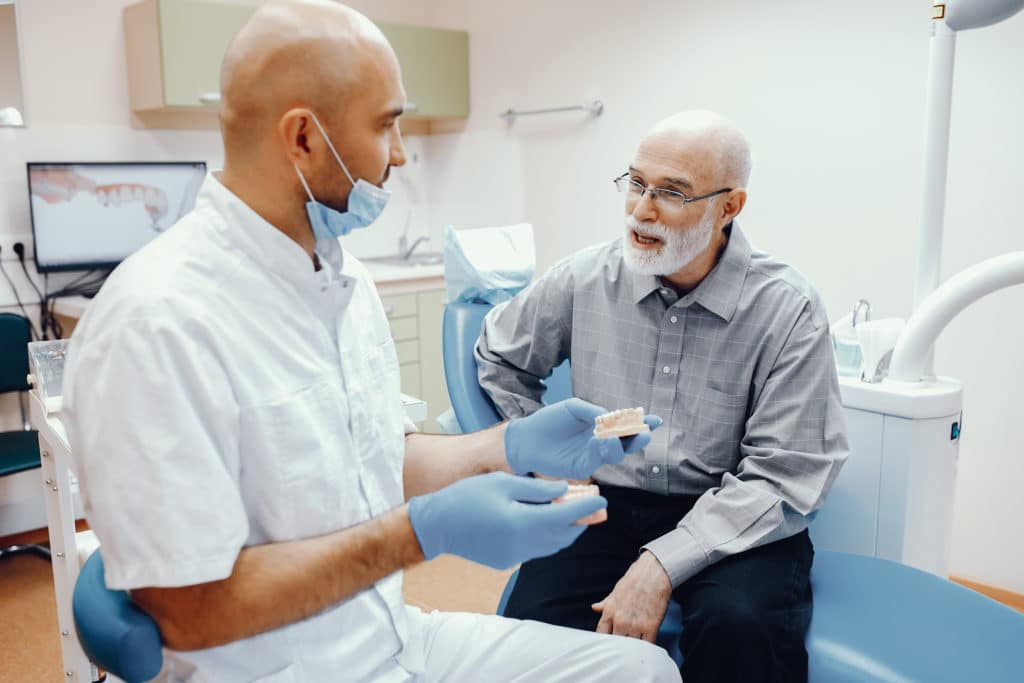
Sometimes plaque and tartar can build up to the point where the accumulation irritates the gums and cause damage to your teeth. The irritation and damage can even result in tooth loss. A dentist might recommend a dental implant to solve the problem.
If you’re one of the many people who need dental implants and you have Medicare insurance, you probably have a lot of questions such as, “What are dental implants,” and, “Does Medicare cover dental implants?”
What Are Dental Implants?
A dental implant is an artificial tooth with a titanium post that’s surgically attached to your jaw. About 450,000 people have dental implants every year.
Does Medicare Cover Dental Implants? | Medicare Plan Finder
Original Medicare and Medicare Advantage Dental Coverage
Does original Medicare cover dental implants?
No. Original Medicare (Part A and Part B) does not cover dental implants or routine dental care.
Are dental implants covered by Medicare advantage plans?
Sometimes. This means some plans do and some plans don’t.
Private insurance policies called Medicare Advantage (MA) plans can offer coverage for additional services Original Medicare does not, including dental services. Sometimes the dental services offered include implants and sometimes they only include routine cleanings and x-rays.
If you need dental insurance, an agent with Medicare Plan Finder can work with you to find a Medicare Advantage plan in your area that offers dental implants. Some plans also offer coverage for vision, hearing and even fitness classes along with all of the services that Original Medicare covers.
Some people may find that their Medicare Advantage plan does not cover all of their dental needs. Those people may need additional dental coverage from private policies called commercial dental insurance plans to cover major procedures such as dental implants.
How to check if your Medicare Advantage plan covers dental implants.
In order to determine if your current plans covers dental implants, you’ll need to check the summary of benefits you received when you first enrolled in your plan.
There should be a section in your summary of benefits that will specifically address the dental benefits included as well as specifically covered benefits such as implants, dentures, cleanings, and x-rays.
As mentioned, every plan offers different benefits, so you should always verify with your plan summary benefits to be sure. If you do not know how to find your summary of benefits, you should call your insurance company or speak to a licensed agent.
Does Medicare Supplement Cover Dental Implants?
No. Medicare supplement plans do not cover dental implants.
Medicare Supplement (Medigap) plans can help pay for financial items such as copays and coinsurance that can come with Original Medicare.
Unlike Medicare Advantage plans, Medigap policies do not offer additional benefits. That means that a Medicare Supplement plan will not pay for routine dental care or dental implants. You cannot have both a Medicare Advantage policy and a Medigap plan at the same time, so it’s a great choice to learn the difference between the two.
A licensed agent with Medicare Plan Finder can help you determine what you need, and what’s available in your area. To learn more, call (833)-567-3163.
Does Medicaid Pay for Dental Implants?
Medicaid is both federally and state-funded. The program helps people who qualify to pay for their health insurance. Every state has different rules about dental coverage. While most states provide at least emergency dental services for adults, not all states provide comprehensive dental coverage.
If you qualify for Medicaid and have questions about what services your state covers, contact your local Medicaid office.
Elderly Dental Problems and Their Solutions
Tooth loss is not an inevitable part of aging, but many seniors can develop diseases which can make dental implants or other solutions a necessity. Conditions that affect older adults include dry mouth, gum disease, and oral cancer.
Dry Mouth
Many medications that treat common senior conditions have dry mouth as a side effect. Dry mouth can lead to cavities, which ultimately lead to gum disease. If you have dry mouth as a medication side effect, talk to your doctor about what drugs you take and the dosages.
Your doctor may change your prescriptions or recommend over-the-counter oral moisturizers or drinking more water. In order to further prevent cavities, your dentist may apply fluoride treatments.
Gum Disease
Periodontal, or gum disease results from bacteria in plaque irritating the gums. The gums become swollen and are more likely to bleed. Periodontal disease is widespread among older adults because it’s often painless until it becomes severe and many people don’t have regular dental exams.
If gum disease goes untreated, the gums can recede from the teeth and form spaces that can collect food particles and more plaque. Advanced periodontal disease can destroy the gums and the bones and ligaments that support the teeth. Your dentist can treat or help you prevent gum disease, so it’s important that you have regular check-ups.
Oral Cancer
Oral cancer is an uncontrollable growth of invasive cells that causes damage to the mouth, tongue, and throat. It can be life-threatening if it’s not treated early. Along with regular dental visits, you can prevent oral cancer by avoiding tobacco or heavy alcohol use.
Other risk factors include a family history of cancer, excessive sun exposure and having HPV. About 25 percent of oral cancer cases are people who don’t smoke or who only drink occasionally. Treatment for oral cancer involves surgery to remove the cancerous cells, or radiation and chemotherapy.
Does Medicare Cover Dentures or Other Alternatives to Traditional Dental Implants?
Dental Exams | Medicare Plan Finder
Some people may not be able to receive dental implants. For example, if your jaw cannot support a dental implant, a dental specialist will have to find an alternative.
Dental Implant Alternatives
Bridges: This alternative uses artificial teeth supported by crowns that attach to the natural teeth to solve the dental issue.
Full or Partial Dentures: Full dentures are a dental implant alternative for people who have lost most of their natural teeth. They are removable artificial teeth secured to a support piece in the mouth. Partial dentures are for people who have most of their natural teeth still, and they attach to natural teeth with metal clasps.
“Teeth in a Day”: Traditional dental implants require a lengthy recovery period that can last up to two years. “Teeth in a Day” is a procedure that uses computer-guided technology to find the best placement for implants and accurately insert new posts in an hour.
If you take care of your teeth, you can avoid many of the issues that contribute to tooth decay, gum disease, tooth loss, and ultimately avoid needing assistance with dental implants. A strong oral hygiene routine includes:
Brushing twice daily with fluoride toothpaste
Flossing between your teeth every day to remove plaque
Limiting alcoholic beverages
Refraining from smoking or chewing tobacco
Regular dental visits even if you have no natural teeth or you have dentures
Visiting your doctor or dentist if you experience abrupt changes in taste or smell
Working to control diabetes, which will decrease the risk of gum disease and other conditions
Many older adults will need assistance with everyday grooming and self-care. If you’re a caregiver, you can help the people you care for avoid gum disease by flossing and brushing their teeth every day and bringing them to their dentist visits.
Let Us Help You Find Dental Plans That Cover Dental Implants
Even though Medicare does not cover dental implants, the right Medicare Advantage plan or commercial dental insurance plan can help pay for the treatments your dentist recommends. Call (833)-567-3163 or contact us here to arrange an appointment with a licensed agent.
This post was originally published on June 12, 2019, and updated on January 15, 2025.
Does Medicare Cover Physical Therapy?
Does Medicare cover physical therapy? It depends. Medicare can help pay for physical therapy, which may be a crucial part of injury or surgery recovery. However, Medicare’s coverage has limits.
Every Medicare beneficiary begins with Original Medicare, which includes Part A, hospital coverage, and Part B, medical coverage. Most physical therapy services will fall under Medicare Part B – however, there are specific Medicare guidelines for physical therapy in-home health services and doctor services.
It can be confusing to navigate the different coverage caps and figure out what Medicare therapy coverage you have. Let’s break it down.
Does Medicare Cover Physical Therapy for Back Pain?
Back pain is one of the most common symptoms that leads to physical therapy. As you age, back pain is almost inevitable. It’s easy to fall into bad habits and poor posture. If you have back pain that lasts for a few weeks or longer, most doctors will recommend physical therapy.
A licensed and professional physical therapist will not only help you decrease pain but also educate you on how to prevent back pain in the future. He or she may even teach you some physical therapy exercises to perform at home.
Alternatively, seniors and Medicare eligibles who have a hard time getting to a doctor’s office may opt for a home nurse who is licensed to assist with physical therapy. In most cases, if your home nurse happens to double as a physical therapist, you will be covered under Part B.
Unfortunately, these services are not free.
Medicare Physical Therapy Cap | Medicare Plan Finder
How Much Does Medicare Pay for Physical Therapy?
Medicare Part B will cover your medically necessary outpatient therapy (physical, speech-language pathology, occupational) at 80 percent, you will likely be responsible for 20 percent of all Medicare-approved costs.
Previously, Medicare only covered up to 80 percent of $2,040 ($1,608) for physical and speech-language therapy services and another 80 percent of $2,040 ($1,608) for occupational therapy services. That meant that, for example, if your physical therapy appointments cost you $100, Medicare would have only covered about 20 visits per year.
Beneficiaries were receiving notices titled, “Advance Beneficiary Notice of Noncoverage.” The notice will tell you what Medicare will can or cannot continue to cover so that you can make informed choices about whether or not you want to continue your physical therapy.
Thankfully, physical, occupational, and speech therapy patients with Medicare won’t have that problem in (833)-567-3163.
Medicare Physical Therapy Billing
Medicare Physical Therapy Caps | Medicare Plan Finder
When it comes to paying the bills for your physical therapy, you may want to consider adding either a Medicare Advantage plan or a Medicare Supplement plan. Even though Original Medicare Part B covers physical therapy, the cap will hold you back. Adding Medicare Advantage or Medicare Supplements may give you the coverage you need to pay the bills.
The good news is that everyone who is eligible for Original Medicare is also eligible for Medicare Advantage and Medicare Supplement plans. You can’t have both, so you’ll have to choose one.
Medicare Advantage plans are offered by private insurance companies and are designed to add additional covered services like dental, vision, hearing, fitness.
Alternatively, Medicare Supplement plans do not provide coverage for additional services but instead provide additional financial coverage. These plans are designed to help you pay for your coinsurance, copayments, and deductibles. You’ll have to decide what makes the most sense for you and your needs: more financial coverage, or more covered services?
Your physical therapist can discuss the physical therapy benefits specific to your condition and personal medical history.
Does Medicare Cover Transportation to Physical Therapy Appointments?
Original Medicare does not cover non-emergency medical transportation. Some Medicare Advantage plans can cover Medicare transportation benefits including travel to and from doctor’s appointments.
How to Find a Physical Therapist Who Accepts Medicare
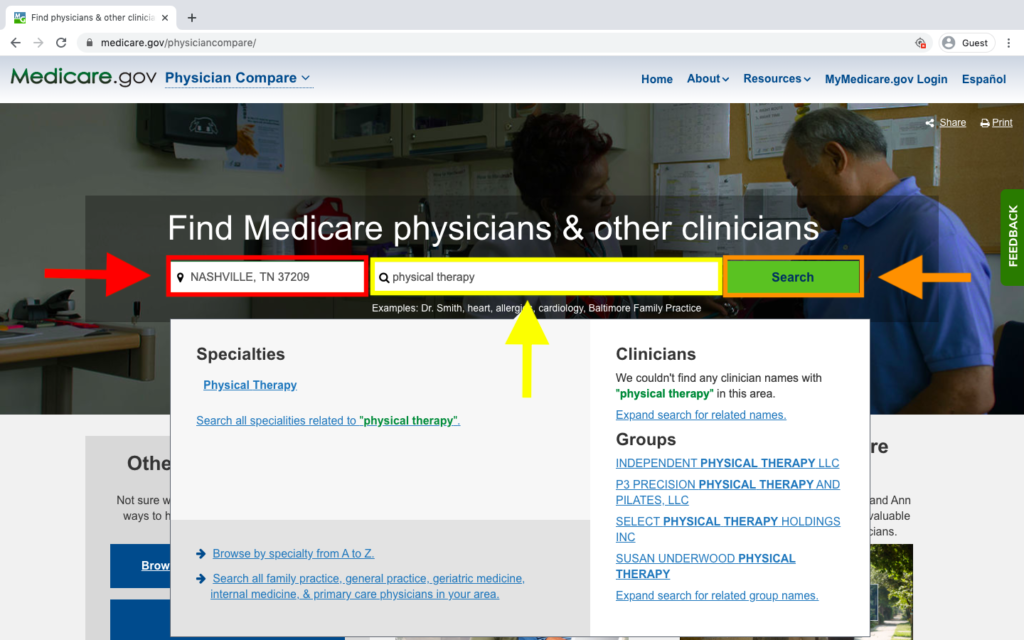
Finding a local physical therapy practice that takes Medicare may be easier than you think. If you’re looking for physical therapy near you, click here to get started. Medicare.gov’s Physician Compare website allows you to find providers who specialize in the services you need including physical therapy.
Enter your zip code beside the red arrow. We used our home office’s zip code in Nashville, Tennessee, which is 37209. Then type “physical therapy” in above the yellow arrow. After that, click “Search” beside the orange arrow.
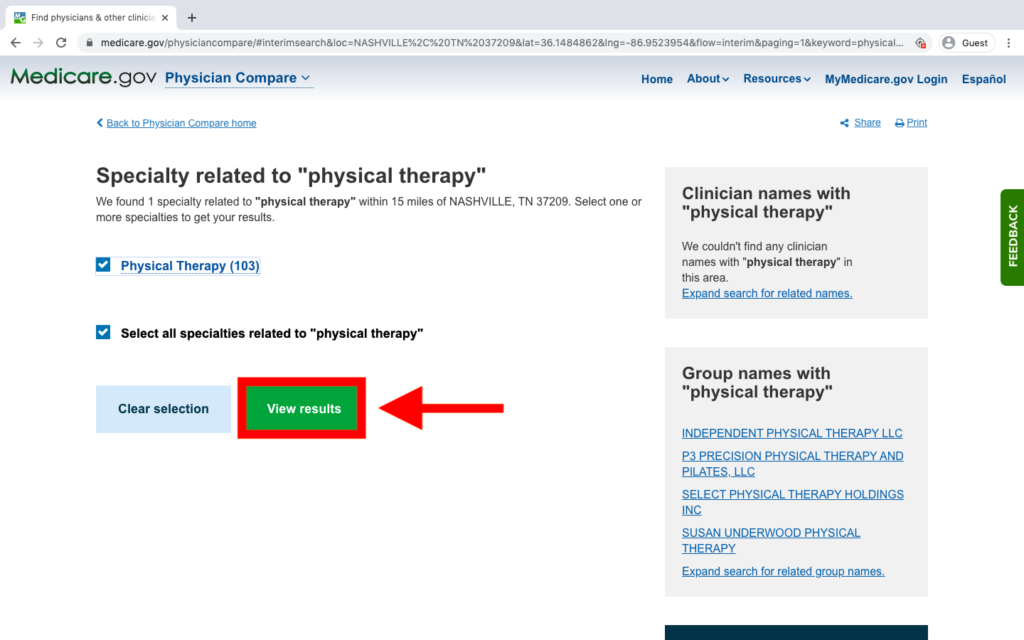
You confirm the service you need on the next page. If the boxes beside “Physical Therapy” and “Select all specialties related to ‘physical therapy'” are white, click in them to make both boxes have check marks. Then click “View results.”
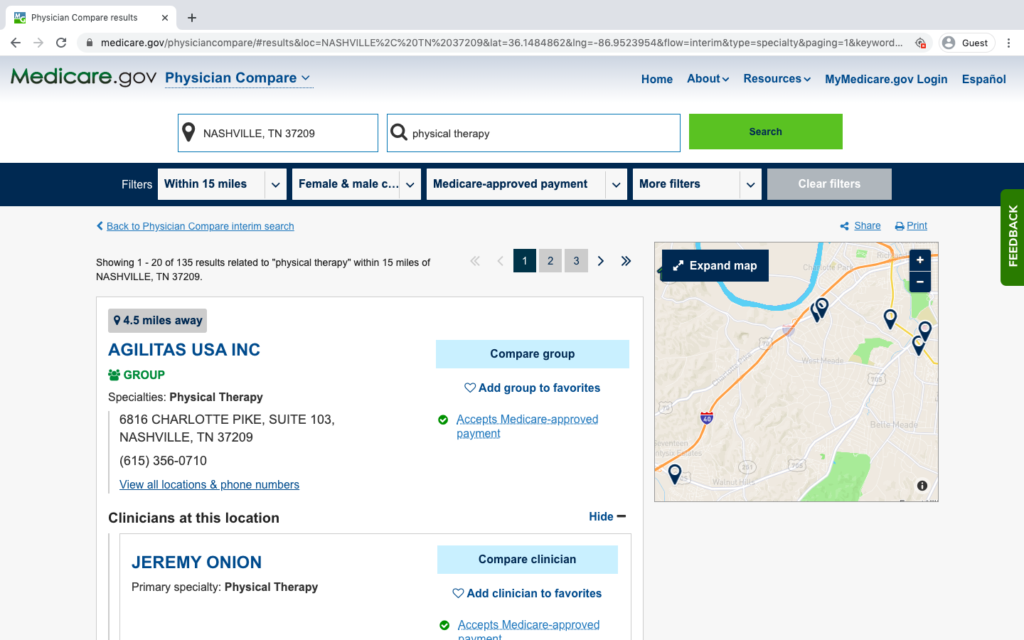
The last step is scrolling through the list of providers and making some calls. You may have to call more than one physical therapy practice to find one that fits your medical and budget needs.
Need a New Medicare Plan?
Our agents can help you decide if Medicare Advantage or Medicare Supplements are right for you. We have agents in 50 states and we’re constantly growing!
Plus, our agents are licensed to sell plans from many of the major insurance carriers in your area, which means we are NOT biased. We can help you set up an appointment with an agent who can show you how to choose the right Medicare plan for your needs.
Most seniors and Medicare beneficiaries will have to wait until AEP (10/15 to 12/7) to change plans. Check outour post about Special Election Periods to see if you qualify for a SEP. Not sure if you qualify? That’s OK. Your licensed agent can help you find out if you qualify. Give us a call at (833)-567-3163 or click here to have Medicare Plan Finder call you.
This post was originally published on January 4, 2018, by Anastasia Iliou, and was most recently updated on January 6, 2020, by Troy Frink.
Does Medicare Cover Your Migraines?
Most of the 4 million Americans who suffer from migraines are between the ages of 18 and 44. These severe headaches usually diminish in later life but can still be a cause for concern for seniors. Migraines are reported in 17% of those over age 65 and may indicate a more serious underlying condition.
If you experience migraines, consult with your doctor for diagnosis and treatment. You may even be able to use your Medicare benefits to cover some of the cost!
Migraine symptoms and treatment
A migraine is defined as a severe, recurring headache that can last for hours or even days. Those who have these headaches chronically can show symptoms for around 15 days out of the month. If you are experiencing these symptoms, check with your physician as soon as you can. The most common symptoms are:
Throbbing pain on one or both sides of the head
Blurred vision or sensitivity to light
Nausea or dizziness
Confusion
Treatment Options
The primary treatment method for migraines is medication, both for relief and prevention. Your doctor may prescribe one or more of these medications depending on your diagnosis and symptoms.
Abortive migraine medications are used to relieve the symptoms of severe headaches as they occur. Some of these target serotonin in the brain to treat migraines directly, while others are used to treat individual symptoms. Some are available over-the-counter.
These abortive medications include:
Almotriptan (Axert)
Sumatriptan (Alsuma, Imitrex)
Zolmitriptan (Zomig)
Acetaminophen
Chlorpromazine (for treating nausea)
In cases of severe or frequent symptoms, your doctor may prescribe preventive migraine medications. These are meant to diminish the regularity and intensity of migraines before they happen.
Antidepressants and high blood pressure medications are commonly used for preventive treatment, as are some new injectables like Aimovig. Recently, doctors have even been using botox to treat migraines!
Migraine coverage with Medicare
Seniors who suffer from migraines might be wondering if their treatment will be covered by Medicare. The answer is sort of complicated: different parts of Medicare will cover certain migraine treatments, but only if your doctor confirms that you need it. For instance, Medicare Part B may cover injections, whereas Part D might cover prescription drugs.
What does Medicare Part B cover?
Part B can cover up to 80% of eligible expenses like doctor’s visits, labwork, or injections given by your physician. This means that after you meet your deductible, you will only have to pay 20% of the total cost. If you have a Medicare Supplement plan however, you may use it to cover that remaining coinsurance.
For more information on finding a Supplement plan to cover your medical expenses, call (833)-567-3163 to speak to a licensed agent today!
Does Medicare cover botox for migraines?
The FDA has approved the use of botox as a form of chronic migraine medication. It works by blocking certain chemicals that cause muscle pain. The primary botox injection sites for migraines are the muscle fibers in the forehead and neck, where migraine pain usually occurs. These injections are usually given every 10-12 weeks to remain effective.
In order for you to receive this coverage, your doctor may need to perform diagnostic tests to confirm to Medicare that migraine therapy is needed. Additionally, Medicare may require your physician to attempt other treatment options before it will cover botox injections.
Be sure to check with your doctor to ensure that your botox injections will be covered by Medicare!
What does Medicare Part D cover?
Medicare Part D mostly covers prescription medications in the form of pills, ointments, inhalers etc. While many prescription migraine medications may be covered by your Part D benefits, it’s always better to be safe than sorry. Before getting your medication, check the formulary for your Part D plan and make sure that your prescription is covered.
We know that Part B will pay for injections administered by a medical professional, but there are some injectable migraine medications meant for home use. This is another area where Part D can help cover the cost!
Does Medicare cover Aimovig?
A new form of preventive medication has recently emerged, called calcitonin gene-related peptide (CGRP) antagonists. Name brands like Aimovig come in prefilled autoinjector pens and are usually prescribed on a monthly basis.
Your Part D benefits may cover a prescription for Aimovig, but the actual amount you pay out-of-pocket can vary depending on if you’ve met your deductible. Don’t forget to check with your Part D plan provider to see if your Aimovig prescription will be covered and how much you will pay in coinsurance.
Treatments not covered by Medicare
There are many forms of alternative treatment for migraines that Medicare will not cover. Acupuncture has been suggested a way of treating migraines, as has massage therapy. Unfortunately, these methods have not been approved by the FDA and, as a general rule, Medicare will only cover FDA-approved treatments.
Chiropractic treatments have also been indicated as a method for natural migraine prevention and pain relief. Medicare however does not cover chiropractic care, except as part of subluxation correction.
If you are suffering from migraines, talk with your doctor about finding a form of migraine therapy that works for you and can be covered by your Medicare benefits! Call us today at (833)-567-3163 if you have any questions.
7 Important Things You Never Knew About Medicare
What is Medicare? Most people are familiar with short answer: Medicare is a federal health insurance program that covers people over the age of 65, people with certain disabilities, or those who suffer from either ESRD (end-stage renal disease) or ALS (Lou Gehrig’s Disease).
While this is probably the easiest way to explain Medicare, most people don’t know how complicated it can be once you dive below the surface. Here we’ve broken down the 7 most important facts about Medicare that you may have never heard before!
1. There are multiple parts of Medicare
Perhaps the biggest misconception about Medicare is that it’s one gigantic program. In truth, what we refer to as Medicare actually has four distinct components, or “parts.” You might hear some different names used but usually these parts will be designated as A, B, C, or D.
The Original Medicare program consists of Part A and Part B. Part A primarily covers inpatient hospital care, while Part B handles outpatient services like doctor visits. These two components of Original Medicare represent the basic coverage that is available to you when you turn 65.
Part C, often called Medicare Advantage plans, are offered by private health insurance companies. These allow recipients of parts A and B to also receive benefits like dental, vision, and prescription drug coverage depending on the plan they choose.
Medicare Advantage | Medicare Plan Finder
Part D, sometimes called a prescription drug plan (PDP), offers prescription drug coverage to beneficiaries enrolled in Medicare. These are offered by private insurance companies as an addition to the Original Medicare benefits, as Original Medicare does not include any drug coverage.
2. You can’t enroll whenever you want
Unfortunately, Medicare is not a program you can just enroll in at any time. It’s true that you are eligible for Medicare when you turn 65, but unless you qualify for automatic enrollment, you will need to sign up during one of the five designated enrollment periods.
The Initial Enrollment Period (IEP) is usually your primary opportunity for Medicare enrollment. If you are aging into the program, this IEP begins three months before your 65th birthday and extends to three months after, giving you seven months in total to enroll.
There is actually a second IEP, sometimes called IEP2, available for those who are eligible for Medicare before they turn 65, such as those with disabilities. This period also lasts seven months and gives these beneficiaries an opportunity to make changes to their plan.
The General Enrollment Period (GEP) is offered for first-time Medicare enrollees who did not join during their IEP. This period occurs every year from January 1 to March 31. Coverage applied for during this period begins on July 1st.
The AEP, or Annual Enrollment Period, starts every 10/15 and runs until 12/7. This period provides an opportunity for those already enrolled in Medicare to make changes to their coverage, such as adding a Part D plan or converting your Original Medicare to a Medicare Advantage plan.
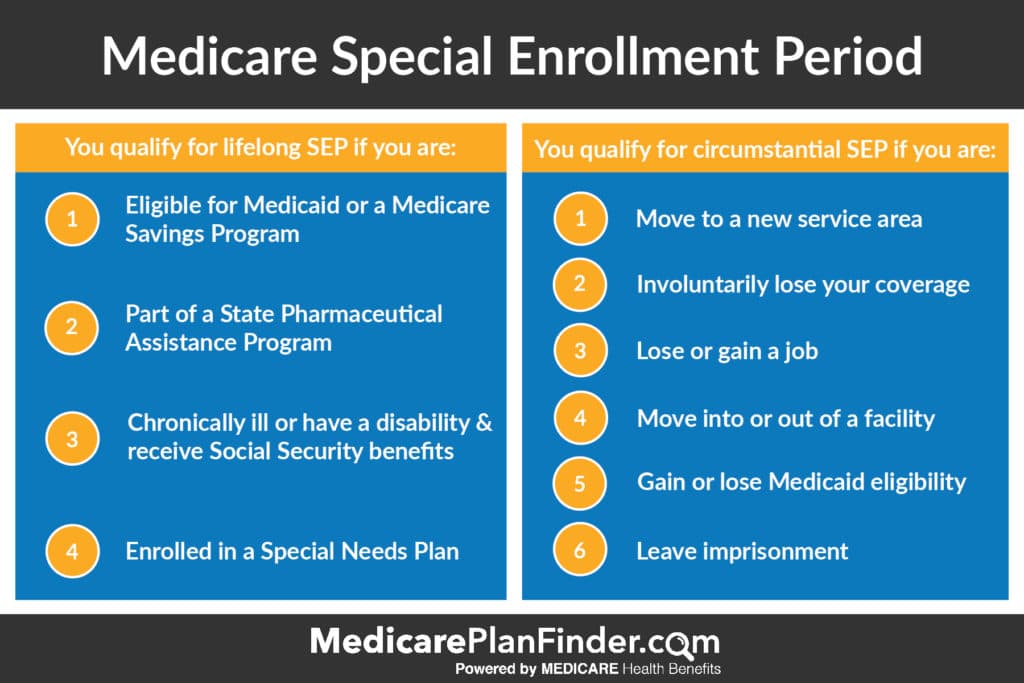
Special Enrollment Periods (SEPs) allow Medicare beneficiaries to make changes to their coverage outside of AEP. During these periods, people who are enrolled in a Special Needs Plan or who have recently lost a job can add to or switch their coverage. Check out the handy graphic below to see if you qualify for one of these SEPs.
Special Enrollment Period | Medicare Plan Finder
In 2019, a new enrollment period was introduced, called the Open Enrollment Period, or OEP. This period lasts from 1/1 to 3/31, and lets those who enrolled in Medicare Advantage during AEP make changes in their coverage without having to wait for the next AEP.
3. You may have to pay if you delay
If you do miss your IEP, you may have to pay penalties when you finally do enroll. The amount you will pay and the duration you will have to pay depends on which part of Medicare you enroll in and how long you waited.
The Part A penalty is incurred if you do not qualify for free, automatic enrollment and you fail to sign up for it when you are eligible. This penalty will be added to your premium to the tune of 10%, which you will have to pay for twice the number of years that you neglected to sign up.
If you enroll late in Part B, your premium will go up by about 10% for every year you were eligible but didn’t sign up. You will then have to pay this increased premium for the entire time you have Medicare Part B. You may also have to pay a penalty if you do not enroll in a Part D plan within the first three months that your Parts A & B are active. However, some of these penalties may be avoided if you qualify for a Special Enrollment Period.
4. Original Medicare only covers 80%
Once you are finally enrolled, you might wonder: “How much does Medicare cover?” The unfortunate truth is that it will not fully cover your medical expenses. Parts A & B will only cover up to 80% of the cost of Medicare-covered services, leaving you to pay the remaining 20% coinsurance.
This might not be too much trouble for routine doctor visits, but in the case of a medical emergency or hospital stay, the amount you pay out-of-pocket can skyrocket quickly. To cover that last 20%, consider purchasing a Medicare Supplement plan to add on to your Original Medicare coverage.
5. Original Medicare doesn’t cover dental, hearing, or vision
Many people might not realize that Medicare covers very little in the way of dental and hearing expenses, and virtually nothing when it comes to vision. Part A will sometimes pay for specific dental services if you have to get them while you are staying in a hospital, but will not pay for cleanings, fillings, dentures etc.
Medicare will sometimes cover diagnostic hearing exams if your physician orders it as part of their treatment, but will not cover hearing aids under any circumstances. For vision coverage, your options with Original Medicare are even more limited, as it will not pay for eye exams, glasses, or contact lenses.
There are some options that can provide vision, hearing, and dental coverage for seniors. A DVH (or Dental, Vision, Hearing) plan can be purchased to add to your Original Medicare benefits, or you might look to a Medicare Advantage policy to consolidate all of that coverage into one plan.
If you think Part C might be the best coverage option for you, click here or give us a call at (833)-567-3163 to have a licensed agent help you compare Medicare Advantage plans!
6. Original Medicare will not cover you abroad
Aside from a few very specific circumstances, Medicare Parts A and B will not cover your health care while you are traveling outside the United States. Medicare Part D plans are also invalid once you are more than 6 hours away from a U.S. port.
But there are some Medicare coverage options available for foreign travel, primarily in the form of Medicare Supplement (Medigap) plans.
7. Supplement plans have the same coverage, different cost
Medicare Supplement, or Medigap, insurance can be used to cover the out-of-pocket costs you may have to pay with Parts A and B. Insurance carriers offer many different types of Medigap plans, often sorted alphabetically, but they all must follow the same government regulations.
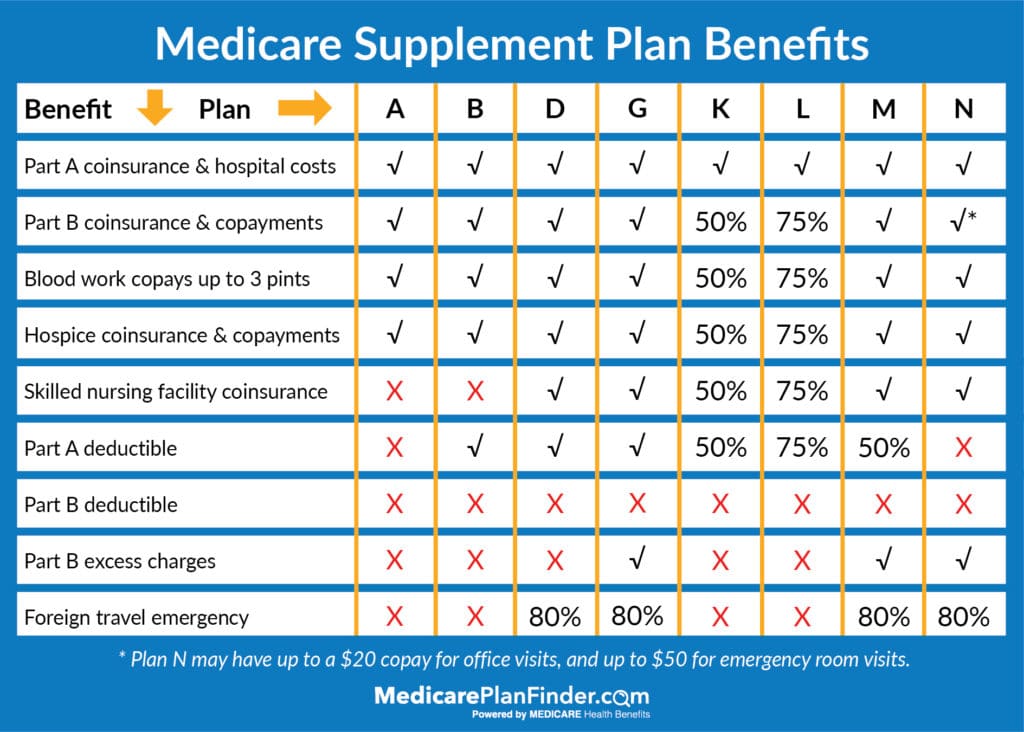
This means that Plan G from one carrier must provide the same benefits as Plan G from another carrier. Below is a quick breakdown of all the benefits covered by the different Medigap plan types.
Medicare Supplement Comparison Chart
Once you have found a Medigap plan type that meets your needs, you must consider the price. Insurance carriers must cover what is mandated by the government guidelines, but may charge very different rates for that coverage.
To find the best price, reach out to one of our licensed agents here or call us at (833)-567-3163 to have them run a personalized quote.
Medicare for the Blind
In a world full of technology, it is easy to assume we all have equal access to Medicare information. But for those who are blind or have visual impairment, this isn’t always the case. In fact, back in 2016, three blind Medicare beneficiaries changed the path for blind seniors and Medicare eligibles.
National Federation of the Blind vs. Centers for Medicare and Medicaid Services (CMS)
What happened to change Medicare for the blind? Three blind beneficiaries decided to challenge how Medicare information is provided to those who are blind or have low vision.
This dispute brought attention to those who are Medicare-eligible and blind and highlighted that they are not provided with equal access to Medicare information. They explained that there was a lack of materials available to someone who was blind or had vision loss.
The Case Results in New Medicare Benefits for the Blind
Two years later, NFB and CMS reached an agreement that requires CMS to provide health care materials for blind or visually impaired beneficiaries in formats such as Braille, large print, and audio. CMS is also now required to extend any time restraints for beneficiaries who have difficulty accessing time-sensitive information.
CMS has responded quickly and implemented critical procedural policies, including training employees in compliance with Section 504 of the Rehabilitation Act of 1973. They are also testing the accessibility of materials on Medicare.gov, providing e-books, and establishing Customer Accessibility Resource Staff.
Medicare and Disability for Blindness
Blind beneficiaries may qualify for benefits from the Social Security Administration (SSA) paid through Social Security Disability Insurance (SSDI) and/or Supplemental Security Income (SSI). These monthly payments can be used to help ensure you have what you need.
The SSA is the organization that administers Medicare benefits for most enrollees. Eligible retired railroad employees get Medicare benefits through the Railroad Retirement Board.
Legally Blind Meaning for Medicare
The Social Security Administration defines blindness as, “vision [that] can’t be corrected to better than 20/200 in your better eye or if your visual field is 20 degrees or less in your better eye for a period that lasted or is expected to last at least 12 months.”
If you think you qualify for SSDI benefits because of your blindness, click here to apply. Be sure to review this disability checklist before you start your application.
Medicare Benefits for the Blind
In general, any disease or medical issue that affects your vision will likely qualify for coverage Medicare Part B. Treatments, as well as yearly preventive visits and diagnostic exams, could be covered for conditions like macular degeneration or glaucoma.
Medicare may also cover routine eye exams for certain high-risk groups, such as diabetics who are more likely to develop conditions that impair their visual acuity.
Unfortunately, Medicare does not classify eyeglasses or contact lenses as “durable medical equipment” and will not pay for them in most cases. Some exceptions include Part B beneficiaries who have had cataract surgery or have a congenital absence.
Medicare Coverage for Service Animals
Medical coverage at the state and federal level do not cover service animals. The average service animal costs between $15,000-$30,000 to adopt. So if you’re on a restricted income, this might be too costly. What can you do if you need a service animal and can’t afford one?
There are numerous nonprofit organizations that raise, train, and offer service animals for reduced costs. Some organizations provide a service animal free of charge if you qualify.
Additionally, while Medicare benefits won’t pay for the obtaining, feeding, or care for the animal, disability benefits may be able to help cover this additional cost. Other necessities, such as support canes, may also be covered by these disability benefits.
The Americans with Disabilities Act (ADA) does not consider “emotional support animals, or companion animals” to be service animals. In order for your service animal qualify, it must be a dog, and help you “perform specific tasks” directly related to your disability. For example, many service animals are guide dogs that help blind owners get from point A to point B.
Qualifying for Medicaid & Medicare Benefits for the Blind
Medicaid is a state and federal program that provides medical benefits to people who meet certain income eligibility requirements. Medicare is public health insurance available to most people 65 and older, and most people who have ALS, ESRD, or who have received SSDI for at least 25 months.
People who qualify for both Medicare and Medicaid may be eligible for a type of Medicare Advantage plan called a Dual Special Needs Plan (DSNP). Medicare Advantage plans are private insurance policies that can offer many benefits that Original Medicare cannot such as meal delivery, non-emergency medical transportation, and coverage for hearing aids.
Your DSNP SEP allows you to make one change per quarter from January to September. You can still make changes to your coverage from October to December, however, but you can only make a change during AEP. The changes you make during this period will take effect on January 1 the following year.
Do you have the right Medicare coverage?
Are you looking for an insurance plan that provides benefits specific to you? Our licensed agents can explain your coverage options and help you find a plan that best fits your needs and budget.
If you are interested in arranging a no-cost, no-obligation appointment with an agent, complete this form or give us a call today at (833)-567-3163.
This post was originally published on August 23, 2018, by Kelsey Davis. The latest update was on January 15, 2025.
Medicare Inpatient vs. Outpatient: Why It’s Important to Know the Difference
Do you know the differences between inpatients and outpatients? The lines can get blurry, but the differences are important for your Medicare plan. Your classification as an inpatient or outpatient determines the coverage you get from Medicare.
Medicare Inpatient vs. Outpatient Coverage
In some cases, an overnight hospital stay does not automatically make you an inpatient. It is easy to assume that you are an “admitted” patient and receiving inpatient services if you are brought to a private or semi-private room, but that may not be the case. You may just be under observation and considered an outpatient.
If you’re getting emergency care, same-day surgery, x-rays, or lab tests, you may be under observation if you stay overnight. You aren’t considered an inpatient until a doctor admits you to the hospital.
Original Medicare Coverage for Inpatient and Outpatient Stays
You may notice that your Medicare card has two different dates for starting coverage: one for Part A, and one for Part B.
Medicare Part A is hospital insurance. Covered services include:
Difference Between Medicare Observation Status and Admission Status
For inpatient classification, a doctor has to purposely keep you at the hospital overnight and then formally admit you as such. Once you’re admitted, you have “admission status.”
A doctor may keep you for several hours under observation before deciding to admit you. During those hours, you have “observation status,” and you’re considered an outpatient. Any approved services during that time will be covered under your Part B.
Medicare Part A covers inpatient hospital stays, but Part B covers outpatient stays. If you need more care after leaving the hospital, you must have been an inpatient for at least three days for Medicare to cover a skilled nursing facility.
Medicare Prescription Drug Coverage
In most cases, prescription drugs that are part of your hospital visit will not be covered under your Part A or Part B. Medicare may cover prescription drugs as part of procedures, like anesthesia for knee replacement surgery, for example.
For the most part, you’ll need either a standalone Medicare Part D (prescription drug plan) or a Medicare Advantage plan if you want coverage for prescription drugs.
Medigap & Medicare Advantage Inpatient and Outpatient Benefits
Medigap (Medicare Supplement) plans are private insurance plans that cover the same services as Original Medicare. Your monthly premium covers financial items such as coinsurance and copays.
In 2027, there are eight different “letters” of Medicare Supplement plan. Each letter offers a different level of benefits. For example, Plan A covers Part A coinsurance and hospital costs, Part B coinsurance and copayments, blood work copays up to three pints, and hospice coinsurance and copayments.
Medicare Supplement Comparison Chart
Medicare Advantage plans are different. It’s important to know the distinction between the two because you cannot have both a Medigap plan and a Medicare Advantage plan.
Medicare Supplement plans only cover financial items, but Medicare Advantage plans can cover additional healthcare benefits such as meal delivery, non-emergency medical transportation, and even fitness classes! Medicare Advantage plans can also cover additional home health care services.
Get the Medicare Coverage You Need
The difference between Medicare inpatient and outpatient care may seem confusing. A licensed agent with Medicare Plan Finder may be able to help you find the right plan to cover your needs.
Our agents are highly trained and they can assess your needs and see if plans in your area can meet them. If you have questions and would like to speak to one of our licensed agents, please call (833)-567-3163 or contact us here to arrange a no-cost, no-obligation appointment today.
This post was originally published on July 13, 2017, by Anastasia Iliou. The latest update was on January 15, 2025.
3 Easy Steps to Making New Friends After Retirement
It’s always tough adjusting to big life changes and, as we get older, those changes seem to come faster and faster. Retiring, moving to a new city, or the death of a spouse can all be overwhelming and foster social withdrawal and isolation.
In fact, a recent survey of retirees showed that 11% of those questioned said they felt lonely and isolated, and almost half of those had recently moved to a new home. The AARP estimates that 42.6 million Americans over age 45 suffer from loneliness, which has been established as a risk factor for early illness and death, especially among seniors.
Fortunately, staying social is easier than ever in our modern age. Read on and learn some awesome methods for making and maintaining new friendships!
1. Follow Your Passions To Find Friends
It’s not easy knowing how to make friends when you are older. Stanford researchers have even suggested that baby boomers are withdrawing from social relationships more than any other group.
But finding new friends doesn’t have to be a guessing game. Just ask yourself a few simple questions: what do you like to do? What are you passionate about? What would you like to learn more about? Finding people with mutual interests and passions is the best place to start forging new friendships.
Social Networking for Seniors
More than ever, technology is helping us form and sustain new friendships. A quick Google search will bring you to senior friendship sites like Silversurfers or Buzz50, which feature forums and chat rooms tailored to older adults.
You can also find countless senior social media groups on platforms like Facebook, which have an increasingly large userbase over the age of 55. Here you can get connected with people online or even find a group that meets in real life. You can look for clubs, classes, or other hobby groups in your area and you’re sure to meet other like-minded social seniors.
2. Getting Out and About
In the social media age, congregating with people who have shared interests can be done from the comfort of your own home. But if you’re feeling cooped up, there are countless ways to meet new senior friends while staying active!
Senior Meetups
A senior meetup is a great place to meet seniors in your area that share your interests or passions. You may find these meetups at churches, gyms, retirement communities, or other places senior citizens hang out. There are even dedicated websites like Meetup.com, which connect you to in-person events based on your location and preferred activity. This helps provide a built-in ice breaker, as you can discuss your common interests.
If you are into photography or arts & crafts, find a workshop at a senior community center where you can advance your skills. If you enjoy cooking but are getting bored of the same old recipes, join a cooking class like the ones offered at Sur La Table. If you’re more of an outdoorsy type, there are groups that go for nature outings. Or you may prefer to find a group that gets together simply to eat, drink, and socialize.
Volunteer Opportunities for Seniors
Another great solution for the social isolation elderly people face is volunteering. This can be a great way to form social connections and do something good for others at the same time.
Organizations like Senior Corps offer programs that allow retirees to mentor young people, be a companion to other seniors who are less mobile, or share their expertise in community projects like building housing.
The AARP also has a program called the AARP Foundation Experience Corps, where those over the age of 50 can tutor young children to help improve their reading comprehension. This mentoring has an impressive impact on the students, improving their literacy skills by up to 60%.
Senior Fitness Classes
Working up a sweat is a tried-and-true strategy for staving off some of the side effects of isolation, such as depression and anxiety. But it can also be a terrific way to meet new people!
Active older adults can join a senior fitness program to help keep an exercise routine and chat with other seniors looking to stay in shape. Many of these programs, like Silversneakers®, may be covered by your insurance. If you have Medicare and are considering purchasing a Medicare Advantage plan to cover fitness programs, click here or give us a call at (833)-567-3163 to speak with a licensed agent.
Medicare Advantage | Medicare Plan Finder
3. Get To Know Your New Friends
Once you have made some new acquaintances, it can be difficult to form a closer bond. Plus, as we get older, we usually have less interest in maintaining superficial or casual relationships. Getting organized and keeping to a routine can help tremendously in developing old and new friendships alike.
Keep A Schedule To Stay In Touch
The best way to uphold and develop a relationship is to keep in contact on a regular basis. As your social group grows, start a calendar.
A well-organized calendar can ensure you never miss a meetup or social event that you want to attend. You can also use your calendar to keep track of birthdays and anniversaries. A simple “happy birthday” can go a long way in strengthening a burgeoning friendship.
Just as modern technology can help us meet new people, it can also help us stay in touch with friends and family alike. On social media platforms like Facebook, you can stay engaged with your social groups, old and new, by liking or commenting on statuses and pictures, as well as posting a few of your own! Emails and phone calls can also keep you in the loop with new friends.
Whichever way you choose to find your new social group, remember that forming long-lasting bonds takes time. If a new acquaintance does not respond to your efforts, try not to take it personally. There are plenty more people out there looking for the same connections you are. Keep searching and don’t get discouraged!
What to Do After the AEP for Medicare Ends
The Medicare Annual Enrollment Period (AEP) is a time when many Medicare beneficiaries can change their plans so their coverage best fits their needs.
If you are enrolled in Medicare, you will receive an “annual notice of change” (ANOC) which explains the changes coming to your current plan for the 2027 year. After reviewing your ANOC, you may decide you need to switch to a new plan.
The AEP for Medicare lasts from 10/15 to 12/7, but once it’s over and you’ve enrolled in a new plan, you may wonder what to do next.
You may wonder if you forgot something important or how you can take advantage of your plan’s new benefits.
Here’s what to do after the Medicare AEP ends:
Review Your Medicare Advantage Plan
If you enrolled in a Medicare Advantage (MA) plan and you decide that it doesn’t fit your needs, you can switch to a different Medicare Advantage plan from 1/1 to 3/31 the . This time period is called the Medicare Advantage Open Enrollment Period (OEP).
For example, if you enroll in a Medicare Advantage plan and it turns out that your doctor no longer takes your new insurance, you may be able to enroll in a new policy that your doctor accepts.* Talk to your agent about what plan options your doctor accepts and see if one of them can work for you.
Be sure to review a new plan’s deductibles, copays, and/or coinsurance. Your agent can help you determine your out-of-pocket costs and what your out-of-pocket maximum will be.
If you decide that Medicare Advantage (or Part C) isn’t for you, you can drop MA and return to Original Medicare (Medicare Part A and Part B) during the OEP. You can also enroll in a Medicare Part D (Prescription Drug) plan and/or a Medicare Supplement (Medigap) plan.
*Medicare Advantage plans are different in every location. We cannot guarantee that your doctor will accept any plans in your area.
Take a Look at Your Medicare Part D Prescription Drug Costs
Original Medicare does not cover most prescription drugs. If you needed Medicare prescription drug coverage during the annual election period for Medicare, you may have either signed up for a Medicare Part D prescription drug plan or a Medicare Advantage plan with prescription coverage.
Some Medicare Advantage plans even cover over-the-counter drugs! Neither Original Medicare nor Medicare Part D cover over-the-counter items. Your agent can help you determine what type of Medicare prescription coverage will work best for you.
Watch your drug costs and make sure that your plan is covering your medications properly. If your insurance company no longer covers one of your prescription drugs, talk to your agent. They can help you file an appeal.
Talk to your doctor before you file an appeal. Find out if there are alternatives that are on your plan’s formulary or if there are any less expensive drugs you can take.
You should also get a written explanation (coverage determination) from your prescription drug plan (PDP). The coverage determination document will go over whether a certain drug is covered, the qualifications to get a certain drug, your costs, and if the plan will make an exception to the coverage rules.
You should ask for an exception from your PDP if:
Your doctor prescribes a drug that’s not on your plan’s formulary
Your healthcare provider prescribes a drug that’s on your plan’s formulary, but you think you should pay less because no lower-tier drugs work for you
Your PDP will send you a letter with the coverage decision. You can file an appeal with Medicare if you disagree with the decision.
The appeals process has five different levels:
1. Redetermination from your plan: In this level, your plan re-evaluates your request for an exception.
2. Independent Review Entity (IRE) review: This is when a third party reviews your request for an exception, which you can request if your plan denies coverage after the redetermination.
3. Office of Medicare Hearings and Appeals (OMHA) decision: You can file an appeal with OMHA if you disagree with the IRE’s decision.
4. Medicare Appeals Council review: If OMHA doesn’t make a timely decision or you disagree with it, you can file an appeal with the Medicare Appeals Council.
5. Federal district court judicial review: This level is reserved for cases that meet a minimum dollar amount. You should get instructions on how to file an appeal in federal court with your Medicare Appeals Council letter.
Evaluate Your Medicare Advantage Plan
The AEP for Medicare is one of the only times of year most people can enroll in a Medicare Advantage plan.* During AEP, schedule a meeting with your agent to talk about your needs. You may determine that a Medigap plan provides all the coverage you need at a price you can afford, or you may determine that a Medicare Advantage plan is a better fit.
Medicare Advantage plans cover additional benefits that can include fitness classes, hearing, dental, and vision coverage. Your monthly premium may be lower with a MA plan, but your doctor network may be smaller.
You must choose a Medigap plan or a Medicare Advantage plan. You cannot have both at the same time.
Use the Open Enrollment Period that starts on 1/1 if you need to cancel your Medicare Advantage coverage and you want to return to your Medicare Supplement plan. For example, let’s say your doctor accepts Original Medicare, but they don’t accept any Medicare Advantage plans in your area.
You may want to enroll in a Medicare Supplement plan if you want coverage for copays and coinsurance. You may be responsible for paying Original Medicare coinsurance if you don’t have a Medigap plan that covers it.
Medigap plans cover different items than Medicare Advantage plans. While MA plans cover additional health benefits, Medicare Supplements cover financial items such as coinsurance and copays.
You can enroll in a Medicare Supplement plan at any time of year, so the time after AEP is a great time to learn about Medigap. Remember — most people can drop Medicare Advantage coverage only during AEP and OEP. You can only get a Medicare Supplement plan if you don’t already have a Medicare Advantage plan.
*Not all plans will be available in your service area or make sense for you.
Meet With Your Agent to Discuss Ancillary Products
Many health insurance agents also sell ancillary products such as life and final expense insurance. The beginning of the year is a great time to contact your agent because they might have more time for you than during the busy AEP for Medicare.
Schedule an appointment to talk about your retirement plan and how you can help your loved ones after you pass away. Write down a list of your long-term goals, financial risks, and plans for your 401(k) or other retirement accounts. The beginning of the year is a great time to create a solid plan for your financial future.
Let Us Help During OEP and Every Other Time of Year
If you have questions about your Medicare coverage, one of our highly-trained, licensed agents can help. An agent may be able to help you find a plan in your area that suits your budget and lifestyle needs. Whether it’s AEP or you’re enrolling in Medicare for the first time, let us help.
Call (833)-567-3163 or contact us here to arrange a no-cost, no-obligation appointment today.
Medicare Plan F Going Away (and Plan C) | ENROLL NOW!
When you enroll in Original Medicare (Part A and Part B), you have the option of increasing coverage by purchasing a Medicare Supplement plan (also called Medigap). These plans work alongside Original Medicare and add financial benefits (like help paying for your copayments, coinsurance, and yearly deductibles).
Every state (except Massachusetts, Minnesota, and Wisconsin) has ten different types of plans. Each plan is represented by a different letter (A, B, C, D, F, G, K, L, M, and N). Plan F and Plan C are the most inclusive, and in turn, are the most popular. But did you know both plans are going away in 2020?
Plan F has been a top-seller in many states for years and is the most comprehensive Medigap plan. Medicare Plan F covers:
Blood work copays up to three pints (100%)
Foreign travel emergency (80%)
Hospice coinsurance and copayments (100%)
Part A coinsurance and hospital costs (100%)
Part A deductible (100%)
Part B coinsurance and copayments (100%)
Part B deductible (100%)
Part B excess charges (100%)
Skilled nursing facility coinsurance (100%)
Medicare Plan C Benefits
Medicare Plan C covers all of the gaps from Original Medicare except for Part B excess charges. More specifically, Plan C includes the following:
Blood work copays up to three pints (100%)
Foreign travel emergency (80%)
Hospice coinsurance and copayments (100%)
Part A coinsurance and hospital costs (100%)
Part A deductible (100%)
Part B coinsurance and copayments (100%)
Part B deductible (100%)
Skilled nursing facility coinsurance (100%)
Plan F vs Plan C
Plan F is very similar to Plan C. The only difference is that Plan C does not cover Medicare excess charges. If a doctor does not accept Medicare assignment rates, you will be responsible for excess charges, but it can not exceed 15% of what Medicare pays. Some states do not allow doctors to issue excess charges. If this is the case, Plan C will operate identically to Plan F.
Back in 2015, Congress passed the Medicare Access and CHIP Reauthorization Act. According to the act, starting on January 1, 2020, Medicare Supplement plans can no longer cover the Part B deductible, something that only Medigap Plans F and C currently cover.
When people don’t have to pay a deductible for services, they can end up overusing the doctor. For example, the might schedule an appointment with their doctor for a flu shot instead of using the free clinic inside their local grocery store. By visiting the doctor unnecessarily (and not paying for it), doctor’s offices are getting crowded and doctors aren’t being fully compensated for their time.
Eliminating Part B deductible coverage through Medigap works better financially for the Medicare program and for the doctors who accept it.
Thankfully, that Part B deductible is a small price to pay at $292 per year in 2027.
When will Medicare Plan F be discontinued? What about Plan C?
If you currently have Medicare Supplement Plan F or Plan C, don’t fret! This policy change only affects new beneficiaries. While your rates may increase (as they technically do every year), you will not lose your current coverage. However, if you leave your Medigap Plan F or Plan C for whatever reason, you will not be able to go back to it after 2020. If you do not have Plan F or Plan C, but you would like to, you can lock yourself in by enrolling NOW.
Due to this change, Plan F and Plan C beneficiaries will be given a chance to compare rates and switch to a new policy. If you decide you may want to switch, you can start by using our Medicare Plan Finder tool to decide what plan option (other than F) is best for you. If you still need help, click here to request a call from a local and licensed agent!
Will Plan F Costs Go Up in 2026?
It is certainly possible that Plan F costs will go up as it is phased out, though it hasn’t been confirmed yet.
Uniquely, the state of Idaho released a memo stating that the Idaho Department of Insurance “is NOT anticipating abnormally large premium increases on Plan F after 2020” in response to questions about Plan F leaving the market. Even people who already have Plan F in Idaho and want to switch to a different Plan F after this year should not face large rate increases.
Can I Get Plan F in 2026?
No, Medicare Plan F was discontinued back in 2020. If you already have Plan F, don’t worry – you can keep your coverage.
What is a good alternative to Plan F?
Many seniors and Medicare eligibles who already have Plan F are deciding to drop Plan F altogether and switch to Plan G. Plan G covers everything that Plan F does minus the Part B deductible, and it typically has a lower monthly premium.
Another popular plan is Plan N. The only benefit that is included in Plan G and not Plan N is the coverage for Part B excess charges. However, the thing to remember about excess charges is they are relatively rare. You will only be charged an excess charge if your provider does not accept Medicare.
Medicare Plan F vs Plan G
Great news! Plan G is almost identical to Plan F! The only difference is that Plan G does not cover the Part B deductible. Plan F may technically cover more, but many people consider Plan G to be a better value. Yes, you will need to pay your Part B deductible upon your first outpatient visit, but after you pay the deductible, you won’t need to pull your wallet out for the remainder of the year. Since you have to pay the Part B deductible yourself, Plan G has lower monthly premiums, and you could save more than $400 a year!
The standard Part B deductible for 2027 is $292, so the savings from choosing G over F significantly outweighs the cost of the deductible.
Is Medicare going away or just certain plans?
No, Medicare is not going away! Don’t panic!
Both Medicare Plan F and Medicare Plan C will be discontinued on January 1, 2020, but other options may be available in your area. We get it, Medicare coverage and plan options can be confusing and stressful. Policies are constantly changing, and healthcare will continue to evolve.
At Medicare Plan Finder, our agents are kept up to date on all the plans in your area and can help you find a plan that suits your needs and budget. If you’re interested in arranging a no-cost, no-obligation appointment, click here or give us a call at (833)-567-3163.
This blog was originally published on October 23, 2018, by Kelsey Davis. The latest update was updated on December 5, 2019, by Troy Frink.
5 Common Types of Mental Illness In The Elderly
Most of today’s senior citizens grew up in a time when mental illness was almost never discussed in public. Over the years though, the stigma around mental health has largely eroded and conversations about mental health often dominate the national discourse.
As mental illness becomes less taboo, its far-reaching impact on society is coming more into focus. For example, the effects of mental illness in seniors are studied much more closely than ever before.
Common Types of Mental Illness In Seniors
With this more extensive research, it’s easier to see what mental health issues are common in the elderly population. The most prominent issues in senior mental health are:
1. Depression
Depression is often cited as the most endemic mental illness in the elderly population today. Many older adults may shrug depression symptoms off as simply “feeling down,” meaning it often goes undiagnosed and may be even more pervasive than the research suggests.
There are many risk factors that specifically contribute to depression in the elderly. Retiring from work can cause strong feelings of boredom or listlessness, and the death or illness of a spouse can leave many stressed and sorrowful.
Not only can depression exacerbate the symptoms of other chronic health issues, it is also noted as a symptom of more severe mental disorders like dementia. This means seniors and their loved ones must be vigilant in watching for these depression symptoms:
Feelings of sadness, hopelessness, or emptiness
Lack of motivation or interest in previously enjoyed activities
Trouble concentrating and decision making
Thoughts of suicide or self-harm
2. Anxiety
Anxiety disorders can take many different forms, such as obsessive-compulsive disorder (OCD), panic disorder, or generalized anxiety disorder. These are usually characterized by intense fear or nervousness over issues most would consider normal, routine aspects of everyday life – locking doors or finding a parking spot, for example.
Like depression, anxiety in older adults is extraordinarily common and is often underdiagnosed. Older adults are especially prone to ignoring this illness, perhaps because the conventional medical wisdom of previous decades downplayed psychiatric symptoms if no physical issues existed.
It is important to note however, that some physical symptoms such as restlessness or fatigue may accompany anxiety, further confusing a potential diagnosis. Be on the lookout for these symptoms of anxiety in the elderly:
Irrational, obsessive, or catastrophic thoughts
Isolating behavior and withdrawal from others
Irritability or agitated moods
Fatigue and muscle soreness
3. Bipolar Disorder
Bipolar disorder is usually diagnosed in younger people, whose moods can swing quickly from elation to depression. If this diagnosis is made when the person is an older adult, it is referred to as late onset bipolar disorder and it is more likely to manifest as agitation.
Diagnosing bipolar disorder in seniors is made even more difficult by the misinterpretation of symptoms. Many of the warning signs of late onset bipolar disorder might be dismissed as simply the natural effects of aging. Furthermore, some symptoms may resemble the side effects of certain medications, like antidepressants and corticosteroids.
As the population steadily increases, the number of cases of late onset bipolar disorder is expected to rise along with it. Professional help should thus be sought if you or those close to you observe any of these bipolar symptoms in adults:
Agitation and irritability
Hyperactivity or distractibility
Loss of memory, judgment, or perception
4. Schizophrenia
Similar to bipolar disorder, schizophrenia is a condition usually diagnosed in younger individuals. Late onset schizophrenia is the terminology used when this disorder is observed in patients over the age of 45.
Schizophrenia is characterized by a broad range of symptoms, from the so-called “negative” symptoms, like loss of interest or enthusiasm in activities, all the way to delusions and hallucinations. While late onset schizophrenia is less common than the early onset variety, older sufferers are more likely to experience these severe symptoms.
Currently, doctors are unsure what causes late onset schizophrenia and why it is different from its other forms. Some have theorized that it is a subtype of the disorder which is triggered by life events. Regardless, it is vitally important that seniors and their loved ones keep an eye out for these late onset schizophrenia symptoms:
Delusions or hallucinations
Disorganized speech or behavior
“Negative” symptoms (absence or lack of interest in normal behaviors)
5. Dementia
Though it is classified separately from mental illnesses by the medical community, dementia is still a disorder that severely affects mental health. There are many different stages and forms of dementia but the most common incarnation is Alzheimer’s disease, which affects around 3 million people over age 65.
Alzheimer’s and other forms of dementia can develop from the natural cognitive decline that happens as we age, drawing a startling link between aging and mental health. All demographics should make mental health a priority but seniors especially should watch for these dementia symptoms:
Disorientation or confusion (forgetting dates, years etc.)
Decrease in memory
Decline in ability to communicate
Mood swings and emotional issues
Treatment & Medication
Mental illness treatment can involve inpatient or outpatient care.
Mental illness treatment can be a tricky process and it begins with a proper diagnosis of the condition’s type and cause. To do this, your doctor may administer several different types of tests, from cognitive and psychiatric evaluations to brain scans and lab tests.
Several different mental conditions have symptoms that overlap and make them difficult to diagnose without extensive medical experience. Once the condition is properly diagnosed, a doctor may suggest one of these common forms of mental illness treatment.
Outpatient Care
The most common forms of outpatient mental illness treatment are based around medication or psychotherapy, often used in conjunction. The efficacy of these treatments varies from person to person and sometimes multiple treatment options must be attempted before an effective one is found.
For depression and anxiety disorders, pharmacological methods of treatment usually utilize antidepressants. These can be prescribed in addition or as an alternative to psychotherapeutic approaches like “talk therapy.” The Anxiety and Depression Association of America (ADAA) also suggestsregular exercise and a balanced diet as ways of staving off these common mental illnesses, stressing the link between brain and gut health.
The primary medications used in treating bipolar disorder and schizophrenia in seniors are classified as antipsychotics, usually prescribed at a lower dosage than people diagnosed at a younger age. For non-drug treatments of more severe cases, inpatient care is often required for proper rehabilitation.
For the treatment of dementia in the elderly, no cure is currently known. But the symptoms can be managed and the Alzheimer’s Association recommends a non-drug approach before attempting medication. These can begin with something as simple as changing the environment of those with dementia to remove obstacles and promote a general ease of mind.
If these non-drug approaches are not effective, certain types of medications like cholinesterase inhibitors and memantine may be prescribed to temporarily relieve some symptoms. Other approaches may include the use of antidepressants or anxiolytics, depending on the specific behaviors and symptoms that manifest.
Inpatient Care
With the more serious mental illnesses widely seen among seniors, outpatient care may not be an option. Those suffering from bipolar disorder or dementia may not be able to maintain their daily functions on their own and must turn to medical services that can attend to their needs 24 hours a day.
For example, the most common form of therapy for conditions like schizophrenia is a psychosocial approach, where a team of doctors, nurses, social workers and other professionals work in close contact with the patient to monitor their symptoms, both mental and physical, and help them maintain social skills and daily activities.
In these severe cases of mental illness, the accessibility of quality inpatient care has been shown to be a determining factor in recovery. The psychosocial interactions common in inpatient care are now considered to play a necessary role in a comprehensive intervention plan, as isolation can intensify many of the symptoms of these conditions.
What mental health services does Medicare cover?
Medicare can help pay for your mental health care.
When faced with one of these potentially life-changing illnesses, it is important to know what exactly is covered by your health insurance. Depending on the condition and its severity, some patients may need an extended stay in a hospital, which can quickly skyrocket the cost of care. Fortunately, Medicare covers many mental health services.
Medicare Part A Coverage
The types of mental health coverage offered differ depending on which elements of Medicare you are covered by. Medicare Part A covers inpatient care, or the medical services you receive while staying in a hospital. The out-of-pocket costs not covered are the same regardless of the type of hospital, general or psychiatric.
Medicare measures your use of hospital facilities using benefit periods. These benefit periods are tallied in increments of 60 days, beginning on the day you’re admitted to a hospital and ending when you haven’t used any hospital services for 60 consecutive days.
If your stay is in a general hospital, there is no limit to the amount of benefit periods Medicare will cover. In a specialized psychiatric facility though, Part A will only pay for up to 190 days of inpatient care during your lifetime.
For further information on how the co-payments break down, check out this handy graphic or see our more in-depth article here.
Medicare Part B Coverage
Medicare Part B will cover most of the cost associated with outpatient mental healthcare. This primarily includes any doctor visits that may relate to your mental health, including appointments with psychiatrists, psychologists, nurses, and social workers.
Therapy and counseling may or may not be covered depending on if the doctor accepts Medicare assignment. Finding a therapist who takes Medicare is now easier than ever, using tailored search tools like the one developed by Psychology Today, available here.
After you meet your Part B deductible, Medicare will cover 80% of their approved amount to the doctor or therapist. This leaves a 20% copay that will have to be paid out-of-pocket. For some, this may still be too expensive and that’s where Medicare Advantage, Supplement, and Part D plans can help!
Medicare Advantage, Supplement & Part D Coverage
There are several types of supplemental coverage that can help pay for Medicare mental health benefits.
Part D plans, for example, offer coverage for prescription drugs which are not covered by original Medicare. For the year of 2020, these plans will have an annual deductible of $435 but, since they are provided by private insurance, there is some variation in the deductible, which may be waived, reduced, or charged upfront.
Medicare Advantage plans, also referred to as Part C, can offer far more benefits than parts A and B alone, including prescription drugs, dental and vision coverage, and group fitness classes tailored to seniors.
Medicare Advantage | Medicare Plan Finder
Alternately, you may choose to apply for a Medicare Supplement plan, which provides additional financial benefits to help with mental health-related costs like copayments and deductibles. There are up to ten distinct types of Medicare Supplement plans (designated alphabetically from A – N). Each plan may differ in coverage and price.
Medicare Supplements | Medicare Plan Finder
Whatever supplemental coverage you are looking for, it is best to seek the help of a licensed agent who can fully explain the details of each plan and find one that works best for you or your loved one. To contact one of these professionals directly for free, no-strings-attached information, fill out this form or give us a call at (833)-567-3163 and get covered today!