7 Ways Medicare Coverage Can Matter as Healthcare Needs Change
Healthcare needs rarely stay the same from one year to the next. A person who mainly needs preventive care today could require new prescriptions, specialist visits, rehabilitation, or more frequent medical appointments in the future. Medicare provides important healthcare coverage, but the way beneficiaries use that coverage can change considerably over time.
Understanding those possibilities can help people evaluate their coverage based on more than their current medical needs. Here are seven ways Medicare coverage can become particularly important as healthcare needs evolve.
Specialist Care May Increase
Many people receive much of their routine healthcare through a primary care provider. Over time, however, new diagnoses or persistent symptoms may lead to appointments with cardiologists, orthopedists, endocrinologists, neurologists, dermatologists, or other specialists.
Access to these providers is an important consideration when choosing the best Medicare plan for you. Original Medicare generally allows beneficiaries to see any doctor or hospital that accepts Medicare, while Medicare Advantage plans typically use provider networks and may have different rules for accessing specialists.
Someone who rarely sees specialists today may have very different needs several years from now. Understanding how a plan handles specialist care can make it easier to evaluate whether its provider access and cost structure fit individual priorities.
Compare Plans from All Carriers in 1 Minute!
Prescription Needs Can Change
Prescription use can change after a new diagnosis, surgery, hospital stay, or change in an existing health condition. A beneficiary who takes only one or two medications now could eventually need several prescriptions with very different costs.
Medicare drug coverage deserves regular attention for this reason. Formularies can differ among plans, and covered medications may fall into different cost-sharing tiers. Plans can also change their formularies and costs from year to year.
Beneficiaries should review their prescription coverage during Medicare’s annual enrollment periods rather than assuming last year’s plan remains the right fit. Comparing current medications with a plan’s formulary, pharmacy network, and expected out-of-pocket costs can reveal meaningful differences.
Rehabilitation May Become Necessary
Surgery, injuries, strokes, joint replacements, and other medical events can create a need for rehabilitation. Depending on the situation, recovery may involve physical therapy, occupational therapy, skilled nursing care, home health services, or other forms of medical support.
Medicare covers many rehabilitation services when applicable requirements are met, but the setting and circumstances matter. Beneficiaries may encounter deductibles, coinsurance, coverage requirements, or limits related to particular services.
Learning how Medicare handles rehabilitation before it is needed can reduce confusion during recovery. It also helps beneficiaries understand why healthcare coverage involves much more than physician appointments and prescriptions.
Behavioral Healthcare Can Matter
Mental health and substance use care can become necessary at any stage of adulthood. Medicare covers a range of mental health services, including certain outpatient services, inpatient psychiatric care, and treatment for substance use disorders when Medicare requirements are met.
Depending on a person’s medical needs, appropriate care could include counseling, psychiatric services, medication management, or evidence-based treatment for addiction, psychiatric issues or other behavioral health concerns. The appropriate provider and level of care depend on the individual rather than age alone.
Beneficiaries should consider provider availability as well as coverage. Finding a behavioral health professional who accepts a particular form of Medicare coverage can affect access to care, especially when ongoing appointments are necessary.
Medical Equipment May Be Needed
Changes in mobility or health can introduce expenses that were never previously part of someone’s healthcare budget. Walkers, wheelchairs, hospital beds, oxygen equipment, blood sugar monitors, and other forms of durable medical equipment may become medically necessary.
Medicare Part B covers certain durable medical equipment when eligibility and supplier requirements are satisfied. Beneficiaries should understand that where they obtain equipment can matter. Using an appropriate Medicare-enrolled supplier or a supplier permitted under their plan can help avoid unexpected coverage problems.
Equipment needs can also change over time. Someone recovering from surgery may need assistance temporarily, while another beneficiary may require equipment for ongoing management of a health condition.
Hospital Care Can Grow
A hospital stay can quickly change the way someone uses Medicare. Inpatient treatment may lead to specialist appointments, prescriptions, rehabilitation, home health services, medical equipment, or follow-up procedures after discharge.
Understanding the distinction between different parts of Medicare becomes particularly useful during these situations. Part A generally covers eligible inpatient hospital care, while Part B covers many physician and outpatient services. Medicare Advantage plans provide Part A and Part B benefits through private insurers approved by Medicare and may have their own network and cost-sharing structures.
Reviewing these differences before a major medical event makes Medicare easier to navigate when more services are needed at once.
Annual Reviews Become Valuable
Healthcare needs change, and Medicare plan details can change as well. Prescription formularies, provider networks, premiums, deductibles, copayments, and other plan features may differ from one year to the next.
An annual coverage review gives beneficiaries an opportunity to compare their current healthcare needs with the coverage they will have for the coming year. That does not mean everyone needs to change plans annually. It means beneficiaries should know what they have before deciding whether to keep it.
No Medicare option can predict every future healthcare need. Regularly reviewing coverage, providers, prescriptions, and expected costs can help beneficiaries make informed choices as their health and medical needs change.
Compare Plans from All Carriers in 1 Minute!
Medicare Advantage Plans vs Supplemental Plans
Medicare Advantage and Medicare Supplement Insurance, also called Medigap, are two different ways to manage your Medicare coverage and healthcare costs.
Medicare Advantage may be a good fit if you want lower monthly premiums, prescription drug coverage, and additional benefits such as dental, vision, and hearing. Medicare Supplement insurance may be a better fit if you want more flexibility when choosing doctors and more predictable out-of-pocket costs for Medicare-covered services.
Neither option is automatically better. The right choice depends on your healthcare needs, budget, preferred doctors, prescription medications, and how often you travel.
Let’s compare how they work, what they cost, and the important differences to consider before choosing a plan.
Medicare Advantage vs. Medicare Supplement: Key Differences
Feature
Medicare Advantage
Medicare Supplement (Medigap)
How coverage works
Private plan provides your Part A and Part B benefits
Works alongside Original Medicare
Monthly premiums
Some plans have $0 premiums
Separate monthly Medigap premium
Medicare Part B premium
Generally still required
Still required
Doctor networks
Often uses HMO or PPO networks
Generally any provider nationwide who accepts Medicare
Prescription drugs
Included in most plans
Requires separate Part D coverage
Dental, vision, and hearing
Often includes additional benefits
Generally not covered
Out-of-pocket costs
Copays, coinsurance, and deductibles vary by plan
Helps pay certain Original Medicare cost-sharing expenses
Annual out-of-pocket limit
Yes, for covered Part A and Part B services
Depends on the Medigap plan; Plans K and L have specific limits
Referrals and prior authorization
May be required
Original Medicare generally does not require prior authorization
Travel within the U.S.
Coverage rules and networks vary
Broad access to Medicare-accepting providers
Foreign travel
Limited; some plans offer emergency benefits
Some plans cover limited foreign travel emergencies
Compare Plans from All Carriers in 1 Minute!
The biggest difference is how you receive your Medicare benefits.
With Medicare Advantage, a private insurance company administers your Medicare coverage. With Medigap, you keep Original Medicare and purchase additional insurance to help pay certain costs Medicare leaves behind.
You cannot use Medicare Advantage and Medigap together to cover the same healthcare expenses.
What Is Medicare Advantage?
Medicare Advantage plans, also known as Medicare Part C, are offered by private insurance companies approved by Medicare.
To enroll in Medicare Advantage, you must have Medicare Part A and Part B. Once enrolled, you receive most of your Medicare-covered healthcare services through your Medicare Advantage plan rather than through Original Medicare.
Medicare Advantage plans must cover medically necessary services covered by Original Medicare, with certain exceptions such as hospice care, which remains covered by Original Medicare.
Many Medicare Advantage plans also offer benefits beyond Original Medicare.
Depending on the plan and your eligibility, additional benefits may include:
Not every Medicare Advantage plan includes these benefits. Coverage amounts, restrictions, and eligibility requirements vary.
Types of Medicare Advantage Plans
Two common types of Medicare Advantage plans are HMOs and PPOs.
Health Maintenance Organization (HMO):Medicare Advantage HMO plans generally require you to use doctors and hospitals within the plan’s network, except in certain circumstances such as emergencies. You may also need referrals to see specialists.
Preferred Provider Organization (PPO):Medicare Advantage PPO plans generally provide greater flexibility to see out-of-network providers, although you may pay more for those services.
Other Medicare Advantage options include Private Fee-for-Service plans and Special Needs Plans.
Plan availability depends on where you live.
How Much Does Medicare Advantage Cost?
Some Medicare Advantage plans have monthly premiums as low as $0. However, a $0 plan premium does not mean healthcare is free.
You generally must continue paying your Medicare Part B premium, although some Medicare Advantage plans may help pay part or all of that premium.
You may also pay deductibles, copayments, or coinsurance when receiving medical services.
One important protection is that Medicare Advantage plans have an annual out-of-pocket maximum for covered Part A and Part B services.
Once you reach your plan’s applicable limit, you generally pay nothing for covered Part A and Part B services for the remainder of the year.
Prescription drug costs and monthly premiums do not count toward this medical out-of-pocket maximum.
Compare Plans from All Carriers in 1 Minute!
What Is Medicare Supplement Insurance (Medigap)?
Medicare Supplement Insurance, commonly called Medigap, is private insurance designed to help pay certain out-of-pocket expenses associated with Original Medicare.
Original Medicare covers many hospital and medical services, but beneficiaries may still be responsible for deductibles, copayments, and coinsurance.
Medigap helps pay some of these remaining expenses, depending on the policy you select.
For example, Original Medicare generally pays 80% of the Medicare-approved amount for covered Part B services after you meet the deductible.
Certain Medigap plans can pay the remaining 20%, reducing your out-of-pocket expenses.
Unlike Medicare Advantage, Medigap does not replace the way you receive your Original Medicare benefits.
You keep Medicare Part A and Part B, and your Medigap policy supplements that coverage.
What Does Medigap Cover?
Medigap benefits depend on the standardized plan you purchase.
Depending on the plan, coverage may help pay:
Medicare Part A hospital coinsurance
Medicare Part A deductible
Medicare Part B coinsurance or copayments
Skilled nursing facility coinsurance
Hospice care cost sharing
Certain foreign travel emergency expenses
Medigap policies generally do not cover routine dental care, vision care, hearing aids, long-term care, or private-duty nursing.
They also do not cover your monthly Medicare Part B premium.
Understanding Medigap Plans
In most states, Medigap policies are standardized using letters such as Plan A, Plan B, Plan G, and Plan N.
For example, a standard Medigap Plan G from one insurance company provides the same basic medical benefits as a standard Plan G from another insurance company.
However, the monthly premiums can be very different.
Massachusetts, Minnesota, and Wisconsin use different Medigap standardization rules.
Two popular options to compare are Plan G and Plan N.
Plan G provides extensive coverage of Original Medicare cost-sharing expenses, although you remain responsible for the Part B deductible.
Plan N also provides substantial coverage but may require certain office visit and emergency room copayments, and it does not cover Part B excess charges.
Medigap Plan F is another comprehensive option, but it generally is not available to people who became eligible for Medicare on or after January 1, 2020.
How Much Does Medigap Cost?
With Medigap, you generally pay three separate premiums or costs:
Your monthly Medicare Part B premium.
Your monthly Medigap policy premium.
Your separate Medicare Part D prescription drug plan premium, if you enroll in one.
You may also have certain deductibles or other out-of-pocket costs depending on your Medigap policy.
Although Medigap generally involves higher monthly premiums than many Medicare Advantage plans, it can make expenses for Medicare-covered healthcare services more predictable.
Medigap premiums vary by insurance company, location, age, pricing method, and other factors. Premiums may also increase over time.
Compare Plans from All Carriers in 1 Minute!
Is Medicare Advantage Cheaper Than Medigap?
Medicare Advantage often has a lower monthly premium than Medigap, but that does not necessarily mean it will cost less over an entire year.
Consider two hypothetical situations.
Example 1: Someone who rarely visits the doctor
A relatively healthy Medicare beneficiary might choose a Medicare Advantage plan with a $0 monthly plan premium.
If they only need preventive care and a few doctor visits, their total annual medical expenses could be relatively low.
In this situation, paying a separate monthly Medigap premium might cost more.
Example 2: Someone who needs frequent medical care
Another beneficiary might see multiple specialists, receive ongoing treatments, and require regular outpatient procedures.
With Medicare Advantage, copayments and coinsurance could add up throughout the year, subject to the plan’s annual medical out-of-pocket maximum.
With Original Medicare and a comprehensive Medigap policy, many of those Medicare-covered expenses could be paid by the supplemental policy.
In this situation, paying a higher monthly premium might result in more predictable healthcare expenses.
Neither example guarantees that one option will be less expensive.
The important comparison is your total expected annual cost, including premiums, prescription medications, and out-of-pocket expenses.
Which Offers More Freedom to Choose Doctors?
Doctor access is one of the most important differences between Medicare Advantage and Medigap.
With Original Medicare and most Medigap policies, you can generally visit any doctor or hospital in the United States that accepts Medicare.
This can be particularly valuable if you travel frequently, spend part of the year in another state, or receive treatment from multiple specialists.
Medicare Advantage plans often operate through provider networks.
An HMO may require you to use network providers for most non-emergency services. A PPO may allow out-of-network care, but your costs can be higher.
Medicare Advantage plans may also require prior authorization for certain services.
Before enrolling, confirm that your preferred doctors, hospitals, and specialists participate in the plan and that your prescriptions are covered.
Which Is Better for Someone With Chronic Health Conditions?
If you have a chronic medical condition, your decision deserves additional attention.
Someone managing diabetes, heart disease, cancer, or another ongoing condition may need regular appointments, specialized treatments, medications, or hospital services.
Medigap may appeal to someone who wants broad access to Medicare-accepting providers and predictable cost sharing.
Medicare Advantage may appeal to someone who wants coordinated care, additional benefits, or access to a Special Needs Plan designed for certain qualifying conditions.
The best choice depends on the actual plans available to you and the providers and services you need.
It’s also important to consider future coverage flexibility.
Can You Switch From Medicare Advantage to Medigap?
You may be able to switch from Medicare Advantage back to Original Medicare during an applicable Medicare enrollment period.
However, that does not necessarily mean you can purchase any Medigap policy you want.
In most states, your best opportunity to purchase Medigap without medical underwriting is your six-month Medigap Open Enrollment Period, which begins when you are both 65 or older and enrolled in Medicare Part B.
Outside that period, insurance companies may be able to consider your health history when deciding whether to issue a policy or how much to charge.
Certain federal and state guaranteed issue protections provide exceptions.
This is an important consideration for someone thinking about enrolling in Medicare Advantage now and purchasing Medigap later.
Medicare Advantage vs. Medigap: Which Should You Choose?
Medicare Advantage may be worth considering if:
You want to keep your monthly plan premium low.
Your preferred doctors participate in the plan’s network.
You want prescription drug coverage included in the same plan.
You value additional dental, vision, hearing, or fitness benefits.
You are comfortable with the plan’s provider network and cost-sharing rules.
Medigap may be worth considering if:
You want broad access to doctors who accept Medicare.
You frequently travel or spend time in multiple states.
You prefer more predictable expenses for Medicare-covered services.
You are comfortable paying a separate monthly supplemental insurance premium.
You want to minimize certain deductibles, copayments, and coinsurance.
Remember that your health needs and financial circumstances can change over time.
The least expensive option today may not be the most appropriate option several years from now.
Frequently Asked Questions About Medicare Advantage vs. Supplemental Plans
Is Medicare Advantage better than Medigap?
Neither is universally better. Medicare Advantage may offer lower premiums and additional benefits, while Medigap can provide broader provider access and more predictable cost sharing for Original Medicare services.
Can I have both Medicare Advantage and Medigap?
No. Medigap cannot be used to pay Medicare Advantage deductibles, copayments, or coinsurance. These are different coverage arrangements.
Does Medigap cover prescription drugs?
Medigap policies sold today do not include prescription drug coverage. You can generally purchase a separate Medicare Part D plan while enrolled in Original Medicare.
Do Medicare Advantage plans have a maximum out-of-pocket limit?
Yes. Medicare Advantage plans have annual limits on out-of-pocket expenses for covered Part A and Part B services. The limits vary by plan and do not include all healthcare expenses.
Can I see any doctor with Medigap?
With Original Medicare and most Medigap policies, you can generally see any doctor nationwide who accepts Medicare. Medicare SELECT policies are an exception and may have network requirements.
Is Medigap worth the monthly premium?
It depends on how much you value predictable healthcare expenses, provider flexibility, and protection against certain Original Medicare cost-sharing obligations. Comparing your total annual costs can help you decide.
Compare Medicare Advantage and Medicare Supplement Plans in Your Area
Choosing between Medicare Advantage and Medigap is an important decision, but you don’t have to make it based on general information alone.
Plans, premiums, provider networks, and benefits vary by location and insurance company.
At Medicare Plan Finder, you can explore your coverage options and compare plans available in your area.
Before enrolling, review your doctors, prescriptions, expected healthcare needs, and total potential costs.
Compare Medicare plans in your ZIP code or call (833)-567-3163 to discuss your options.
Compare Plans from All Carriers in 1 Minute!
Original Medicare vs. Medicare Advantage
Original Medicare and Medicare Advantage are two ways to receive Medicare coverage. Both provide Medicare Part A and Part B benefits, but they differ in how you receive care, what you pay, and whether you use provider networks. Understanding those differences can help you choose coverage that fits your doctors, prescriptions, budget, and travel needs.
Original Medicare vs. Medicare Advantage: At a Glance
Feature
Original Medicare
Medicare Advantage (Part C)
Who provides coverage?
Federal Medicare program
Private insurance companies approved by Medicare
Hospital and medical benefits
Part A and Part B
Includes all medically necessary Part A and Part B services, except hospice care, which Original Medicare generally covers
Doctors and hospitals
Generally any provider nationwide that accepts Medicare
Often uses provider networks; rules vary by plan type
Prescription drugs
Usually add a separate Part D plan
Many plans include Part D coverage
Additional benefits
Generally does not cover routine dental, vision, or hearing services
Some plans offer additional dental, vision, hearing, or fitness benefits
Monthly premiums
Part B premium and Part A premium if applicable; optional Part D and Medigap premiums
Continue paying Part B premium and any additional plan premium
Out-of-pocket limit
No annual limit for Part A and Part B costs without supplemental coverage
Annual limit for covered Part A and Part B services under the plan
Medigap eligibility
May be paired with a Medigap policy
Cannot use Medigap to pay Medicare Advantage costs
What Is Original Medicare?
Original Medicare is the federal health insurance program that includes Part A (hospital insurance) and Part B (medical insurance). Medicare generally serves people age 65 and older and some younger people with qualifying disabilities or conditions.
Part A generally helps cover qualifying inpatient hospital stays, skilled nursing facility care, hospice care, and certain home health services. Part B generally helps cover medically necessary doctor services, outpatient care, preventive services, and durable medical equipment.
With Original Medicare, you can generally visit any doctor or hospital in the United States that accepts Medicare. You typically pay deductibles and coinsurance. For many Part B services, your share is 20% of the Medicare-approved amount after the deductible, although cost sharing varies by service.
Pros and Cons of Original Medicare
Broad provider access: You can generally see any provider nationwide who accepts Medicare, without a plan network.
Supplemental coverage options: You may be able to purchase a Medicare Supplement (Medigap) policy to help with certain out-of-pocket costs.
Separate drug coverage: You usually need a stand-alone Part D plan if you want Medicare prescription drug coverage.
No annual out-of-pocket maximum: Original Medicare alone does not cap your annual Part A and Part B spending.
Compare Plans from All Carriers in 1 Minute!
What Is Medicare Advantage?
Medicare Advantage, also called Medicare Part C, is an alternative way to receive your Medicare Part A and Part B benefits through a private insurance company approved by Medicare. You must have both Part A and Part B to join a Medicare Advantage plan.
Many Medicare Advantage plans include Part D prescription drug coverage and may offer extra benefits, such as routine dental, vision, hearing, or fitness services. Availability, benefits, costs, and provider networks vary by plan and location. You generally continue to pay your Part B premium, even if the Medicare Advantage plan has a $0 additional monthly premium.
Common Medicare Advantage Plan Types
HMO: A Health Maintenance Organization plan generally uses a provider network and may require referrals for certain specialist visits. Emergency and urgent care rules differ from routine care. Learn more about Medicare Advantage HMOs.
PPO: A Preferred Provider Organization plan generally lets you see providers outside its network, although your costs may be higher. PPOs generally do not require specialist referrals. Learn more about Medicare PPO plans.
Pros and Cons of Medicare Advantage
Predictable annual limit: Plans have an annual out-of-pocket maximum for covered Part A and Part B services. This limit does not include every expense, such as premiums or Part D drug costs.
Potential extra benefits: Some plans include services that Original Medicare generally does not cover.
Provider network considerations: Depending on your plan, you may need to use in-network doctors or obtain prior authorization for certain services.
Annual changes: Premiums, copays, drug formularies, networks, and benefits can change from year to year.
How Does Medigap Fit Into the Comparison?
Medicare Supplement Insurance, also called Medigap, is different from Medicare Advantage. Medigap is private supplemental insurance designed to help pay certain out-of-pocket costs under Original Medicare, such as deductibles and coinsurance. You cannot use a Medigap policy to cover costs under a Medicare Advantage plan.
Medigap policies sold today do not include prescription drug coverage. People who want drug coverage with Original Medicare and Medigap can generally consider a separate Part D plan. Eligibility to buy a Medigap policy, and whether an insurer can use medical underwriting, depend on enrollment timing and applicable state and federal rules.
Which Option May Be Better for You?
Original Medicare may appeal to people who value broad access to doctors nationwide or want to pair Medicare with a Medigap policy. Medicare Advantage may appeal to people who prefer an all-in-one plan with an annual medical out-of-pocket limit and potentially additional benefits, provided their preferred doctors, hospitals, and medications are covered.
Compare the total annual cost, not just the monthly premium. Review your prescriptions, preferred pharmacies, doctors, hospitals, expected medical needs, and how often you travel. There is no single best option for everyone.
Compare Plans from All Carriers in 1 Minute!
When Can You Change Medicare Coverage?
Medicare’s annual Open Enrollment Period runs from October 15 through December 7. During this period, eligible Medicare beneficiaries can generally switch between Original Medicare and Medicare Advantage or make changes to Medicare Advantage and Part D coverage for the following year. Other enrollment periods may apply depending on your circumstances.
Before switching from Medicare Advantage to Original Medicare, check whether you can obtain a Medigap policy on acceptable terms. Outside certain guaranteed-issue situations, Medigap insurers may be allowed to use medical underwriting, depending on your state and circumstances.
Frequently Asked Questions
Is Medicare Advantage the same as Original Medicare?
No. Original Medicare is administered by the federal government. Medicare Advantage plans are offered by private insurers approved by Medicare and provide your Part A and Part B benefits through the plan.
Can I have both Medicare Advantage and Medigap?
You cannot use a Medigap policy to pay Medicare Advantage plan costs. Medigap is designed to work with Original Medicare.
Do Medicare Advantage plans replace my Part B premium?
No. You generally must continue paying your Part B premium, even if your Medicare Advantage plan has a $0 additional premium. Some plans may offer a Part B premium reduction.
Do all Medicare Advantage plans include prescription drug coverage?
No. Many do, but not all. Check each plan’s drug coverage and rules before enrolling.
Need help reviewing your options? Compare plans available in your area and speak with a licensed insurance agent about your coverage needs.
Originally published September 20, 2018. Revised October 2026.
Spouse Medicare 101
Spouse Medicare 101
Medicare is different from other forms of insurance in a lot of ways. One of the biggest differences is that there are no family plans in Medicare. All Medicare coverage is individual-based.
However, even though Medicare and marriage are not directly related, your marital status can impact your Medicare costs in a few special ways.
Does Medicare Offer Spouse Coverage?
Medicare does not offer health coverage for spouses. You would have to be eligible on your own to qualify for Medicare – your spouse’s eligibility does not affect yours.
According to the rules set in place by the Centers for Medicare & Medicaid Services, marriage can affect your Medicare in the following ways:
Eligibility for Medicare cost savings can change due to your spouse’s income
Your Part D (prescription drug plan) premiums can be higher due to your spouse’s income
Premium-free Part A eligibility can be determined based on your spouse’s work history if they worked more than you.
So, can you get Medicare through your spouse? Not technically, no – but your marital status is not irrelevant.
Medicare if Spouse is Disabled
If one spouse is 65 and begins receiving Medicare and the other is not yet 65, there may be other ways to qualify. If you are diagnosed with ESRD or ALS or if you have been receiving SSDI (Social Security Disability Insurance) for at least two years, you can qualify for Medicare regardless of your age.
The good news is that if you do qualify for Medicare based on a disability, you may also qualify for a Medicare Special Needs Plan at a low cost.
Medicare Eligibility Requirements
The “main” Medicare program is called “Original Medicare.” You can qualify for Original Medicare by:
Unlike Medicaid, income does not impact Medicare eligibility. Additionally, unlike ACA plans, pre-existing conditions do not affect your Medicare costs or coverage. The only exception to this is in private Medigap (or Medicare Supplement) plans. If you do not enroll in a Medigap plan when you first become eligible for Medicare, you can be charged more based on your health history. Medigap plans are completely optional and are there for additional financial protection.
You can qualify for additional health and drug coverage through Medicare Advantage plans or Medicare prescription drug plans after you’ve enrolled in Original Medicare. Those plans cannot charge more based on your age or preexisting conditions.
Spouse Social Security Benefits
Even though the Social Security Administration manages Medicare enrollments, Social Security and Medicare are two vastly different things. There are a few differences in how your marital status affects your benefits.
For Social Security, your benefit is calculated based on your total household income according to your tax returns. That includes both your and your spouse’s income. Both you and your spouse can benefit from Social Security, even after one spouse has passed away.
Medicare does not work like that. Your marital status and income do not impact your eligibility, and there are no additional Medicare benefits given to a spouse after a Medicare beneficiary passes.
Health Insurance Options for Spouse of a Medicare Recipient
If one spouse is ineligible for Medicare and needs to find a different health plan, don’t panic – there are plenty of options for health insurance for the spouse of a Medicare recipient. You might want to start by checking to see if that spouse is eligible for Medicaid based on your total household income. If the answer is no, you’ll want to start looking at individual health plans in your area, which you can do through healthcare.gov/.
If the Medicare spouse has insurance through an employer when they become eligible for Medicare, the non-Medicare eligible spouse can also try getting COBRA until they are also eligible for Medicare. COBRA allows an individual, couple, or family to continue health coverage after leaving a job. However, keep in mind that even if you’re able to keep your health plan through COBRA, your costs may go up because your employer won’t be sponsoring the plan for you anymore.
Can my Wife get Medicare at 62?
To get Medicare, you have to either be 65 or have a qualifying disability.
If your husband or wife is just a few years short of Medicare eligibility, they can select an ACA plan or enroll in a short-term health plan. Short-term medical insurance can be renewed for up to 36 months, so it’s a good option if you’re within 36 months of becoming eligible for Medicare. Since these plans are designed for such short periods of time, they tend to be a bit cheaper than long-term plans, like the ones offered by your employer or the ACA.
Will non working spouse get Medicare?
People often wonder if Medicare is available for their non-working spouse. In short: yes, as long as they meet the age or disability requirements. However, your spouse’s costs may be different from yours. Your employment status does not determine your Medicare eligibility – but it can determine your Medicare costs as such:
If you or your spouse has worked and paid Medicare taxes for at least 40 quarters, you can qualify for premium-free Medicare Part A
If you and your spouse have worked and paid Medicare taxes for less than 30 quarters (or have not worked at all), your Medicare Part A premium will be $600/month in 2027.
Can my Wife get Medicare if she Never Worked?
Employment and marital status do not impact Medicare eligibility. Even someone who has never worked a day in their life can get Medicare, but their costs may be higher than someone who has been paying Medicare taxes.
Medicare vs. Medicaid
Unlike Medicare, your Medicaid coverage can be impacted by your marital status. While each state has somewhat different regulations, most of Medicaid eligibility is based on the Federal Poverty Line. Your income is calculated using your total household income, which is verified with your tax returns. Both your and your spouse’s income are included. That means that even if you qualify for Medicaid based on your income, you won’t be eligible if you and your spouse’s total income together is higher than your state’s limits.
How to Apply for Medicare Through a Spouse
You cannot apply for Medicare through your spouse. You’ll have to wait until you are eligible and then apply during your Initial Enrollment Period. If you qualify by turning 65, this period begins three months before your 65th birthday and ends three months after. If you miss that period, you can apply during the Open Enrollment Period from 1/1 through 3/31. To apply for Medicare online, visit the Social Security website, not medicare.gov.
How do I Apply for Spousal Medicare Benefits?
There are no spousal Medicare benefits – but you can apply for spousal Social Security benefits, here.
What is Not Covered Through Your Spouse’s Medicare?
Your spouse’s Medicare plan won’t provide health coverage for you. If you’re looking for Medicare for spouses, you’ll have to wait until the other spouse is eligible. Then, you can talk to an agent about finding separate plans that work for both of you and both fit into your household monthly budget.
Medicare Family Coverage
In general, Medicare is not available to non-qualifying spouses or dependants. However, if your child has a qualifying disability, they may be eligible for a Medicare plan of their own. Note that except for in the cases of ALS and ESRD, you will have to receive disability benefits for at least two years before you can enroll in Medicare.
How Does Getting Married Affect Medicare?
Getting married? Congrats! A new marriage often involves complicated discussions about finances, and you might be wondering, “will getting married affect my Medicare benefits?” The good news is that no, marriage does not affect your current Medicare benefits – but it CAN impact your eligibility for Medicare cost savings programs. For example, Medicare Savings Programs and Low-Income Subsidies for Medicare prescription coverage base eligibility on total household income. If your new spouse causes your household income to increase, you could become ineligible for these programs.
If you’re not yet 65, you might be wondering, “will I lose my disability Medicare if I get married?” No! Even if you are qualifying for Medicare based on disability and not age, your Medicare coverage won’t change based on your marital status.
Medicare Premium Payments: How Much Does Medicare cost for a Married Couple?
How much does a married couple pay for Medicare? Medicare is 100% individual, so each spouse will have to pay their own premium. There are no joint plans with joint costs.
Your Medicare Part A monthly premium will depend on your and your spouse’s work history and will range between $0 and $600 per month in 2027. Your Medicare Part B premium will be $209.50 in 2027 (unless you qualify for savings programs or have your premium covered by a Medigap plan). If you have Medicare Part D prescription drug coverage or either a Medicare Supplement or Medicare Advantage plan, you’ll pay a separate premium for those plans.
Do Husband and Wife pay Separate Medicare Premiums?
Yes – families and spouses cannot have joint Medicare plans. All premiums will be separate. Some people will have their premiums automatically deducted from their Social Security benefits.
How Your Spouse Might Affect how Much you Pay
Your spouse can reduce your Part A premium amount if they have worked more than you. Additionally, your spouse’s income can affect your eligibility for assistance programs such as Medicare Savings Programs, Medicaid, and Medicare Extra Help.
Medicare Plan Spousal Discounts
While Medicare does not provide spousal benefits, there are some plans that offer household discounts for plan premiums. You should always confirm with your agent whether or not a household discount exists as some companies may have specific requirements regarding spousal discounts.
Medicare Extra Help and Income Limits
The one thing that marriage will affect when it comes to Medicare is whether or not you qualify for the Extra Help Program, otherwise known as Low-Income Subsidy (LIS). LIS exists to help people with limited income pay for their prescription drugs. Those who qualify for the program pay less in drug premiums, copayments, and coinsurances.
Meet with a Licensed Agent
Even if you and your spouse have different Medicare plans, you can still share an agent!
Sharing an agent will make your enrollment process easier and help you build a relationship with someone who knows everything about Medicare plan options and can help you find savings.
Do you have a licensed agent? Have more questions about spouse Medicare? Give us a call today to set up a free meeting.
Our agents are licensed to sell many different insurance plans, so they can offer you an unbiased opinion and help you find the plan that truly works best for your needs.
Additional Benefits with Medicare Advantage Plans: What You Need to Know
When exploring Medicare options, Medicare Advantage plans stand out due to their potential to offer benefits beyond what Original Medicare covers. These additional benefits can significantly enhance your healthcare coverage, but it’s important to remember that not all Medicare Advantage plans are the same. Each plan varies in the additional benefits offered, making it crucial for beneficiaries to compare plans carefully based on their health needs and preferences.
Understanding Medicare Advantage Plans
Medicare Advantage plans are offered by private insurance companies approved by Medicare. They provide all the benefits of Medicare Part A and Medicare Part B, often combined with other health services that Original Medicare does not cover. The inclusion of additional benefits is one of the primary reasons these plans have gained popularity among Medicare beneficiaries.
Types of Additional Benefits
Dental, Vision, and Hearing Care
Most notably, many MA plans include coverage for dental, vision, and hearing care—services not covered by Original Medicare. Dental benefits might cover routine check-ups, cleanings, x-rays, and even some types of dental surgery. Vision care often includes eye exams, glasses, or contact lenses, while hearing care might cover hearing aids and auditory exams.
Wellness Programs
Many plans incorporate wellness programs such as fitness memberships or discounts on health and wellness services. These benefits are designed to promote a healthy lifestyle among seniors, which can help prevent or manage common diseases associated with aging.
Over-the-Counter Allowances
Some MA plans offer allowances for over-the-counter (OTC) products such as vitamins, pain relievers, and first aid supplies. This benefit can be particularly helpful as it reduces out-of-pocket costs for everyday health items.
Telehealth Services
With the growing popularity of digital health services, many MA plans now include telehealth benefits, allowing beneficiaries to consult with healthcare providers from the comfort of their homes. This is especially beneficial for those with mobility challenges or those living in remote areas.
Transportation Benefits
Transportation to and from healthcare facilities can be a significant hurdle for many seniors. Some MA plans offer transportation benefits, which can be a deciding factor for those who do not have easy access to transportation or who are unable to drive.
Nutritional Support
Recognizing the importance of nutrition in health, some plans provide benefits aimed at nutritional support, including meal deliveries, especially after hospital stays, or nutritionist consultations to help manage dietary needs.
Choosing the Right Plan
When selecting a Medicare Advantage plan, consider the following steps:
Assess Your Health Needs: Understand your specific health requirements—do you need regular vision or dental services, or are you managing a chronic condition that might benefit from wellness programs?
Compare Plans in Your Area: Not all plans are available in every location, and benefits can vary widely between plans. Use the Medicare Plan Finder tool or consult with a licensed insurance advisor to compare the plans available in your area.
Read the Fine Print: Once you’ve narrowed down your choices, look closely at the plan’s summary of benefits to understand what is and isn’t covered, and at what cost. Pay attention to any specific limitations or rules regarding how you can use the benefits.
Check Provider Networks: Ensure that your preferred doctors and hospitals are included in the plan’s network. Medicare Advantage plans often have network restrictions, and going out of network can result in higher out-of-pocket costs.
Review Star Ratings: Medicare rates plans based on quality and performance. These ratings can help you understand the quality of care and customer service you can expect from different plans.
Conclusion
Medicare Advantage plans can offer a range of additional benefits that enhance your healthcare experience, but the key is to choose wisely based on your personal health needs and circumstances. By doing thorough research and understanding the specifics of each plan, you can find a Medicare Advantage plan that not only meets your health needs but also enhances your quality of life through additional benefits.
However, the Medicare AEP only lasts from 10/15 through 12/7 of each year. Some people may qualify for a Special Enrollment Period and may be able to change plans outside of the AEP, but for many, this will be the only time to change plans!
What you Should do During Medicare AEP
Even if you think you have the best Medicare plan in the world, here are a few things you should definitely do during or leading up to Medicare AEP. If you need help with this, we advise giving us a call.
Check Eligibility for Savings.
Apply for LIS (Extra Help) prescription drug savings program) and other Medicare Savings Programs to see if you could be saving money. If you have low income, you may even want to try applying for Medicaid! The results could influence what coverage you are eligible for this AEP.
Review Current Medicare Coverage.
Did you receive your ANOC (Annual Notice of Change), and is anything in your plan changing? These letters are usually sent and received every year at the beginning of September.
What insurance do you have now?
Do you have Original Medicare only, or do you have a private plan as well?
Do you have enough coverage?
Does your plan fit into your budget, or could you be saving more money?
Are all of your doctors and prescriptions covered by your current plan?
Ask yourself these questions and take notes, because there may be something better out there.
Notate your Life Changes.
Did you start seeing a new doctor this year, or do you have a problem with your current doctor? Not all plans accept the same doctors, so make sure you’re documenting your current physicians so you can easily confirm they are in network with any potential plans you’re considering for the new year.
Did you gain or lose a job, or suddenly develop financial stress? There are multiple ways to manage your Medicare based on a budget and a licensed agent can walk you through the options you may qualify for.
Were you diagnosed with a new health condition that requires expensive treatments? Some plans are specifically designed for certain chronic conditions.
Think about not only your past year but what you expect to happen over the next year. Think about what type of coverage you might need to get yourself through it all.
See What Medicare Plans are Available in 2027
Every year, new Medicare plans may come to the market, and old plans may change what they are offering. It’s important to look at the new information instead of just assuming that your old plan will stay the same. If your plan does change what they are offering, you will be notified – but it is important to look at other changes in your area as well.
Maybe there’s a great new doctor you’ve wanted to see, but she doesn’t accept your current plan! Or, maybe you suddenly have access to a plan with a five-star rating, when previously you only had access to four-star plans!
An important thing to note is that new benefits are not available to review and discuss each year until October 1st. You may need to speak with a licensed agent to ensure you’re reviewing the plans for the upcoming benefit year and not mistakenly comparing plan benefits that will ultimately be changing.
Meet with an Insurance Agent.
We know it’s nice to think that you can do it all yourself and that with the internet, you don’t need an insurance agent anymore! But, that’s not always true. The benefits of meeting with a licensed insurance agent are simple: it’s free, it’s easy, and it can’t hurt!
Our agents are licensed and represent a variety of different insurance companies, meaning they are not all biased towards one plan option.
Your plan won’t cost any more money whether you meet with an agent or not, so meeting an agent can only help you. A licensed agent can walk you through everything that is available in your local area and help you select the best option based on your needs. Plus, let us repeat – the meeting is free!
We’re here to help, so we don’t want to only talk about the positives. Here are some things that you should NOT do during the Medicare AEP:
Don’t Jump into a new Medicare Plan Too Fast.
Do you understand how to choose a Medicare plan? Sometimes good deals are tempting, and it’s easy to jump into a shiny new plan because the costs are lower or there’s an added benefit. Make sure you’ve considered everything before you switch because it might not be easy to switch back. Make sure that your doctors work with the new plan, it covers your prescriptions, and there aren’t any hidden costs. Also, make sure the new benefit is something that will actually be useful to you!
Misunderstand Medicare Supplements vs. Medicare Advantage Plans.
Medigap, or Medicare Supplements work differently from Medicare Advantage and other types of Medicare plans. Technically, Medigap enrollment is not limited to the AEP. However, that does not mean that you should just change back and forth between different Medigap plans any time.
If you enroll in Medigap outside of your Initial Enrollment Period (when you first become eligible for and enroll in Medicare), you may be put through an underwriting process and may have higher fees based on your age and any preexisting conditions. Medicare Advantage and Part D plans do NOT take age and preexisting conditions into account, but Medigap plans if you wait too long to enroll.
3. Don’t Avoid Researching Medicare Plan Options.
If you already know the name of a carrier, you might be tempted to go straight to their website and enroll in a plan that looks good online. However, there may be more than one carrier offering plans in your area. So, how do you look at all of them easily?
Start by using a plan comparison tool, like our free Medicare Plan Finder. Then, once you’ve compared a few options, consider taking that research to a licensed agent who can talk to you about what you’re looking at and why the differences matter.
Ready for AEP?
To schedule an appointment with one of our licensed agents, call (833)-567-3163 or click here. We can’t wait to help you get the coverage you deserve!
Does Medicare Cover Orthotics?
Medicare is a great resource for eligible beneficiaries to help pay for medical expenses. Orthopedic care can come with a hefty cost, and you may want to know, “Does Medicare cover orthotics”?
Yes, but only if your condition meets certain requirements and plan qualifications.
You can quickly and confidentially shop plans here.
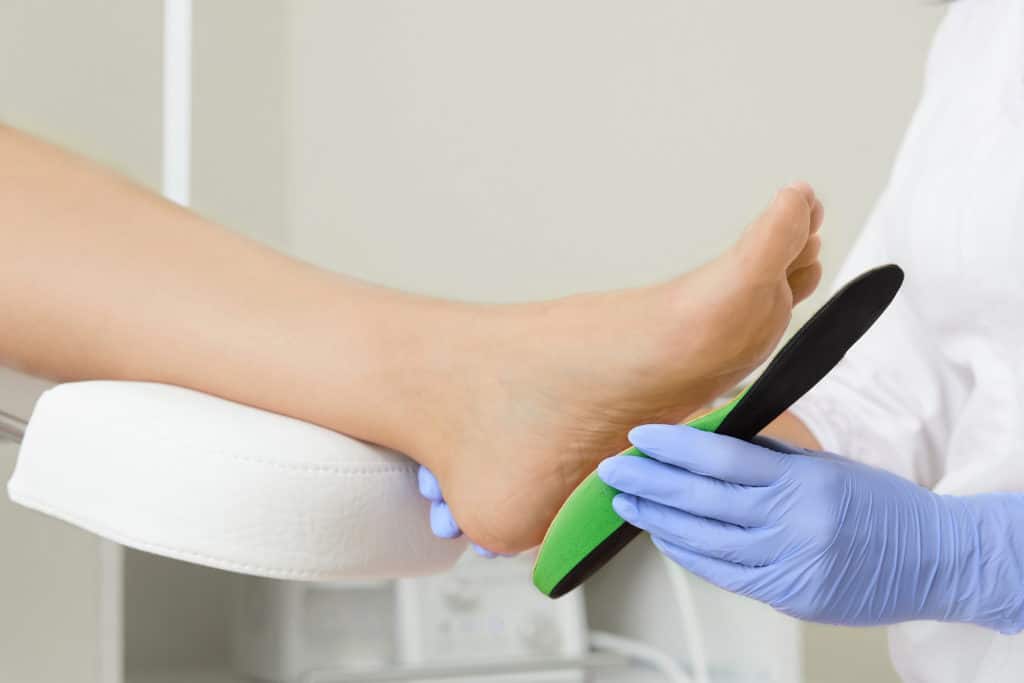
When you have foot problems, it may seem like every little movement you make causes excruciating pain. Even standing still can be difficult. Orthotics can provide relief for people experiencing orthopedic problems such as osteoarthritis, foot pain, or back pain.
Does Medicare Cover Orthotic Shoes or Inserts?
Does Medicare Cover Orthotics? | Medicare Plan Finder
Orthotic shoes are custom-fitted footwear designed to reduce the patient’s pain for a variety of health conditions including:
Metatarsalgia: chronic pain in the ball of the foot
Plantar fasciitis: chronic breakdown of soft tissue around the heel
Bunions: a painful, bony bump on the outside of the big toe
For the most part, Medicare does not cover orthopedic or inserts or shoes, however, Medicare will make exceptions for certain diabetic patients because of the poor circulation or neuropathy that goes with diabetes.
Medicare may cover the fit and cost of one pair of custom-fitted orthopedic shoes and inserts once per year for those patients.
How Much Does Medicare Pay for Orthotic Services?
Podiatrists are doctors who specialize in the feet and ankles, and they prescribe and design medically orthotic devices. Orthopedic devices as part of a leg brace fall under Medicare’s guidelines for durable medical equipment (DME).
In order for Medicare to cover orthotics, your doctor must first determine that orthopedic care is medically necessary. Medicare Part B may cover about 80 percent of the Medicare-approved cost, and you may have to pay the remaining co-insurance. The company that supplies your DME must be Medicare-approved.
Does Medicare Cover Orthotics for Plantar Fasciitis?
Plantar fasciitis, also called “Policeman’s Heel,” is an often self-treatable and diagnosable ailment involving inflamed tissue on the bottom of the foot. You may feel stabbing pain near your heel. It can usually be treated with physical therapy, shoe inserts, steroid injections, and surgery in some cases.
Podiatrists often prescribe treatment for plantar fasciitis. If your doctor is able to prove that it is medically necessary and the prescription is required, you may be able to get coverage at the Medicare-approved amount. Additionally, there may be some Medicare Advantage plans in your area that provide coverage for orthotics for plantar fasciitis.
Does Medicare Cover Orthotics for Weight Loss?
According to the Hospital for Special Surgery (HSS), orthotics can help ease the extra stress on the feet for overweight people. Medicare does not cover orthotics for people who are overweight just because they are overweight.
Medicare may cover weight loss services such as surgery and/or nutrition counseling for people who qualify. Some Medicare Advantage plans even cover fitness programs!
You may also be able to get over-the-counter benefits with some Medicare Advantage plans. So, even though you may not qualify for prescription orthotic coverage, you may be able to find coverage for over-the-counter products you can find at your local drugstore or mail-order pharmacy.
Does Medicare Cover Orthotics After Hip Replacement Surgery
Sometimes doctors prescribe hip braces as a part of hip replacement surgery recovery. However, hip braces oftentimes don’t include a foot orthotic device. Medicare may help pay for the hip brace as part of your DME coverage, but coverage may not include an orthotic device.
According to Dr. James P. Ioli, DPM, a podiatrist with the Harvard Medical School, you should have a physical therapist assess your “pelvic, hip, knee, ankle, and foot movement” to examine how your “soft tissue restrictions [muscle and cartilage stiffness]” and flexibility contributes to your pain. The physical therapist can address your pain and make recommendations to manage it.
Does Medicare Cover Transportation for Orthotics Appointments?
Medicare may cover non-emergency medical transportation in an ambulance if you have a doctor’s note detailing why an ambulance is medically necessary.
If you don’t need an ambulance, some Medicare Advantage plans cover non-emergency medical transportation to doctor’s appointments, to the hospital, and to the pharmacy. Contact your agent to learn more about Medicare Advantage supplemental benefits.
Does Medicare Cover Podiatry?
Does Medicare Cover Orthotics? | Medicare Plan Finder
While Medicare will only cover orthotics if they’re part of a leg brace or for diabetes, Medicare will cover treatment for the following conditions:
Morton’s Neuroma
Morton’s Neuroma is irritation of nerves in the toe. One common sign of Morton’s Neuroma is numbness, and podiatric treatment for Morton’s neuroma includes using a metatarsal pad, cortisone injections and surgery in some extreme cases.
Plantar Fasciitis
Plantar Fasciitis is when the plantar fascia tears. The breakdown causes severe pain with standing and walking. Patients usually experience the most pain first thing in the morning because the calf and foot muscles tighten up overnight.
Plantar Fasciitis treatment includes physical therapy for proper stretching exercises, wearing a splint at night and cortisone injections. If pain becomes severe, a podiatrist might recommend surgery.
Bunions
The pain and stiffness associated with bunions usually worsen gradually. Podiatrists normally start small with treatment and prescribe bunion pads, toe spacers or shoe inserts. If those items fail, the podiatrist may recommend surgery.
Stress Fractures
Stress fractures occur after repeated blows to an area cause tiny fractures. Common causes of stress fractures include walking, running, frequent jumping and playing sports.
Most stress fractures will heal on their own after the patient walks with crutches or uses a walking boot. In some severe cases, the fracture won’t heal because it’s in a complex foot bone, and surgery will be the only course of action to correct it.
Peripheral Neuropathy
Peripheral Neuropathy is caused by nerve damage. The damaged nerves are unable to send the proper messages from the central nervous system to the rest of the body.
Peripheral Neuropathy causes the patient to experience pain, burning sensations, numbness, tingling, and weakness. Common Peripheral Neuropathy causes include:
Peripheral Neuropathy has no cure, and treatment only relieves the patient’s symptoms. The most common treatment for neuropathic pain is prescription drugs, but also topical creams, gels, and patches. In some cases, a cortisone sympathetic nerve block can provide temporary pain relief.
Medicare will only cover your treatment if your podiatrist says it’s medically necessary. Medicare Part B may cover 80% of the Medicare-approved costs. You will be responsible for the Medicare Part B deductible in order for Medicare to cover podiatry.
Podiatric Care Not Covered by Medicare
Medicare does not cover routine podiatry services, because CMS doesn’t consider them to be medically necessary. Some of those treatments and services include:
Trimming toenails
Foot cleaning and soaking
Removing corns and calluses
Treatment for flat feet
Get Medicare Coverage for Orthotics and Podiatry Today
Medicare will only pay for limited podiatric services, and having the right coverage can make all the difference in your quality of care. The licensed agents at Medicare Plan Finder are highly trained and ready to help you find a plan to suit your budget and lifestyle.
This post was originally published on May 28, 2019, and updated on December 11, 2019.
Is Medicare Better Than Individual Plans?
Is Medicare Better Than Individual Plans?
One survey about Medicare satisfaction vs. private insurance satisfaction found that people with Medicare were happier with their health plans than people with individual plans. Will you find the same to be true?
As you turn 65 or otherwise become eligible for Medicare, you probably have a lot of questions. What’s going to change? Will I lose or gain new benefits? The good news is that signing up for Medicare does not necessarily mean giving up your plan flexibility or your favorite doctors. There are plenty of Medicare options available, and we’ll explain why it’s worth it to go ahead and get signed up as soon as you can.
Employer Coverage
You can purchase health insurance through your employer, as long as it meets the coverage limits set by the federal government. If you’re retiring but aren’t eligible for Medicare yet, you can use COBRA to hold you over. COBRA allows you to continue receiving your employer coverage for a short period of time (but your employer likely won’t help you pay for it except for in some unique cases).
You can also technically have Medicare and employer coverage at the same time, if you become eligible for Medicare while you are still employed. That might make sense for some people and not others.
Private Coverage
You can purchase insurance from an exchange like Healthcare.gov, directly from your state, or directly from a health insurance company. Generally, purchasing private insurance is more expensive than employer coverage, and much more expensive than Medicare and Medicaid.
Medicaid
Medicaid is a federal health program. Each state has slightly different rules and each state has its own funding. The program can cover any person of any age with low income (according to the Federal Poverty Level and with some adjustments in each state). Most Medicaid beneficiaries will have either no or very small premiums. If you have a low monthly income AND are over 65, you may qualify for both Medicaid and Medicare! In that case, you can get what is called a “Dual-Eligible Special Needs Plan,” which is low-cost and tailored to your needs.
Medicare
Original Medicare is a federally funded health program that can cover any adult over the age of 65 as well as some adults with disabilities, such as end-stage renal disease.
Most people with Medicare will start with parts A and B. Part A provides hospital coverage, and Medicare Part B provides medical coverage. Anyone who wants more coverage can opt to enroll in either a Medicare Advantage plan or a Medicare Supplement (also called Medigap) plan. Medicare Advantage is sometimes referred to as “Part C” because you have to have Part A and Part B first to enroll in it, and it can cover a lot of services that parts A and B do not.
Unless you enroll in a Medicare Advantage plan that includes prescription drug coverage, you’ll want to enroll in a separate drug plan. These plans are referred to as “Medicare Part D,” because they are completely separate from the other “parts.” Part D plans only cover prescription costs.
Some people may qualify for no or low-cost Medicare coverage, but others will have to pay premiums. Most people will not have to pay nearly as much for Medicare as they would with an individual or private health plan.
You may think that individual plans provide more coverage due to the higher premiums, but that is not always the case. All Medicare plans include preventative services. Plus, you can choose to enroll in Medicare Advantage, which is like a private plan for Medicare. With Medicare Advantage, you can roll all your benefits – medical, dental, vision, prescription drugs, and even fitness – into one convenient plan.
How is Medicare different from other health insurance?
Medicare is vastly different from other health insurance options for a lot of reasons, ranging from the way you pay for your coverage to when you can enroll.
For starters, the Medicare enrollment period is different from the ACA enrollment periods and your employer’s enrollment periods. The Medicare Annual Enrollment Period runs from October 15 through December 7, but be sure to not confuse it with the ACA Open Enrollment Period, which runs from November 1 through December 15 of each year.
Another thing that is different is that some people can have their Medicare Part A payments automatically deducted from their Social Security check.
Employer Health Insurance vs. Medicare Plans
It’s hard to even compare Medicare plans vs. employer health plans because the only thing they have in common is that they provide health insurance. If you’re turning 65 or otherwise preparing to make the switch from your employer plan to Medicare, you should know the pros and cons of each option.
For starters, Original Medicare is the same for everybody. Technically, there are not separate plans to choose from within the government Medicare program. Once you’ve enrolled in Original Medicare, you can decide to add coverage through a private Medicare Advantage or Medicare Supplement plan. Some people may see this as a great thing because you can enroll right away without stressing about all your options. Others don’t like it, because one plan clearly cannot work for everybody. However, that’s what the private plans are for (and many of them are incredibly cheap compared to employer plans – some even have $0 premiums).
The advantage of private health insurance for Medicare (Medicare Advantage or Medicare Supplement) is that you can pick and choose which benefits are most important to you so that you aren’t paying for coverage that you don’t need. Plus, some people will qualify for Medicare Special Needs Plans which are specifically designed for people with special financial or medical needs and are usually relatively low-cost plans. Private Medicare plans can closely resemble individual marketplace plans or employer plans.
The disadvantages of private health insurance for Medicare-eligible people are that they sometimes have limited doctor networks and that some areas might have a limited number of plans to choose from. Typically, people who live in rural areas may have fewer plan options when it comes to private Medicare coverage.
Medicare vs. Medicaid
Both Medicare and Medicaid are government programs that are regulated by CMS (Centers for Medicare and Medicaid Services). They both provide health insurance for medically necessary services.
The main difference between Medicare and Medicaid is who qualifies. It is possible to qualify for both programs, but Medicaid qualifications are based on income while Medicare qualifications are based on age and disability. Another difference is that while the Medicare qualification rules are federal, Medicaid qualification rules can change slightly by state.
Medicare Versus Spouse Insurance
A lot of people who are newly qualified for Medicare wonder if it might be better to stay on their spouse’s insurance plan. The fact is, it depends on how good your spouse’s insurance is. However, if you do qualify for Medicare, Part A (the part that covers hospital costs) has a $0 premium for anyone who has worked and paid Medicare taxes for at least ten years. If you haven’t worked that long but your spouse has, you might still qualify. If that’s the case, there’s no reason not to go ahead and enroll in Medicare Part A as soon as you become eligible.
Additionally, if you wait too long to seek out further Medicare coverage, your costs may go up. You can be charged a penalty of up to 10% of your premium if you don’t enroll in Medicare Part B when you first become eligible. Plus, Medicare Supplement plans can charge more or deny coverage based on preexisting conditions if you wait too long to enroll. So if you think you might want to enroll in a Medicare Supplement plan, don’t wait too long to start looking.
Medicare vs Other Health Insurance: The Benefits
If you are eligible for Medicare coverage but considering alternative health insurance, you should start by learning what Medicare does and does not cover. Medicare Part A and Part B are the same for all who enroll. They cover preventative healthcare, like your annual wellness visits and flu shots at 100%.
Part A also covers 60 consecutive hospital days at 100%. After the 60th day, you’ll start to owe co-payments. Part B covers mental health, lab tests and X-rays, emergency transportation, and medical equipment.
Medicare A and B do not include prescription drug coverage, dental, vision, hearing, podiatry, or any service that is not deemed medically necessary either for treatment or prevention. For additional health coverage, millions of Medicare beneficiaries enroll in Medicare Advantage.
Since Medicare Advantage plans are owned by private companies, they can add in benefits like dental, vision, hearing, etc. – any of those extra benefits that you might be accustomed to from having private health insurance. Some Medicare Advantage plans also cover prescriptions. If you want prescription coverage but don’t care about all of the extra benefits, you can enroll in a stand-alone prescription drug plan instead. However, you cannot have both a Medicare Advantage plan and a Medicare prescription drug plan at the same time, so choose wisely.
The Costs of Medicare vs Other Health Insurance
The good news about Medicare is that as long as you or your spouse have worked and paid Medicare taxes for a certain number of years, your Part A Medicare costs will be low.
If you or your spouse has worked and paid Medicare taxes for at least 40 quarters, you’ll owe $0 in Part A premiums.
If you or your spouse has worked and paid Medicare taxes for less than 30 quarters, you’ll owe $600/month in 2027 in Part A premiums.
Part B premiums are standard for all Medicare beneficiaries. It can change each year, but the Part B monthly premium in 2027 is $209.50, and the deductible is $292. Most services that Part B covers are covered at 80%, so you may owe 20% coinsurance or doctor co-payments.
If you choose to enroll in a prescription drug plan, a Medicare Advantage plan, or a Medicare Supplement plan, you may face an additional premium.
Medicare vs. Private Insurance Costs
If you’re choosing between enrolling in Medicare Part B versus private insurance, remember that delaying your Part B enrollment can leave you with up to a 10% increase in your premium when you do decide to enroll.
If you decide to add on private Medicare insurance through a Medicare Advantage or Medigap plan, remember that you’ll still have to pay your Medicare Part A and B monthly premiums (unless you qualify for a savings program such as QMB). You cannot enroll in Medicare Advantage without enrolling in Medicare parts A and B first.
Medicare Advantage and Medicare Supplement plans are completely separate and therefore come with separate bills. You’ll owe a premium (which in some cases can be $0), and you’ll likely have a deductible as well as co-payments for certain services.
Many private health insurance plans also have out-of-pocket maximums, which means that if you have a lot of health care costs, you can reach a point where you stop having to pay out-of-pocket for services. Those out-of-pocket expenses can really start to add up even with Medicare if you’re someone who needs a lot of medical care!
Why is Medicare cheaper than private insurance?
A lot of new Medicare beneficiaries do find that their Medicare costs are cheaper than what they were paying before they qualified. The biggest reason for that is the way Medicare is funded. While you or your spouse were working hard for all those years, you were paying Medicare taxes. Your low premiums today are because of all that hard work! Plus, the Medicare office does not incur nearly the same amount of administrative costs that many healthcare companies do.
Is it better to have Medicare or private insurance?
Is Medicare a good insurance option? Is private health insurance better? It depends on who you ask. This is a great question to ask an insurance agent who knows what sort of medical expenses you have and what your budget is.
The main difference you have to remember when you’re wondering if private insurance or Medicare is better is that private insurance gives you more plan options. To get a private Medicare Advantage plan, you’ll have to enroll in Medicare A and B, first. Then, you can choose if you want to personalize your coverage and add benefits by enrolling in additional medical insurance.
If you’re stuck between Medicare and keeping your employer plan, remember that you could face penalties if you don’t enroll in Medicare when you first become eligible – and nothing says you can’t keep both!
Is Medicare or private insurance better for people with dependents?
If you have dependents, Medicare isn’t going to help you. But that doesn’t mean you shouldn’t enroll. Medicare only provides individual coverage – there are no family plans or spouse Medicare plans. However, your Medicare Part A might be free. If that’s the case, you might want to consider enrolling in Medicare for yourself first, and then taking a look at options for your dependents.
If you have access to an employer plan, do the math to figure out if it may be more cost-effective for you to have your group vs. individual Medicare Advantage coverage. In some cases, it might even make sense for you to keep both. If your Medicare Advantage premium is low enough, you can keep that for yourself but also hang onto your group coverage for as long as you can to support your family. An insurance agent can help you figure out what’s best for you.
Can I drop my employer health insurance and go on Medicare?
If you become eligible for Medicare while still receiving employer health insurance, you can and should still enroll in Medicare to avoid penalty fees.
First, find out if you’re currently in one of the Medicare enrollment periods. Medicare open enrollment is different from your employer’s open enrollment period.
If you just became eligible, you’ll have a few months for your “Initial Enrollment Period.” If you’re aging into the program, this period begins three months before your 65 birthday and ends three months after. If you’ve already missed that period, don’t panic – you can enroll for the first time from January 1 through March 31 of each year.
Once you’re enrolled, the “Annual Enrollment Period,” is when you can add or make changes to your Medicare coverage. It runs from 10/15 through 12/7 of each year. This period is not for enrolling in Medicare for the first time – it’s only for adding or making changes to your private Medicare coverage.
According to Medicare.gov, some people will be automatically enrolled in Medicare Part A upon becoming eligible. If you are not automatically enrolled, you can apply for Medicare on the Social Security website.
How Medicare Works with Other Insurance
Millions of Medicare beneficiaries opt to enroll in Medicare Advantage or Medicare Supplements on top of their Medicare coverage. In these cases, the private insurance companies act as the “secondary payers.” Health benefits that Medicare does not cover will be automatically billed to the private company, but anything else will go to Medicare first. If you have both employer insurance and Medicare, Medicare might actually be the secondary payer. Check with your employer or your employer’s health insurance plan to be sure.
Both Medicare and private insurance coverage will have limitations – so having both is a great way to keep yourself and your families financially covered in case of a medical emergency.
How Medicare Plan Finder Can Help You
We specialize in Medicare and serving the underserved senior and Medicare-eligible population. Do you or a loved one need help selecting a Medicare plan that truly helps? Set up a free appointment with one of our licensed agents in your area to get bias-free assistance.
Save Money on Prescription Drugs with Discount Cards
Do you have a high deductible or copayment for prescription drugs? Or maybe you’ve been prescribed a medication that isn’t covered by your insurance? Don’t worry, prescription discount cards could be the budget-friendly solution you need to cut down on costs.
What Are Prescription Discount Cards?
Prescription discount cards are offered through networks designed to help consumers save on medications. These cards are free, easy to use, and widely accepted at thousands of pharmacies nationwide. They can provide significant discounts on both brand-name and generic drugs, even for those without insurance.
Many of the top-rated prescription discount cards can be sent directly to your email or phone for immediate use.
By comparing available options and learning how these programs work, you can maximize your savings and make informed decisions about your prescription costs.
Why Consider Prescription Discount Cards?
Here are some key reasons why prescription discount cards are worth exploring:
Immediate Savings: You could save up to 80% or more on the retail price of prescription medications.
Ease of Use: Present your card at participating pharmacies and instantly access discounts.
Accessibility: These cards are free, require little to no personal information, and are available to everyone.
Versatility: Many programs also offer discounts on pet medications.
How Do They Work?
When you use a prescription discount card, the savings come from negotiated rates between pharmacies and pharmacy benefit managers (PBMs). PBMs act as middlemen, working to secure lower prices on drugs for consumers. This process often results in significant cost differences for the same medication at different pharmacies, so it’s essential to compare prices.
The Truth About Prescription Discount Cards
It’s normal to feel cautious about something that sounds too good to be true, especially when Medicare scams and other healthcare-related frauds are on the rise. Here’s how to identify legitimate prescription discount cards:
Clear Pricing Tools: Legitimate programs let you compare drug prices for both brand-name and generic medications online.
Pharmacy Acceptance: Ensure the card is accepted at your preferred pharmacies.
No Strings Attached: Reliable programs don’t require you to provide sensitive personal information.
Transparency: Discounts are consistent and comparable to other trusted programs.
Best Prescription Discount Cards in 2027
Not all prescription discount cards are created equal. Some may offer greater savings on specific medications or have more participating pharmacies in their network. Here are some of the top options to consider:
1. GoodRx
GoodRx is one of the most popular discount programs, allowing you to compare prices across 70,000+ pharmacies in real-time. The app provides coupons that can save you up to 80% on medications. Simply print, email, or text the coupon to yourself and present it at the pharmacy.
2. SingleCare
SingleCare offers a free prescription discount card that works at major pharmacies like CVS, Walmart, and Walgreens. Discounts can be as high as 80%. The program is user-friendly and doesn’t require personal information.
3. US Pharmacy Card
This free card is accepted at more than 59,000 pharmacies nationwide. It’s especially versatile, offering discounts on pet medications too. Cards can be printed, emailed, or texted directly to you.
4. Discount Drug Network
With potential savings of up to 85%, this card is another great option. It requires minimal information to sign up and offers a robust pricing tool for easy comparisons.
How to Use a Prescription Discount Card
Find a Participating Pharmacy: Popular options like Walmart, Walgreens, CVS, and Rite Aid often honor prescription discount cards.
Present Your Card: Show your card or coupon to the pharmacist when you pick up your prescription.
Compare Prices: Use online tools or mobile apps to compare prices before you head to the pharmacy.
Real-World Example: How Much Can You Save?
Let’s take the example of rosuvastatin (Crestor), one of the most commonly prescribed medications in the U.S.
Retail Price: $161.64 for a 30-day supply of 20 mg tablets (without insurance).
Discounted Price: With GoodRx, you could pay as little as $8.44 at Walmart.
That’s a massive saving of over $150 — just by using a free prescription discount card!
Prescription Discount Cards and Medicare
Navigating Medicare and prescription drug coverage can feel overwhelming. Fortunately, a licensed agent can help you understand your options, whether you’re looking at Part D plans, Medicare Advantage, or supplement plans.
If you’re interested in learning more, schedule a no-cost, no-obligation appointment with one of our licensed agents today. Call us at (833)-567-3163 or fill out our online form.
Final Thoughts
Prescription discount cards can be a game-changer for anyone looking to reduce their medication costs. Whether you’re uninsured, underinsured, or simply looking for a way to save, these programs provide an easy and effective solution.
Take the first step toward savings today. Explore your options, download a card, and start comparing prices at your local pharmacies.
Does Medicare Cover Chiropractic Care?
Many people visit the chiropractor to treat a variety of conditions including back pain and headaches. Chiropractic care may be an alternative to prescription drugs.
The idea is that chiropractic care will treat the root cause of the problem, rather than just treating the symptoms. If you have Medicare insurance, you may want to know, “Does Medicare cover chiropractic care?” Yes, but according to the official notice of Medicare coverage for chiropractic care, Medicare has non-covered, always-covered, and perhaps-covered categories.
So it is only applicable in limited circumstances when chiropractic care treatments meet specific rules.
Medicare Chiropractic Coverage
Medicare will not cover the X-rays, massage therapy, or acupuncture treatments your chiropractor may recommend. However, Medicare does cover chiropractic care (spinal manipulation) to correct subluxations, which describes the condition when one or more spinal vertebrae move out of position.
Original Medicare consists of hospital insurance (Part A) and medical insurance (Part B). Medicare Part B will help pay for chiropractic services if your doctor says they’re medically necessary.
If your chiropractor is Medicare-approved, Part B will pay for 80% of your adjustment. You will still owe 20% coinsurance, and the Part B deductible applies.
Original Medicare does not cover many services people want. Private insurance plans called Medicare Advantage (MA) plans can offer coverage for additional chiropractic services.
MA plans vary by location and carrier, and choosing a plan may seem overwhelming. A licensed agent with Medicare Plan Finder can help you find a health insurance plan in your area that fits your needs.
Here is how Medicare Part A, B, C, and D apply to Chiropractic coverage:
Medicare Part A will not cover a visit to a chiropractor because it only applies to hospital care. Chiropractic care is classified as a non-emergency medical service provided in a chiropractic doctor’s office.
Medicare Part B covers manipulation of the spine if a chiropractor believes treatment of a subluxation, which is a misalignment of the spine, to be medically necessary. Part B also provides coverage for physical therapy, since this is another outpatient treatment.
Medicare Part C, the Medicare Advantage plan part, will also cover medically necessary chiropractic services.
Medicare Part D, the Medicare prescription drug benefit, does not apply to chiropractic care at all because Chiropractors are not typically permitted to prescribe medicines legally.
How Many Chiropractic Treatments Does Medicare Cover?
Medicare provides five paid chiropractic visits annually. This can be arranged by your physician through either the Chronic Disease Management plan (CDM) or the Team Care Arrangement (TCA). Medicare chiropractic coverage will save you more than $250 in your healthcare costs.
How Much Does Chiropractic Care Cost With Medicare?
Medicare beneficiaries are United States residents enrolled in Medicare Part A or Part B benefits, or enrolled in both Part A and Part B. They are entitled to receive most medical services after paying their deductibles and a 20% coinsurance.
As a Medicare beneficiary, several factors affect the exact amount you pay with Medicare, for example:
Your health insurance plan
How much your chiropractor charges
Whether your doctor takes Medicare and accepts the assignment
The type of facility
The location of your test or service
What Leads to the Need for Chiropractic Adjustments?
Chiropractor Explaining X-Ray Results to Man | Medicare Plan Finder
Many common conditions can lead to spinal subluxations. For example, let’s say you bend over to pick something up, and when you stand up, your back doesn’t feel right. It hurts, feels tight, and you can’t stand up straight.
You visit your doctor right away, and your doctor determines that your spine is out of alignment. Your doctor might refer you to a chiropractor.
Before your chiropractor creates a treatment plan you will have X-rays and tests to assess your range of motion.
Improper lifting is one cause of spinal subluxations. Other common causes include:
A vertebra going out of place due to slips, trips or falls
The entire spine slipping out of place because of poor posture
Damage to intervertebral joints (joints between the vertebrae) resulting in joint swelling
Tight back muscles that can move the vertebrae out of place
Why Good Posture Is Important
Many people sit down for 6-8 hours a day, and that sedentary lifestyle may be more dangerous than smoking. You may spend hours looking at your phone or laptop while hunched over. That puts unnecessary strain on your neck.
For every inch that your head strays from its natural position, you put an extra 20-30 pounds of pressure on your neck (according to Rene Cailliet, MD, former Director of the Department of Physical Medicine and Rehabilitation at the University of Southern California).
While you sit, don’t slouch. Sit with a straight back and keep your head squarely above your shoulders. If you sit for an extended period of time, be sure to get up and walk around for a while. Develop healthy habits such as stretching your entire body every day.
Benefits of Chiropractic Care for Seniors and Medicare Eligibles
A Chiropractic Adjustment | Medicare Plan Finder
Even though Medicare does not cover chiropractic care unless it’s part of subluxation correction, you may still benefit from chiropractic care. Along with correcting subluxations, chiropractic care may provide relief from headaches, low back and neck pain, and sciatica.
Headaches
Many people may not want to take prescription drugs for headache relief, and they may want to pursue an approach that doesn’t require an abundance of OTC meds either. Many studies suggest that chiropractic care helps treat both tension and migraine headaches.
Lower Back Pain
Chiropractic treatment may be a cost-effective approach to successfully treating lower back pain. Some patients may find that spinal manipulation is more effective for providing pain relief in the long term.
If your doctor recommends chiropractic care for your lower back pain, then it may be a viable option for relieving pain symptoms.
Sciatica
Sciatica refers to a pinched sciatic nerve. It usually starts with a herniated spinal disk. The pain runs from the base of the spine into your legs, and it can range from a mild ache to severe pain.
Your foot might also go numb or feel weak. According to the European Spine Journal, chiropractic adjustments may be more effective than corticosteroid treatment for sciatica.
Common Chiropractic Care Questions
What chiropractic codes does Medicare cover?
Here are the most common chiropractic codes:
CPT Code 98940 Chiropractic manipulative treatment (CMT); Spinal, 1-2 regions
CPT Code 98941 Chiropractic manipulative treatment (CMT); Spinal, 3-4 regions
CPT Code 98942 Chiropractic manipulative treatment (CMT); Spinal, 5 regions
Does Medicare cover chiropractic care in 2020?
Medicare chiropractic coverage in 2027 continues to cover the Medicare guidelines for chiropractic documentation.
Where can I find the latest Medicare fee schedule for 2027?
Medicare.gov is where you will find all the information you need about Medicare’s chiropractic coverage, including the latest Medicare chiropractic fee schedule.
Does AARP United Healthcare cover chiropractic?
Most plans in the AARP secondary Medicare insurance offer a chiropractic benefit.
Let Us Help You Find Medicare Coverage for Chiropractic Care
If you’re one of the many people who rely on chiropractic care for pain relief, you may want to consider a Medicare Advantage plan to help cover costs.
The licensed agents at Medicare Plan Finder are highly trained and they can help you find a MA plan in your area with additional chiropractic coverage. Call(833)-567-3163 or contact us here to learn more.
Find Medicare Plans | Medicare Plan Finder
This post was originally published on June 24, 2019, and updated on January 15, 2025.