Did you know that you can use your Medicare coverage to fight obesity? Medicare coverage for weight loss can include obesity screenings, obesity counseling sessions, nutritionists, and qualified dietitians. It may even include gym membership discounts. If you think eating well and exercising is too expensive, think again: your Medicare plan can cover it!
Medicare Part B Weight Management Services
Medicare Weight Loss Programs | Medicare Plan Finder
Since obesity is classified as a disease, Medicare Part B covers it like any other ailment. It all starts with your “Welcome to Medicare” annual wellness visit when you first enroll, and it continues with your yearly wellness visits. At your appointments, your doctor should check your height, weight, blood pressure, and BMI – all things that can help your doctor diagnose you with obesity and provide proper treatment. These appointments do not require cost-sharing.
If your doctor considers you at risk for obesity, you may be eligible for preventative counseling and even appointments with a nutritionist. Medicare Part B can cover medically necessary obesity counseling and nutrition therapy.
Obesity commonly leads to heart disease. Medicare Part B covers cardiac rehabilitation (exercise, education, and counseling) for those who have had a heart attack, heart failure, or a related surgery.
Nutritionists & Dietitians
Your doctor may recommend that you see a nutritionist or dietician.
Be careful when choosing a nutritionist or dietitian, because Medicare does not cover all of them. For Part B to cover this service, you must medically require it, and the nutritionist or dietitian must accept Medicare assignment. Medicare only covers trained nutritionists under Part B as MNT (medical nutrition therapy). Any patient who has diabetes, kidney disease, or has had a kidney transplant is eligible based on medical need.
Obesity Screenings & Counseling
As long as you have Medicare Part B and have a BMI (body mass index) of 30 or higher, you are eligible for obesity screenings and counseling. The National Heart, Lung, and Blood Institute has a free BMI calculator on its website, but a doctor’s screening will be much more accurate. Your BMI is the percentage of your bodyweight that is made up of fat. Remember that some fat is healthy – you are not aiming for a BMI of zero. A healthy BMI is between 18 and 25. Lower than 18 is too little, 25-30 is a bit high, and above 30 is obese.
When you do get your free obesity screening, you might consider behavioral counseling for body fat loss. Your primary physician should offer their own obesity counseling. If not, they might recommend another Medicare-covered service.
Gym Memberships
The only true “Medicare weight loss programs” are fitness programs.
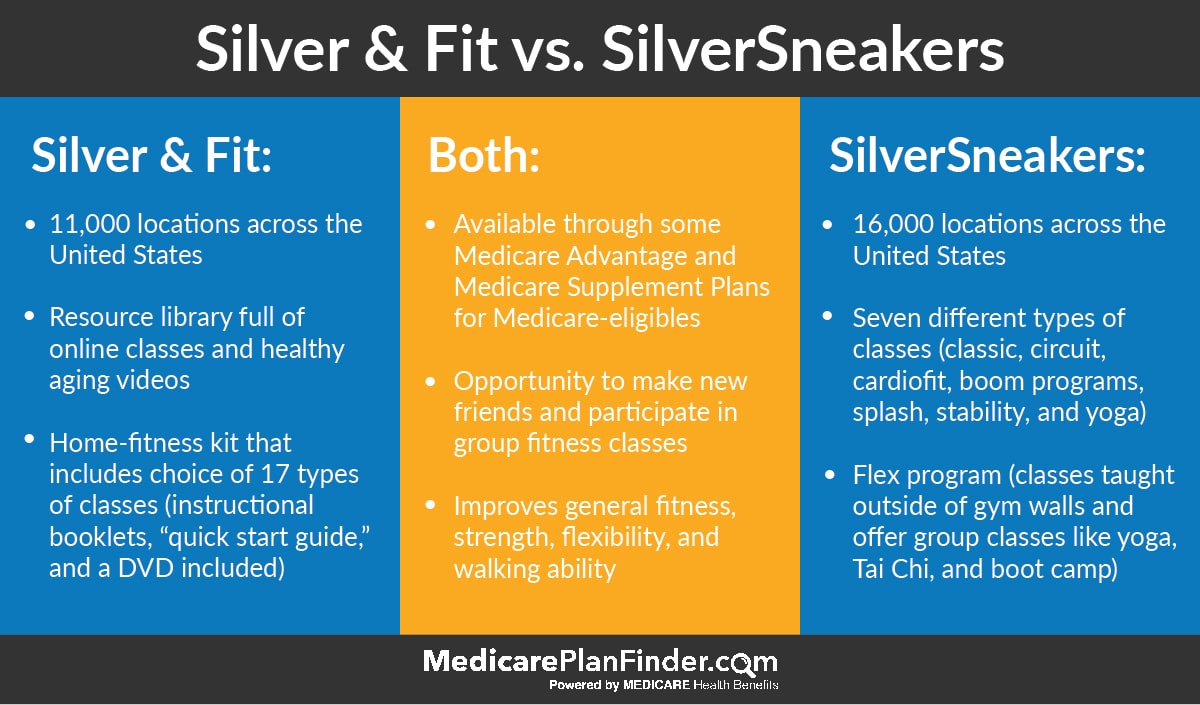
Original Medicare (Part A and Part B) does not cover gym memberships or fitness programs, but private plans may include a gym membership or fitness center discounts. These are usually offered through major Medicare fitness programs such as SilverSneakers® and Silver & Fit®.
Plans with these benefits are not available in every county. Look over your plan or speak with your agent if you aren’t sure about fitness coverage in your Medicare plan.
Obesity Is a Disease
In 2013, the American Medical Association officially started recognizing obesity as a disease. As such, with a BMI of 30 or higher, you can qualify for “obesity behavioral therapy.
The disease affects approximately ⅓ of Americans, and this recognition allows it to be taken more seriously in the medical community and increase research funding. The classification also helps decrease the stigma involved with obesity. It is a commonplace lie that obesity is merely the result of overeating and a lack of exercise. Some people lack the mental strength to control their eating habits and others are incapable of exercising for one reason or another. Saying that obesity is a disease opens the door for obesity counseling and physical therapy as a form of treatment.
Obesity is a common disease in the senior citizen community due to a reduction in physical activity and a lack of access to good nutrition. Additionally, other common senior conditions like heart disease, diabetes, and physical impairments can make it harder to focus on nutrition and exercise. That’s why it’s so important to use your Medicare coverage for healthy eating, exercise, and weight loss.
Does Medicare Cover Weight Loss Surgery/Bariatric Surgery?
Medicare Part B covers bariatric surgeries such as gastric bypass surgery and laparoscopic banding surgery (LAP-BAND). However, you must meet certain criteria. For example, your doctor must determine that Medicare weight-loss surgery is necessary.
Bariatric surgery is a procedure that reduces the amount of food the stomach can hold, effectively forcing you to eat less. However, it is invasive and not recommended for everyone.
Medicare does NOT cover cosmetic surgeries, such as excess skin removal for weight loss surgery.
Types of Bariatric/Weight-Loss Surgeries
The most common bariatric surgeries are a gastric bypass, a sleeve gastrectomy, an adjustable gastric band, and a biliopancreatic diversion with duodenal switch.
Generally, bariatric surgery is recommended for people with:
A gastric bypass is a weight-loss surgery that has been performed for over 50 years, making it the most experienced bariatric operation. In this procedure, a large section of the stomach is stapled off, creating a pouch that connects to the small intestine. The pouch can only hold a few ounces of food, so patients are unable to eat as much as they used to (and won’t feel as hungry).
This procedure requires that patients make major dietary changes. Protein, vitamin B12, iron, and calcium become increasingly important. Sweet and fatty foods must be avoided.
Sleeve Gastrectomy
A sleeve gastrectomy is performed laparoscopically. About 75% of the stomach is removed, causing it to form a “sleeve” shape. This procedure is used for people with a BMI over 40. It often results in 60% weight loss.
A sleeve gastrectomy cannot be reversed. It typically does not have an effect on diet (except for during recovery time).
Adjustable Gastric Band
A laparoscopic gastric banding procedure is the least invasive. A soft, silicone ring with an expandable balloon is implanted at the top of the stomach. It basically creates two compartments for the stomach. The patient will only eat enough food to fill the top part. Over time, the food will pass through into the second (original) compartment of the stomach and will be digested.
This surgery is newer and was not approved until 2001. There may be some long-term complications with this surgery, such as frequent vomiting, implant malposition, erosion, or weight loss failure.
Biliopancreatic Diversion with Duodenal Switch
The duodenal switch procedure starts with a sleeve gastrectomy. Then, the lower intestine is divided, leaving only a few feet of intestine connected to the digestive tract.
This procedure usually results in the greatest weight loss, but patients will likely have frequent and loose bowel movements and gas. Patients will also need to be closely monitored for healthy vitamin, mineral, and protein levels.
In some cases, a doctor or surgeon may recommend that you undergo the sleeve gastrectomy first, then revisit the duodenal switch in 9-12 months.
The duodenal switch often results in 60-80 percent excess weight loss within two years.
Finding a Doctor for Obesity Treatment
Your primary physician can at least help you get started on your obesity treatment but might refer you to a nutritionist or other specialist if necessary.
Be sure to check with your plan network to make sure your doctors and specialists are covered. You can use Medicare.gov’s Physician Finder to find out if a doctor accepts Medicare, and visit your private plan’s website to find out if your doctor or specialist is in your plan’s network.
Are There any Medicare-approved Weight Loss Programs?
Medicare has not formally approved any weight loss programs or fad diets. Speak to your doctor before joining a new program. Here is some information about popular weight loss programs.
Recently, private Medicare Advantage plans have been given the ability to cover more benefits, and dietary programs like this could be one of them. However, it is more common to find Medicare Advantage plans that cover Medicare fitness programs and nutritionists.
Optifast
Optifast is advertised as a “medically-supervised” and “science-based program that delivers weight loss for health gains.” On average, Optifast users ave lost 30 pounds over 26 weeks (which is a healthy ratio). They’ve also seen decreases in blood glucose levels, blood pressure, and cholesterol.
The program provides meal replacements that include 100% of the recommended daily value of 24 different vitamins and minerals. There are five daily servings. Optifast comes in shake mix, bars, soups, and chewable vitamins.
Jenny Craig
The Jenny Craig plan includes a variety of foods and a personal consultant that you can connect with weekly. The meal plans ask you to eat every two to three hours and allow you to mix in your own fresh fruits, vegetables, and dairy. Three entrees and two snacks cost less than $25 per day.
In some areas, you’ll be able to visit and pick up your food from a local weight loss center. Otherwise, you can join Jenny Craig online.
Weight Watchers
Weight Watchers revolutionized fad dieting with their point system.
Each Weight Watchers user will have a unique amount of “points” they are able to use each day. Every piece of food is awarded a point value (though some may be worth 0 points). Your daily point budget is based on your age, height, weight, and sex. Technically, you can eat whatever you want as long as you don’t go above your daily points budget.
Weight Watchers is not very expensive, starting at $3.07 per week for the digital-only plan. You can download the Weight Watchers app and do it all yourself!
What’s nice about the Weight Watchers diet is that you don’t have to eat frozen foods shipped to you, you can keep buying your own groceries and cooking healthy meals. You may even be able to keep enjoying some of your favorite foods, as long as you enjoy them in moderation.
Medicare for Diabetes and Weight Loss
Obesity can put you at a higher risk of developing diabetes. You can use your Medicare coverage to help prevent both obesity AND diabetes.
Medicare Part B covers diabetes self-management training (DSMT), blood sugar monitors, blood test strips, lancets devices, lancets, therapeutic shoes or inserts, and external insulin pumps.*
Additionally, Medicare can cover your participation in the 16-session Diabetes Prevention Program if you:
Have a BMI over 25 (23 if you are Asian)
Have never been diagnosed with either diabetes or ESRD
Have not participated in this program before
Have a hemoglobin A1c test result of 5.7-6.4%, a fasting plasma glucose result of 110-125 mg/dL, or a two-hour plasma glucose result of 140-199 mg/dL (test results must be from the past 12 months)
Medicare Part A covers hospital stays, and Medicare Part B covers physician services. If you are over the age of 65, you automatically qualify for Medicare coverage. You can also qualify by receiving SSDI (Social Security Disability Income) for 25 months or more or by being diagnosed with either ALS (Lou Gehrig’s Disease) or ESRD. Most people will get premium-free Part A but will have to pay a monthly premium for Part B.
To add more to your Medicare plan, the best option is to enroll in a MAPD, or Medicare Advantage Prescription Drug plan. These plans include everything that Part A and Part B covers plus prescription drug coverage and other benefits like dental, vision, and fitness programs like SilverSneakers® and Silver & Fit®.
We have benefits advisors in 50 states that can help you select the best Medicare Advantage Prescription Drug plan for your needs.
Some people may even be able to get a MAPD plan with a $0 premium! To find out more, chat with us, send us a message, or give us a call at (833)-567-3163.
This post was originally posted on June 22, 2017, and was last updated on December 3, 2019.
Dental Vision Hearing Insurance for Seniors and Medicare Beneficiaries
It’s important to always be mindful of your overall health. That includes everything – from the aches and pains you feel to your teeth and your eyesight!
Unfortunately, Original Medicare does not include extensive dental, vision, and hearing insurance for seniors and Medicare beneficiaries. If you are looking for dental, vision, and hearing insurance, you should consider a Medicare Advantage plan.
Original Medicare only includes Part A (hospital coverage) and Part B (doctor coverage), but Medicare Advantage plans, also called Part C, generally include dental benefits, vision benefits, hearing benefits, prescription drug coverage, and more!
Original Medicare covers limited dental, vision, and hearing procedures:
Oral examinations as part of another hospital stay
A jaw disease, oral cancer, face tumor, or face fracture-related procedure
Infections caused by dental procedures
Severe and medically necessary eye procedures and tests such as cataract surgery and corrective lenses following surgery
Macular Degeneration, Glaucoma, and Diabetic Retinopathy tests
Hearing tests that are a part of your primary physician’s routine well-visit
Cochlear implants
Does Medicare pay for hearing aids?
Original Medicare does not cover everything. Medicare Advantage plans can add the following hearing insurance for seniors benefits:
Treatments for hearing problems
Hearing aids
Hearing aid fittings
Hearing aid exams
Hearing tests
Hearing Aid Costs
Medicare Advantage health insurance plans can help cover hearing aid costs associated with fittings, exams, and tests.
Hearing aid costs can range anywhere from $400 to $4,000 per ear. Even if the initial device isn’t too expensive, you may have to pay the costs of a hearing aid fitting, hearing aid exams, and replacement hearing aids every five years or so.
When you add everything together, you could be paying thousands of dollars over your lifetime for your ear care. Luckily, a Medicare Advantage plan is a solution that may help you out financially.
Hearing Aid Brands
When choosing hearing aid brands, details matter! Have an idea of your budget, your ear size, and how you will be using the hearing aid. Will you wear it all day long? Can you afford to splurge a little on your hearing aid?
Some of the most highly-rated hearing aid brands are Phonal, Unitron, Signia, Sonic, and Widex – but be careful! Not all Medicare Advantage plans will cover all hearing aid brands. Be sure to carefully look at the provider network before you select a plan to make sure that hearing aid brands you like are included. Some insurance companies may also give recommendations.
Hearing Aid Types
Just like there are numerous hearing aid brands, there are also numerous hearing aid types. Some of the most common hearing aid types are as follows:
Invisible-In-the-Canal (IIC)
Custom-fitted to your ear canal
Invisible when worn
Great for mild to moderate hearing loss
Completely-In-Canal (CIC)
Custom-fitted to your ear canal
In-The-Canal (ITC)
Custom-made to fit in your ear canal with small portion showing outside of the ear
Great for mild to mildly severe hearing loss
In-The-Ear (ITE)
Custom-made to fit outer portion of your ear
Great for mild to severe hearing loss
Receiver-In-Canal (RIC)
Barely seen when worn
Uses electrical wires instead of a plastic tube
Great for mild to moderate hearing loss
Behind-The-Ear (BTE)
Housed in casing behind the ear
Tube directs sound into earmold fitted inside the ear canal
Great for moderate to severe hearing loss
Medicare Dental Coverage
Original Medicare doesn’t cover everything. Medicare Advantage plans can add the following dental insurance for seniors:
Dental issues caused by another procedure, such as for jaw disease or a kidney transplant
Dentures and denture care
Fillings and extractions
Routine checkups
Does Medicare pay for dentures?
If denture or dental implant coverage is important you, then you should consider a Medicare Advantage plan as dental insurance for seniors.
Medicare Advantage (MA) plans provide Part A (hospital coverage) and Part B (medical coverage) plus additional coverage like prescription drugs, vision, hearing, and dental health!
Most Medicare Advantage dental plans cover dentures and much more — cleanings, x-rays, annual exams, fillings, pullings, and root canals.
Supplemental Dental Insurance for Seniors on Medicare
Seniors and Medicare eligibles may not find the oral health coverage they need with Medicare Advantage or Medicare Supplement plans. For example, a Medicare Advantage plan might cover routine dental services (like preventive care), but not major services like dental implants.
Medicare Supplements (Medigap) are private plans that cover financial items like Original Medicare copays and coinsurance. With a Medicare Supplement plan, you pay a monthly premium and you don’t pay a separate copay or coinsurance when you visit the doctor*.
You cannot have both a Medicare Advantage and a Medicare Supplement plan at the same time. It’s important to know how each type of plan can save you money. Contact your agent to discuss the difference between each type of plan, and ask how you can save money with each. Talk to your agent about your dental care needs, too. Your agent may be able to find a plan in your area that meets your budget needs along with your medical needs.
If you need additional coverage, you may be able to find private dental insurance plans that cover items such as dental implants, cosmetic dentistry, or orthodontics. Private dental plans, like Medicare Advantage plans, may be available as a dental PPO, HMO, or other plan type.
*Plan benefits can vary by plan. Some Medicare Supplements cover copays for doctor’s appointments. Medicare Supplements only help cover Medicare-approved charges.
Dental Discount Plans
Instead of a dental insurance plan, you may be able to find a dental discount plan in your area. With a dental discount plan, you’ll pay an annual fee upfront (instead of a monthly premium). You won’t have copayments, but you’ll have discounted rates on your dental services (if you see a network dentist). You would pay the dentist directly. Talk to your agent about discount plan options.
Medicare Vision Coverage
Original Medicare does not cover everything. Medicare Advantage plans can add the following vision benefits:
Routine eye checkups
Eye exams
Glasses
Contacts
Medicare Eyeglasses Providers
Each Medicare Advantage plan will have its own provider network. That means that not all Medicare eyeglasses providers will accept the plan you choose.
When shopping for a Medicare Advantage plan, you should always look at the provider network and make sure that your favorite doctor or other vision provider accepts the plan you choose.
Medicare Advantage PPO
There are several different types of Medicare Advantage plans. If you’re looking for dental, vision, or hearing insurance for seniors a Medicare Advantage PPO plan is a good way to go. PPOs are one of the most popular types of Medicare Advantage plans.
A Medicare Advantage PPO is ideal because even though there are doctor and pharmacy networks, you can go to other doctors and pharmacies. You may not have as much coverage with out-of-network doctors and pharmacies, but at least you have that option.
You do not need to select one primary care doctor and usually do not need referrals, meaning that if you need to go to a vision specialist, you can technically go to any provider.
Medicare Advantage plans are convenient because all the coverage you need can be rolled into one plan with one monthly premium. Some MA plans even offer low deductibles in exchange for high premiums!
Enroll in Medicare
Are you interested in getting dental, vision and hearing insurance for seniors? A Medicare Advantage plan may be the perfect solution!
Our agents with Medicare Plan Finder can answer any questions you may have and may be able to help you find the best plan for your needs and budget.
If you’re interested in arranging a no-cost, no-obligation appointment, fill out this form or call us at 833-567-3163.
*This post was originally published on March 16, 2017, by Anastasia Iliou. The latest update was on November 26, 2019, by Troy Frink.
Flu vs. Cold: Guide to Causes, Symptoms, and Treatments for Older Adults
The flu and the common cold are both upper respiratory infections that tend to pop up throughout the year (but especially in the colder months). Respiratory illnesses are infections of the body’s respiratory system, which includes the nose, sinuses, mouth, throat, voicebox, windpipe, and lungs. The cold and flu affect the upper respiratory system (nose, sinuses, and throat).
Since these illnesses can be common, it’s easy to ignore the symptoms and to avoid taking preventative measures. It’s also easy to not know whether you have a cold or flu! However, both can have some serious ramifications if not taken seriously! What have you done to protect yourself from the flu and the common cold?
How to Tell the Difference Between Cold and Flu
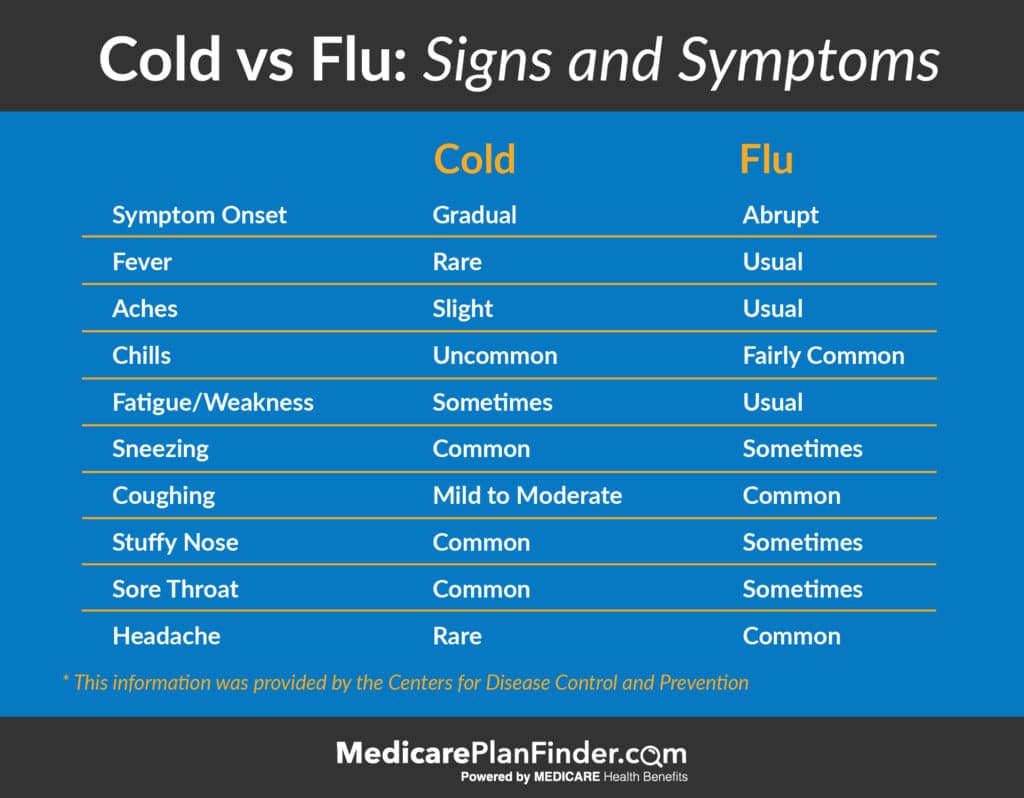
Colds can share symptoms with the flu, making it hard to tell which one you have. It’s important to find out early on whether you have the flu or a cold, because the treatment path may be different. Additionally, the flu can lead to more complications, so it’s better to know as soon as possible if there are other symptoms you need to watch for.
The CDC says that you should see a doctor to be tested for the flu within your first few days of experiencing symptoms. However, there are a few symptom differences you can look for on your own to start with. Mainly, if you have a fever or are experiencing chills, you should definitely see the doctor and find out if you have the flu. Both colds and the flu often come with headaches, fatigue, nasal congestion (runny or stuffy nose), and sometimes body aches or feverish symptoms.
The flu tends to be much more abrupt than a cold; you might feel great one day and awful the next. Most people will also have a fever and chills that last for multiple days with the flu, while a fever is more rare with a cold.
Colds tend to be much milder, so there’s a good chance that once you’ve had a few, you’ll know whether you have the flu or a cold. It’s still always a good idea to check with your doctor if you aren’t sure.
Cold vs. Flu Symptoms | Medicare Plan Finder
Common Cold Symptoms
The common cold can manifest slightly differently in each person. However, common symptoms of a cold are:
Runny nose
Stuffy nose
Sneezing
Nasal congestion
Cough
Sore throat
Mild headaches and body aches
Fatigue
Low-grade fever
You should see a doctor if you aren’t sure whether you have a cold or the flu, but you should definitely see a doctor (visit an urgent care facility if necessary) if you experience shortness of breath, wheezing, severe pain, a fever that lasts more than one day, or any fever that reaches over 101.3 degrees.
Common Cold Virus Name & Causes
The common cold virus is most often caused by either coronaviruses or rhinoviruses. It is uncommon, but possible, for these viruses to cause further damage, such as pneumonia and bronchitis. Further damage is more common with the flu than with the common cold, and is more common in people who already have immune disorders or are affected by other conditions.
Coronaviruses and rhinoviruses can spread through the air when someone who has a virus coughs, sneezes, or even talks. The viruses can enter your body through your mouth, eyes, or nose.
Common Cold Prevention
Since the cold virus spreads through air particles, it can be anywhere. It’s best to always avoid touching your mouth, eyes, or nose without thoroughly washing your hands first. You should also avoid sharing bath towels, food, drinks, and even everyday objects like computer keyboards with someone who is sick.
Sometimes, you may not know that people are sick. That’s why it’s also best to always be cautious in public areas. For example, airports and planes carry a lot of germs, which may be why you find yourself getting sick whenever you travel for the holidays. Believe it or not, USA Today reported that security bins are the most germ-ridden objects in airports. Think about it – is anybody cleaning those trays? Probably not, or at least not very often, yet thousands of travelers touch them and put their objects in them every day.
Always wash your hands after touching public objects, and avoid touching them when you can! Carry hand sanitizer with you for moments when you can’t get to a sink.
You can help keep the cold virus from spreading through your home, office, and any other public area by:
Staying home when you’re sick, if possible
Avoiding hugs, kisses, and handshakes
Coughing into your arm, not your hands
Sneezing into a tissue
Washing your hands immediately after blowing your nose
The cold virus can absolutely be transmitted through food. Whether you’re sharing a disk with someone or coughing over the food you’re serving, your germs can live on your food. In fact, one hospital reported that cold viruses could remain on a surface for as long as seven days.
Head Cold vs. Cold
Some people use the terms “head cold” and “common cold” interchangeably. Realistically, a head cold is a form of the common cold. You could either have a head cold or a chest cold, it just depends on the location of your symptoms. A head cold probably means that you have either a stuffy or runny nose and some congestion along with a fever or a headache. If you have a chest cold, you’re more likely to feel that in your throat, and you might even experience some chest discomfort or wheezing.
Common Cold vs. Sinus Infection
It may be hard to tell whether you have a cold or a sinus infection because the symptoms are generally the same. The only difference is what caused the illness in the first place. While the common cold is a viral infection, a sinus infection is a bacterial infection. You can cure a sinus infection with antibiotics, but antibiotics won’t do much for you if what you have is the common cold. Antibiotics cannot treat a viral infection.
Common Cold Treatment
There is currently no known cure for the common cold because it is a viral infection and not a bacterial one. You should always see a doctor if your symptoms don’t improve or if you don’t know how to treat your illness. Healthline recommends the following treatment plan for the common cold:
Get lots of rest and sleep
Drink plenty of fluids, especially water and natural fruit juices
Use a decongestant or saline spray to loosen up your nasal passages
Sleep with a humidifier to ease congestion
Use over-the-counter pain relievers like ibuprofen for headaches and fevers
Get lots of sleep when you’re sick!
Common Cold Treatment at Home
As long as you are sure that you have a cold and not the flu or a sinus infection, you can treat your cold symptoms at home. Using the suggestions provided by Healthline above and avoiding too much energy exertion may be all you need.
Be sure to stay hydrated and eat healthy foods while you’re recovering (and all the time). If it’s possible to stay home, let yourself relax for a few days.
Common Cold Medicine
Since the common cold is a viral infection, it cannot be treated with antibiotics. However, there are several different medications on the market that can be purchased over-the-counter and can help cure your symptoms.
There may be a better option on your pharmacy shelf, but after researching common cold medicines, we found the following options:
Vicks DayQuil and NyQuil: Relieves headache, fever, sore throat, minor aches and pains, nasal congestion, and cough. The “DayQuil” product is non-drowsy, while the “NyQuil” product may help you sleep at night. Generic versions of these products may be available at your pharmacy.
Mucinex Sinus-Max: Relieves headache, fever, cough, and nasal congestion. Mucinex has a variety of products that you may find in your pharmacy that offer different types of cold symptom relief. Read each box before you make a decision, or ask your pharmacist for help.
Robitussin: Controls and relieves cough and chest congestion and thins and loosens mucus. Has a non-drowsy effect.
Tylenol Cold + Head: Controls and relieves headache, body aches, fever, sore throat, nasal congestion, chest congestion, and mucus. Tylenol also has a series of products that you may want to look at before making a decision.
Some people swear by using ibuprofen products (such as Advil) for treating cold symptoms like headaches and fevers. However, one British study found that ibuprofen is ineffective for sinus pain. You may want to try ibuprofen when you have a cold, but if it doesn’t work and you want to try something else, be sure to wait the appropriate amount of time labeled on the box before putting another medication in your body.
Common Cold Menthol
Menthol is a cooling ingredient found in plants like mint (it even has a mint-like smell). Menthol is used in Vicks VapoRub and in certain cough drops. Menthol can ease breathing and reduce coughs and throat pain.
How to get rid of a Cold in 24 Hours with Quick Common Cold Remedies
Depending on the severity of your cold, you may not be able to completely get rid of it in 24 hours. However, there are certain steps you can take to speed up your recovery time. The more time you spend sleeping and relaxing, the quicker you are likely to recover.
You should also be sure to eat healthy meals like soups and salads, even if you don’t feel hungry. Only drink water, tea, and all-natural juices that are high in antioxidants, like orange juice and cranberry juice.
Influenza, most commonly referred to as “the flu,” can be catastrophic when not handled properly. The flu is different from a cold and is often more severe and abrupt. For instance, most people who have influenza experience a fever. Other symptoms include:
Fever/feverish chills
Cough and sore throat
Runny or stuffy nose
Muscle aches
Headaches
Fatigue
Vomiting
Diarrhea
Even if you do not experience all of those symptoms, it does not mean you don’t have the flu. It’s always a good idea to see your doctor if you aren’t sure.
Flu symptoms in elderly people are generally the same as those in the younger population, but they may be more severe.
Your doctor may or may not perform an official flu test to diagnose you, because whether or not you have the flu may not change your treatment plan. Since the flu (like the common cold) is a viral infection, it cannot be treated with antibiotics.
However, unlike the common cold, the flu can lead to life-threatening illnesses and complications such as pneumonia, sinus infections, ear infections, heart inflammation, muscle inflammation, brain inflammation, and even organ failure. People who have other preexisting conditions such as asthma or heart disease are at a much higher risk of complications.
If you experience any of these more severe symptoms, it is crucial that you get to an urgent care facility or emergency room right away:
Difficulty breathing
Severe chest or abdomen pain
Dizziness or confusion
Seizures
Inability to urinate
Severe muscle or body pain
Severe weakness
High fever
Severe dehydration
Other worsening of chronic conditions
There are technically three different types of the flu virus. Types A and B are what cause the annual influenza outbreak that your doctors want you to get vaccinated for. Type C is generally much less severe. Additionally, type A can affect animals as well as humans (though it is highly unlikely that you and your pets will trade the virus back and forth).
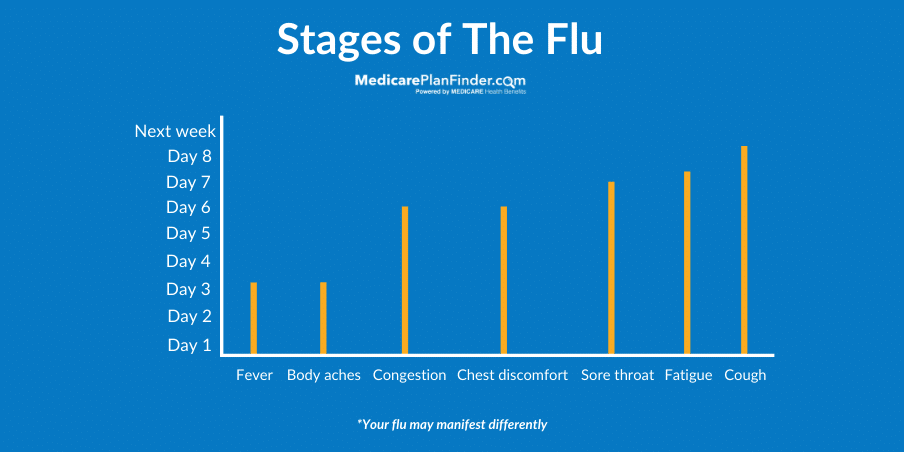
Stages of the Flu
A typical case of influenza will appear as follows:
Days 1-3: Headache, muscle pain, fatigue, cough, sore throat, fever, stuffy nose
Day 4: Fever and muscle aches disappear or decrease, while chest discomfort may increase. Fatigue and congestion may continue.
Day 8: Symptoms overall decline, but fatigue and cough may continue for 1-2 weeks.
When to See a Doctor for the Flu
Without knowing your state of health, we cannot say whether or not you should see a doctor. Some people say that healthy adults really don’t have to see a doctor for the flu at all. However, the earlier you are able to test to find out if you have the flu or a cold, the sooner you can start the appropriate treatment. Plus, if you do have the flu, you can’t get an antiviral prescription without seeing your doctor – and antiviral medications are only effective if you take them within 48 hours of experiencing symptoms.
Flu Treatment for Adults
Similar to the common cold, there is no known cure for the flu. The best way to treat the flu is to treat the symptoms.
Treating flu symptoms in elderly people is not much different than in younger adults or even kids (though kids may need more rest).
The CDC recommends that you stay home for at least 24 hours after your fever is gone (except to seek medical care). You should stay away from others, wash your hands often, cover coughs and sneezes, and even consider wearing a face mask to avoid infecting others.
You should care for yourself by:
Getting plenty of bed rest
Drinking lots of fluids, especially water, tea, and natural fruit juice
Unlike treatment for the common cold, a doctor may prescribe an antiviral medication for flu treatment. These drugs work best when you begin treatment early. They can shorten your illness by about a day and can lessen your symptoms, also reducing the chance of further complications.
Tamiflu
Your doctor might prescribe the antiviral medication called Tamiflu for influenza treatment. Tamiflu is available in both liquid and capsule form and is FDA-approved for all ages (two weeks and older).
Make sure to pay attention to your doctor’s instructions when taking Tamiflu.
Tamiflu is most effective when taken within 48 hours of experiencing flu symptoms. You should take it with food according to your doctor’s instructions. The Tamiflu website suggests that anyone over the age of 13 should take 75mg twice daily for five days. Those under the age of 13 should take one dose based on weight twice daily for five days.
Technically, the Tamiflu website advertises that you can take Tamiflu even without experiencing influenza symptoms if you know you’ve been exposed to the flu (for up to six weeks). That might be a good option for couples living together or parents taking care of a child with the flu virus. In this case, you should only take one dose once daily as long as prescribed.
If you are taking any other medications, be sure to disclose that information to your doctor to make sure there won’t be any negative interactions.
Additionally, make sure that if you do have to take liquid Tamiflu for more than days, it should be stored in the refrigerator. All forms of Tamiflu (liquid or capsule form) should be discarded once you stop needing it.
Flu Medicine OTC
Antiviral medications cannot be purchased over-the-counter, but some OTC cold medicines can treat your flu symptoms the same way that they treat cold symptoms. Look for OTC medications labeled “cold & flu” at your local pharmacy, and ask the pharmacist for help.
The flu virus typically hangs around for about a week, but symptoms can remain for as long as two weeks. People ages 65 and older are more likely to experience complications from the flu than younger adults.
How to Cure Flu Fast
The fastest way to cure the flu is to take care of yourself and take your doctor’s advice. If your doctor prescribes an antiviral medication, be sure to take it as directed. Regardless, be sure to get plenty of sleep and drink extra water to help cure the flu as quickly as possible.
Getting Your Flu Shot
Since people over the age of 65 are more likely to suffer complications from the flu virus, it is very important that you get your flu shot every year.
Flu Shot Dangers in Elderly People
The flu shot has been known to cause some minor side effects such as pain, swelling, or soreness at the injection site, as well as muscle aches and headaches. However, the side effects typically only last for one or two days and are much better than contracting the flu and any resounding complications. Additionally, some people may be allergic to the flu shot. Those who are allergic should speak to their doctor about alternatives and ways to prevent infection.
Does Medicare Cover Flu Shots?
Even if your health insurance doesn’t cover your flu shot, many clinics and pharmacies offer free flu shots or give incentives like $5 gift cards when you get your flu shot.
Original Medicare may be all you need to treat the flu, but a Medicare Supplement plan can help you cover your copayments, and a Medicare Advantage plan can add additional benefits such as non-emergency medical transportation to get you to the doctor and over-the-counter drug coverage to fund your cold medicine.
To speak to a licensed agent about adding Medicare coverage, call (833)-567-3163.
Compare Plans from All Carriers in 1 Minute!
How Does Medicare Cost Sharing Work?
Cost sharing is the reason we have any kind of insurance. In many cases, you don’t pay the full amount of medical expenses if you have health insurance. For example, Original Medicare covers 80 percent of approved costs, and you pay 20 percent. It may sound simple, but it can actually be pretty confusing when you take into account deductibles, copays, coinsurance, out-of-pocket maximums, and premiums.
Medicare Cost Sharing Definitions
Medicare cost sharing may seem more complex than other forms of insurance because Medicare has four different parts, and each one covers something different. Two of those parts are public (Parts A and B), and two are private (Parts C and D).
When you add Medicare Supplements to the mix, things may seem even more confusing. For example, you can’t have both a Medicare Part C plan and a Medicare Supplement plan at the same time. Also, if you have a Medicare Part C (Medicare Advantage) plan, you may not need a Part D (prescription drug) plan because some Medicare Advantage plans cover prescription drugs.
Before we go over what cost sharing looks like for each part of Medicare, we’re going to cover some basic Medicare cost-sharing terminology:
Coinsurance: A percentage of the total cost for medical services. The amount you pay may be different depending on the bill. For example, you may pay 20 percent of the total bill for a doctor visit. If your doctor bills Medicare $100, you’d pay $20.
Copayment: A set amount that you pay for medical services. For example, you may pay $10 upfront for a doctor’s appointment. If your doctor bills Medicare $100, you’d still pay $10 (though you may receive a larger bill for coinsurance later), depending on what your plan pays.
Deductible: The amount you pay out-of-pocket each year before insurance coverage “kicks in.”
Out-of-Pocket Maximum: An overall out-of-pocket spending limit you might have with certain Medicare Advantage plans. Once you reach the maximum, Medicare will cover 100 percent of all approved costs.
Premium: A set amount you pay every month to keep your coverage.
Medicare Part A Cost Sharing
Medicare Part A is hospital insurance and it covers inpatient procedures, hospice care, and skilled nursing facilities. Many Medicare eligibles don’t pay a monthly premium for Part A. If you don’t meet the “premium-free Part A” requirements, you may pay up to $458 per month in 2020.
The 2020 Part A deductible is $1,408. For inpatient hospital or skilled nursing facility stays, you may pay:
Days 1-60: $0 coinsurance
Days 61-90: $352 coinsurance per day in 2020
Days 91 and beyond: $704 coinsurance per day in 2020. You may be able to use “lifetime reserve days,” which are “extra” days Medicare may cover. You may have up to 60 lifetime reserve days. Once you’ve used your lifetime reserve days, you may be responsible for paying 100 percent of hospital services.
Medicare Part B Cost Sharing
Medicare Part B is medical insurance, and it helps pay for outpatient medical services such as doctor’s appointments, emergency medical transportation, outpatient therapy, and durable medical equipment (DME).
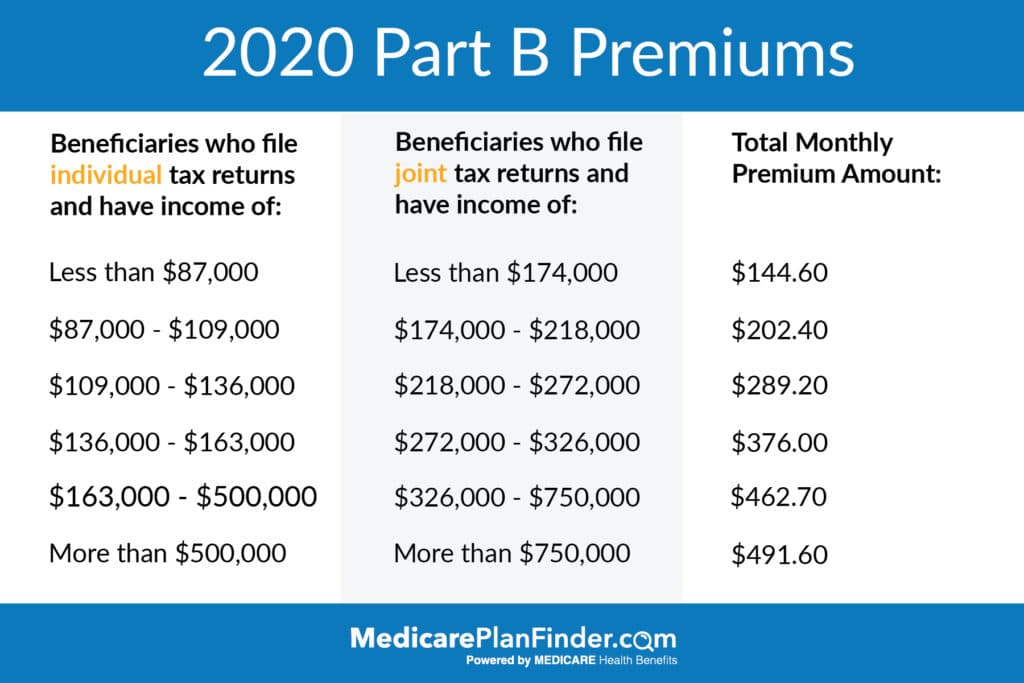
The standard Part B premium is $144.60 in 2020. You may have to pay more depending on your income.
The deductible for Medicare Part B is $198 in 2020. After you meet the deductible, you may pay 20 percent coinsurance of the Medicare-approved total amount.
2020 Medicare Part B Premiums
Medicare Part C Cost Sharing
Medicare Advantage (MA or Part C) are private plans that can cover additional benefits such as prescription drugs, dental, hearing, vision, and fitness classes. You must be enrolled in both Part A and Part B before you can enroll in a MA plan.
Premiums for MA depend on the plan*. They can be as low as $0, but as much as $200. The average premium in 2020 is $23.
Each Medicare Advantage plan may have a different deductible, copay, and/or coinsurance payment. In 2020, the Medicare MOOP (Maximum Out-Of Pocket) spending amount is $6,700**.
Your agent can help you decide if a Medicare Advantage plan is right for you.
*You will still have to pay your Part B premium even if you have a Medicare Advantage plan.
**Medicare MOOP only applies to Original Medicare-covered services. It does not apply to supplemental benefits.
Medicare Part D Cost Sharing
Medicare Part D is prescription drug coverage. You may have to pay a monthly premium, for which the average cost was $33.19 nationwide in 2019.
The 2020 Part D deductible is $435, meaning that Part D plans cannot charge a deductible any higher than that. Many plans may have lower deductibles. Your coverage won’t start until you’ve met your plan’s deductible.
After you meet the deductible, you’ll pay 25 percent of both generic and brand name drug costs. For example, if a prescription drug’s total cost is $40, you’ll pay $10, and your insurance plan will pay the remaining $30.
If your plan requires you to pay a copay or coinsurance, those costs will go toward your TrOOP (True Out-Of Pocket). For example, if your plan requires a $15 copay for a drug, that money will go toward your out-of-pocket limit.
After you pay $6,350, which is the TrOOP threshold, you enter Catastrophic Coverage, and you’ll pay only five percent of your prescription drug costs.
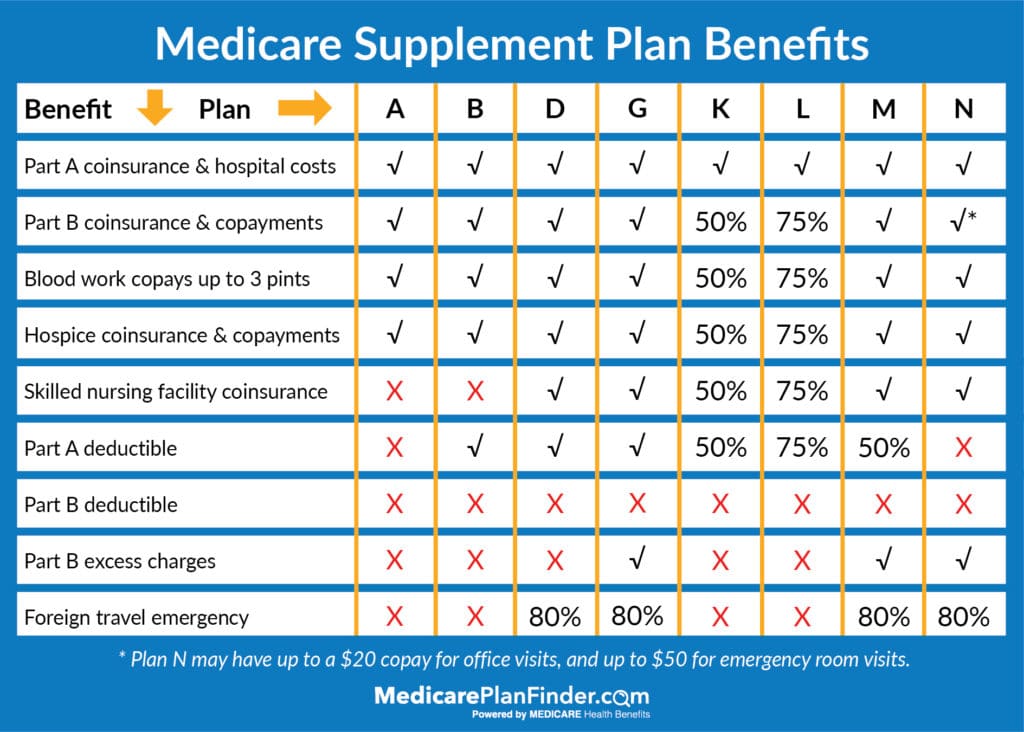
Medicare Supplement (Medigap) plans have a different cost sharing structure than MA plans. Medigap plans have eight standardized coverage levels*. In 2020 there are eight different coverage levels:
2020 Medicare Supplement Comparison Chart
Medicare Supplement plans work like this: You pay a monthly premium** and the plan covers the financial items in the chart above. Medigap plans only cover Medicare-approved costs, not additional benefits like MA plans.
Talk to your agent to discuss your needs and whether a Medigap plan is right for you.
**You will still be responsible for paying Part B premiums with a Medicare Supplement plan.
We Can Help You Navigate Medicare Cost Sharing
Cost sharing with Medicare may seem complicated, and a licensed agent with Medicare Plan Finder can help you determine what you need. Our agents are highly trained, and they can find the Medicare Advantage, Medicare Supplement, and/or Medicare Part D plans in your area. To arrange a no-cost, no-obligation appointment with an agent, call 1-844-431-1832 or contact us here.
FreeStyle Libre Medicare Coverage
FreeStyle Libre is a continuous glucose monitor (CGM) that consists of a small, water-proof, fully disposable sensor that you wear on your arm for 14 days, plus a reader device.
The reader shows your blood glucose levels in real time, and it doesn’t require a finger stick like most CGMs do. FreeStyle Libre is approved for monitoring blood glucose levels in both Type 1 and Type 2 diabetics.
FreeStyle Libre Medicare coverage is much like other Medicare coverage for durable medical equipment (DME). You may have to pay coinsurance or copays, and you have to purchase your DME from a Medicare-approved supplier.
How does FreeStyle Libre Medicare Part B coverage work?
Medicare Part B is medical insurance, and it helps pay for outpatient doctor’s appointments, preventive care such as diabetes screenings, and durable medical equipment (DME). In order for Medicare to approve your DME, your doctor must prescribe it, and it must be a device that will last for three years or more.
You may be responsible for 20 percent of approved Medicare costs for FreeStyle Libre including the equipment itself and your doctor’s supervision.
Medicare Supplement Coverage for FreeStyle Libre
Medicare Supplements (Medigap) plans are private insurance plans that can help pay for expenses that you may incur with Original Medicare (Part A and Part B) such as coinsurance and copays. They work like this: you pay a monthly premium, and your copays and coinsurance, including what you’d pay for durable medical equipment, are covered.
Medicare Advantage FreeStyle Libre Coverage
Medicare Advantage (MA or Part C) plans are also private plans. They work differently than Medigap plans because MA plans offer additional benefits rather than help paying for financial items.
You cannot have both a Medigap plan and a Part C plan, so it’s best to contact your agent to discuss your individual needs, including coverage for diabetes and durable medical equipment.
How much does FreeStyle Libre cost without insurance?
According to GoodRx, FreeStyle Libre can cost about $135 every two weeks. That adds up to $3,510 per year.
Medicare Coverage for Insulin
Original Medicare does not help cover insulin unless it’s in conjunction with an insulin pump. Medicare Part D or certain Medicare Advantage plans may help cover insulin products such as Lantus and Novolin.
According to GoodRx, Lantus is the most popular insulin drug. The average copay is $37.50-$67.50.
Where can I get FreeStyle Libre?
You can get FreeStyle Libre at most major pharmacies, however, Medicare may only cover the device if you get it at a “participating DME supplier.” According to Abbot, the FreeStyle Libre manufacturer, Medicare will help pay for the device if you purchase it from one of the following suppliers:
Advanced Diabetes Supply
Better Living Now
Byram Healthcare
CCS Medical
Diabetes Management & Supplies
Edgepark Medical Supplies
Edwards Health Care Services
HealthLink Solara Medical Supplies
J&B Medical Supply
Mini Pharmacy
United States Medical Supply
In order for Medicare to cover your durable medical equipment, your doctor must say it’s medically necessary. You may need to have periodic follow-up appointments in order for Medicare to continue covering FreeStyle Libre.
How do I use a FreeSyle Libre system?
With the FreeStyle Libre 14-day system, you’ll wear a small sensor on the back of your upper arm that automatically* monitors your glucose 24 hours a day.
Instead of finger pricks**, you simply swipe the reader over the sensor on your arm for a painless, one-second scan. Each scan provides an up-to-the-minute glucose reading, a graph to spot trends, and an eight-hour history of your glucose levels.
*The FreeStyle Libre system requires a one-hour warmup period when you first wear the device before you can check your blood glucose levels.
**You may still have to prick your fingers in certain situations including when your symptoms don’t match your CGM readings and when you suspect that the readings may not be accurate.
Difference Between FreeStyle Libre and Other Constant Glucose Monitors
According to the Diatribe Foundation, a company that distributes information about diabetes, another CGM called the Dexcom G6 received Medicare DME approval in early 2019.
Like Abbot’s FreesStyle Libre, Dexcom’s G6 is covered for people on “intensive insulin therapy like multiple daily injections or use of an insulin pump.”
Both devices feature a smartphone app that you can use to closely monitor your blood glucose and manage your insulin treatment. According to Diatribe, Medicare covers CGM smartphone apps “including sharing features.”
The main differences between FreeStyle Libre and G6 are the “warmup periods” and how long you can wear the devices. FreeStyle Libre features a one-hour warmup period, and you can wear the device for two weeks. The Dexcom G6’s warmup period is two hours, and you can wear the device for 10 days.
Who needs constant glucose monitoring?
Diabetic people need constant glucose monitoring because their bodies can’t produce insulin or efficiently use the insulin it makes. Insulin is a hormone that regulates blood sugar levels.
FreeStyle Libre is best for diabetics who use insulin pumps or need multiple insulin injections per day. According to the Mayo Clinic, if you don’t manage diabetes, it may lead to the following complications:
Along with managing blood glucose levels, a balanced diet such as the Mediterranean diet, exercising regularly, and maintaining a healthy weight may help prevent type 2 diabetes or manage type 1 diabetes symptoms and complications. Work with your doctor to develop a comprehensive treatment plan.
If you have diabetes and you want to learn more about Medicare coverage for FreeStyle Libre, a licensed agent with Medicare Plan Finder can help.
Our agents are highly trained, and they may be able to find plans in your area that cover fitness programs, meal delivery, hearing, and/or routine vision care. To set up a no-cost, no-obligation appointment to discuss your needs, call 1-844-431-1832 or contact us here now.
The Ultimate Guide to Medicare Coverage for Arthritis
Arthritis is an inflammation of the joints. The condition can affect one or more joints, and it can cause pain and stiffness. According to the Centers for Disease Control and Prevention (CDC), approximately 54.4 million adults 18 and older have diagnosed arthritis, and the “prevalence of arthritis increases with age.”
Some types of arthritis may be preventable and the symptoms may be manageable. Medicare may cover different treatments and services for arthritis.
Common Types of Arthritis
There are more than 100 types of arthritis, but the most common types are:
Rheumatoid arthritis is an autoimmune condition in which the immune system attacks your joints and organs. Rheumatoid arthritis has no known cause. According to the Mayo Clinic, your primary care provider may refer you to a rheumatologist if you have the following symptoms:
Tender, warm, and/or swollen joints
Stiff joints that are worse in the morning or periods of inactivity
Inflammation tests such as erythrocyte sedimentation rate (ESR)
Rheumatoid Factor (RF) tests to look for antibodies that indicate rheumatoid arthritis
Imaging tests such as X-Ray, MRI, and Ultrasound to examine joints
Medicare Coverage for Rheumatoid Arthritis
Original Medicare helps cover doctor-recommended diagnostic testing for RA, doctor’s appointments, and some doctor-administered drugs such as disease-modifying antirheumatic drugs (DMARDs). Other covered treatments can include physical therapy, over-the-counter (OTC) drugs such as ibuprofen, and corticosteroids (inflammation relief drugs) such as prednisone. In rare circumstances, your doctor may recommend surgery.
Original Medicare does not cover prescription drugs that you take at home, but Medicare Part D or certain Medicare Advantage plans might.
Medicare Advantage plans are private insurance plans that can cover benefits Original Medicare does not such as meal delivery, OTC drugs, and non-emergency medical transportation.
Osteoarthritis
According to the National Institute of Arthritis and Musculoskeletal and Skin Diseases (NIAMS), osteoarthritis is the most common type of arthritis. The disease causes damage to a joint’s protective cartilage, which wears down over time. Osteoarthritis can affect any joint, but it most commonly occurs in the hands, knees, hips, and spine.
Joint stress caused by repetitive physical activity (sports, active jobs, etc.)
Osteoarthritis can have the following symptoms:
Joint stiffness, especially after sitting for long periods of time
Swelling or tenderness in one or more joints
The feeling of bone on bone, or a “crunching” feeling
Osteoarthritis Treatment and Medicare Coverage
Treatment for osteoarthritis includes over-the-counter drugs such as Tylenol and ibuprofen. Prescription-drug treatment can include antidepressants such as Cymbalta, which can ease arthritis-related pain if OTC drugs don’t work. Medicare Part D and certain Medicare Advantage (MA) plans can cover prescription drugs, and some MA plans may cover OTC drugs.
Non-medication treatments can include physical therapy, occupational therapy, and if the condition becomes severe, surgery such as osteotomy and joint replacement.
Psoriatic Arthritis
Psoriatic arthritis is an autoimmune condition like rheumatoid arthritis. Like rheumatoid arthritis, psoriatic arthritis can cause joint stiffness and pain. According to the Arthritis Foundation, about 30 percent of people who have the skin condition psoriasis also get psoriatic arthritis.
Symptoms of psoriatic arthritis include:
Joint pain and stiffness
Tendon or ligament pain
Rashes or changes to fingernails and toenails
Fatigue
Limited range of motion
Vision problems
Psoriatic arthritis is also linked with irritable bowel syndrome (IBS), Crohn’s disease, and other digestive issues such as diarrhea.
Medicare Coverage for Psoriatic Arthritis
Psoriatic arthritis treatment includes prescription drugs such as DMARDs and corticosteroid injections, and topical treatments such as calcipotriene. Over-the-counter treatments include topical treatments such as salicylic acid gel and NSAIDs.
Fibromyalgia is a condition that causes chronic pain, fatigue, memory problems, and changes in mood. It is not one disease, but a collection of manageable symptoms. The cause is unknown. Symptoms include:
Pain: The most common fibromyalgia symptom is widespread pain in the joints, bones, and muscles.
Fatigue: Many people with fibromyalgia experience exhaustion, flu-like fatigue, and/or disturbances to sleep.
Problems with concentration and mood: Depression is a common symptom of fibromyalgia, along with difficulty concentrating or performing simple mental tasks. Stressful times often exacerbate these symptoms.
Headaches: People with fibromyalgia often experience tension headaches and/or migraines.
Fibromyalgia Treatment
Treatment for fibromyalgia does not cure the condition, but it helps manage symptoms.
According to the Arthritis Foundation, “There are currently three FDA-approved medications for fibromyalgia –– pregabalin, duloxetine and milnacipran.” Some Medicare Part D and Medicare Advantage plans may cover those drugs.
Other treatments can include exercise, acupuncture, and biofeedback, which teaches people how to change physiological functions such as slowing a rapid heart rate.
Gout
According to the Arthritis Foundation, “Gout is a form of inflammatory arthritis that develops in some people who have high levels of uric acid in the blood.” Gout usually starts in the big toe or a joint in the lower body. Gout usually starts after an illness, injury, or infection, and it affects one joint at a time.
Gout Treatment
According to the Arthritis Foundation, gout treatment includes medication and “lifestyle changes.”
Prescription drugs to treat pain and inflammation include colchicine and corticosteroid injections. Drugs to reduce uric acid include Zyloprim and Uloric. OTC medications include NSAIDs.
If you have a gout flare-up, you should take anti-inflammatory medication, ice and elevate the joint, stay hydrated (but not with sugary soda), relax, and ask for help to perform daily tasks.
Get Medicare Coverage for Arthritis Today
If you need help getting Medicare coverage for arthritis, an agent with Medicare Plan Finder can help. Our agents can help determine your budget, lifestyle, and medical needs, and search for a plan in your area that suits you. To set up a no-cost, no-obligation appointment with a licensed agent, call 1-844-431-1832 or contact us here today.
Does Medicare Cover Hospice Care?
More than 1.7 million Americans use hospice each year to maintain or improve their quality of life due to a terminal illness. Hospice care plans address physical, emotional, and spiritual pain and offer support to caregivers during the grieving process.
Hospice decisions can take an emotional and financial toll on you and your family, so you may be asking… “Does Medicare cover hospice?”
How does Medicare cover hospice care?
If you are enrolled in Medicare Part A (hospital insurance), you may qualify for hospice care. However, you must meet the following criteria:
Your doctor certifies that you are terminally ill (with a life expectancy of less than 6 months)
You accept palliative care (for comfort) rather than try to cure your condition
You sign an agreement choosing hospice care over other Medicare-covered benefits to treat your illness
You are not eligible if you had already made a hospice election or have not previously received pre-election hospice services (evaluation of your need for pain and symptom management).
If you meet the above criteria, the following services may be part of your hospice care plan and are covered in part by Medicare:
Other services focused on pain and symptom management
There may be a co-payment of $5 for your prescription drugs or other pain relief. You may also need to pay five percent of the Medicare-approved amount for respite care. However, the following services are not covered by Medicare:
Hospice is intended for people who have six months or less to live. To receive hospice care, you can not receive curative treatment.
If you decide to receive treatment, your hospice care is no longer covered. However, you can withdraw from your hospice care at any given point, and you can resume treatment as long as you are still eligible.
Prescription Drugs Intended to Cure
Just like you can’t pursue curative treatment, you can not take prescription drugs that are intended to cure your illness when receiving hospice care. Hospice only covers drugs that are intended for pain relief and control.
Care for Any Hospice Provider That Wasn’t Arranged by the Hospice Team
You are only eligible to receive care from the hospice team that you initially select.
You cannot get hospice coverage from a different provider unless you go through the switching process. However, you can still visit your regular doctor if they have been appointed to supervise your hospice care plan.
You can only switch to a different hospice provider once per benefit period. If you are interested in switching, be sure to do your research and pick a hospice team you feel comfortable with.
Does Medicare cover hospice room and board?
Medicare does not cover room and board regardless if you live at home, in a nursing home or inpatient assisted living facility, or inpatient hospice office. The only exception is during short-term inpatient or respite care stays in which Medicare will help cover the costs.
Emergency Care
Emergency transportation is not covered by Medicare’s hospice benefits. Medicare will not cover emergency inpatient hospital care unless they are arranged by your hospice team or unrelated to your terminal illness.
Does Medicare cover hospice in a nursing home or at home?
If you are eligible, Medicare will cover hospice care regardless if you receive the care in your home, nursing home, or inpatient facility. Some nursing homes work directly with a hospice team. In a nursing home setting, your hospice team can help with the following:
Regular visits to the nursing home
Consultations by specialized hospice physician as needed
Pain and medication management
Educating staff on symptoms, medications, and care
Emotional and spiritual support
Coordinating care across all patient’s medical providers including doctors, hospice team, and nursing home staff
How long will Medicare pay for hospice care?
Hospice care is intended for people who have less than an estimated six months to live. If you still require hospice care after six months, you can continue to receive benefits if a hospice doctor recertifies your terminal illness in a face-to-face meeting.
You can get hospice care for two 90-day benefit periods followed by an unlimited number of 60-day benefit periods.
Level One: This level includes basic care under Medicare’s hospice benefit. Services include nursing services, medical equipment & supplies, and medications.
Level Two: Medicare designates people who need continuous care such as home health care. The home health aide stays in the patient’s home for eight to 24 hours a day, but it’s short-term care. The patient’s needs are re-evaluated once every 24 hours.
Level Three: The third level of Medicare hospice coverage is general inpatient care. Some people have short-term symptoms that are so severe that they can’t get adequate treatment at home. With level three care, the patient has 24-hour care available.
Level Four: This level of care is more for the family than the patient. If the patient doesn’t meet the criteria for inpatient care and the family needs a break from daily care duties, respite care may be an option. Respite care provides caregivers temporary relief by admitting the patient to a hospital.
Medicare Palliative Care vs. Medicare Hospice Care Coverage
Medicare can cover palliative care for helping relieve symptoms in accordance with curative care. Some organizations define palliative care as “specialized medical care for people living with a serious illness” with the focus of care being symptom relief rather than to find a cure.
The difference between palliative care and hospice care is that palliative care can occur in conjunction with curative care.
Medicare may cover palliative care, but not under the Medicare hospice benefit.
Hospice and Medicare Supplements
Medicare Supplements can help cover the gaps in hospice care that Original Medicare may not, like prescription drugs for pain relief and respite care. After your Medicare coverage, you will likely be responsible for five percent of your total respite care costs and a $5 copay per prescription drug. Medicare Supplements can cover some, or all, of these gaps.
Medicare Supplement Plans A, B, D, G, M, N cover 100 percent of hospice coinsurance and copayments. Medigap Plan K covers 50 percent and Plan L covers 75 percent.
If you are interested in enrolling in a Medicare Supplement plan, or have questions on how these plans work with your correct coverage, click here to get in contact with a licensed agent.
2020 Medicare Supplement Comparison Chart
Hospice and Medicare Advantage
If you enroll in a Medicare Advantage plan, you will have the same hospice care coverage as with Original Medicare. However, Medicare Advantage plans can offer extra benefits like vision, hearing, and dental coverage. They may also offer fitness programs like SilverSneakers®.
If you are interested in enrolling in a Medicare Advantage plan, fill out this form, or give us a call at 844-431-1832. There is no cost to you to meet with one of our agents and there is never an obligation to enroll.
This post was originally published on April 16, 2019, and updated on November 18, 2019.
Those golden years have arrived. If you’re lucky, retirement is just around the corner. Before you retire, you need to make the following important considerations:
Setting a retirement date
Making withdrawals from retirement accounts
Receiving Social Security benefits
Enrolling in Medicare
Writing a will
Paying for your final expenses
Retired couple dancing on the beach
Setting a Retirement Date
While you may have been eager for your retirement to start as soon as you began working, you need to consider your financial situation before you retire.
Take a look at your savings account and your retirement accounts. Think about how much your Social Security benefits will be. If you have a health savings account, also consider those numbers.
Determine your living expenses, health expenses, and the costs of your other retirement dreams.
Go over your available funds and expenses with a financial adviser to estimate how much you need to take care of yourself during retirement and compare those numbers with what you have in your retirement accounts and what you can receive from Social Security.
Making Withdrawals From Retirement Accounts
When you start planning withdrawals from your retirement accounts, you need to understand how taxes work on them and what the age requirements are.
Some retirement accounts, like 401(k)s, are tax-deferred accounts, which means that you’ll owe taxes on what you withdraw.
Other retirement accounts, like Roth IRAs, are made of taxed income. Since these funds were already taxed before growing in the account, they are not taxed when you make withdrawals.
Understanding how taxes work for your retirement accounts will help you plan your withdrawals and anticipate your taxes each year.
You can start making withdrawals without penalties from your retirement accounts at age 59 and a half.
Meet with a financial planner or advisor to review the specifics of your situation and discuss the best option for planning your withdrawals. In some cases, making some withdrawals before the first required minimum distribution may help with tax-planning.
Financial advisor shaking hands with senior woman in living room
Receiving Social Security Benefits
You should also discuss Social Security retirement benefits with a financial advisor. You can start receiving benefits as early as age 62, but the benefit amount may be lower than it could be because you’re receiving the benefit early.
Deciding when to start receiving Social Security retirement benefits depends on your situation, including how long you want to work, your financials, and your health. Whenever you decide to start receiving Social Security benefits, be sure to apply four months in advance of that date.
While there are some exceptions that allow you to become eligible for Medicare earlier, you become eligible for Medicare when you turn 65 years old. Your initial enrollment period (IEP) starts three months before your 65th birthday and ends three months after your 65th birthday. If you retire from the railroad, you may automatically be enrolled.
During this first enrollment period, you do not have to worry about passing an underwriting process or being charged more or denied for pre-existing conditions. Take advantage of this time to research your options and make an informed choice.
You can choose to enroll in Parts A and B (Original Medicare) only, or add on either Part C (Medicare Advantage Plan) or D. Original Medicare is run by the government and includes Medicare Part A, hospital insurance, and Medicare Part B, medical insurance. You can visit any doctor in the country who accepts Medicare. Enrollment is managed by Social Security.
If you enroll in Medicare Advantage, you’ll still have A and B, but you may be able to get additional benefits. These plans are managed by private health insurers and are similar to other private health plans. For example, these plans have networks of health care providers. Some also offer dental, hearing, vision, and prescription drug coverage.
As you decide the direction you want to take when you enroll in Medicare, consider Medicare Part D (prescription drug coverage) and Medigap. You cannot have Medicare Advantage, Part D, and Medigap at the same time. You’ll have to choose between Medicare Advantage only, Medigap only, Part D only, or Medigap and Part D.
Part D plans only provide prescription drug coverage. Medigap (or Medicare Supplement) plans help with out-of-pocket expenses (like copayments) from Original Medicare.
If you haven’t written a will yet, now’s a good time to do it. Include your wishes regarding medical treatment if you are on life support or in a coma. The will should also identify someone who will make medical and financial decisions on your behalf if you become unable to make them for yourself.
The rest of your will should set forth how you want your assets distributed. If you do not put your wishes into writing, your assets will be distributed according to state and federal laws.
While it can be intimidating to create a will, it’s important because it will lift decision-making burdens from your children and caretakers. You can use online resources to create your will yourself or go over it with an attorney. Reviewing it with an attorney can help you think through potential scenarios and plan for them.
Paying for Your Final Expenses
You also need to consider how your funeral and final costs will be paid. Funerals are expensive. The National Funeral Directors Association (NDFA) found that the median funeral costs with a viewing were $6,260 for cremation and $8,755 for burial in 2017.
If you have enough savings to pay for it yourself, you need to realize that probate will delay your beneficiaries’ access to those funds. Probate is the legal process for reviewing a will or applicable laws and disbursing everything out accordingly.
You do not want to put family and friends in a financial bind when planning your funeral.
You can buy a final expense or burial insurance policy.
If you know where you want to be buried and which funeral home you want to use, then it may be worth pre-paying for your funeral. Choose the funeral home wisely because if you prepay and the funeral home closes, you might be out of luck. You’ll also want to be sure that it’s a reputable funeral home.
Alternatively, you can buy a final expense or burial insurance policy. These policies are designed for seniors and are a kind of permanent life insurance policy. These permanent policies have lower coverage levels because they are meant to cover final expenses and funeral costs.
Once you have all these details taken care of, you’ll be able to stop worrying about problems you may encounter and how you’ll leave your loved ones. You’ll be able to maximize your time enjoying your golden years and cherish moments with family and friends.
Healthy Soups for Seniors
There are thousands of unique soup recipes out there on the internet. While soup may only be as healthy as the ingredients inside it, Eatingwell.com reports that soup-eaters have “higher intakes of fiber, vitamin A, magnesium, iron, and potassium, which are all important for a healthy diet, especially for aging seniors! Soups also tend to be relatively low in calories!
Granted, like everything else, you should enjoy soup in moderation. Soups also tend to be high in sodium, which can raise your blood pressure. The potassium content in many soups can even the sodium out, but it’s still not something you want to over-indulge in.
Healthiest Soups for Seniors
The way you prepare and consume a soup can determine whether or not it’s healthy for you. “Healthy” can also depend on your specific dietary needs.
However, the following soups can be deliciously healthy when prepared correctly!
Broth is made of bones and tissue usually derived from chicken, cows, or even fish. Broth can be rich in vitamins and minerals like calcium, magnesium, and phosphorous. MedicalNewsToday says that broth can strengthen your joints, fight osteoarthritis, reduce inflammation, support weight loss, and even aid sleep.
Osteoarthritis is one of the most common forms of arthritis, affecting millions each year. Arthritis can become a legitimate concern. Arthritis happens when your bones wear down from overuse, which can become more possible as you age.
Tomato-based Soups
Tomatoes are loaded with vitamin C and antioxidants and are sometimes considered a superfood. Uniquely, they also contain lycopene, a plant compound that gives tomatoes their red color and has been linked to prostate cancer prevention. Tomatoes are one of the few sources of lycopene. Tomatoes have also been proven to help maintain blood pressure, support heart health, improve insulin levels in diabetic people, reduce constipation, and improve skin and eye health.
Tomato Soup for Seniors
Lentil-based Soups
Lentils are high in fiber and nutrients like vitamin B, iron, magnesium, potassium, and zinc. They also contain phytochemicals, which protect against chronic diseases like heart disease and type 2 diabetes. Again, like everything, it’s important to only enjoy lentils in moderation. Uniquely, they contain “antinutrients,” which can reduce your intake of other nutrients. Thankfully, you would have to eat a lot of lentils for this to pose a real problem!
Healthy Canned Soup
In many cases, canned soups are not going to be nearly as healthy as a fresh, home-made batch. However, sometimes, you just don’t have the time or energy to make yourself some fresh soup! Canned soup can be very cheap at your local grocery store (and even online), and it’s not always terrible for you.
When looking for healthy canned soups, look at the nutrition label and look for low sodium content, less calories, and more vitamins and minerals. Additionally, canned soups tend to have high levels of BPA. Consider looking for soups packaged in “Tetra Pak” or other cardboard/BPA-free solutions.
We found this recipe for split-pea soup that serves six people from Epicurious! You could probably substitute out a different cut of pork (for example, if you have some leftover ham from Thanksgiving, throw that in there)!
Ingredients:
2 tbsp butter
1 chopped large onion
1 cup chopped celery
1 cup chopped peeled carrots
1 ½ pounds smoked pork hocks
2 tsp dried leaf marjoram
1 ½ cups green split peas
8 cups water
Directions:
Melt butter in large pot or dutch oven over medium-high heat
Add onion, celery, and carrots
Saute until vegetables soften (about eight minutes)
Add pork and marjoram; stir for one minute
Add peas, then water; bring to boil
Reduce heat to medium-low and partially cover pot
Simmer until pork and vegetables are tender and peas are falling apart; stir often (about 70 minutes)
Transfer hocks to a bowl
Puree five cups soup in batches in a blender; return to pot
What happens to your health insurance when you retire? Medicare and retirement can seem intimidating, but we’re here to ease some of your concerns and answer your questions.
There are currently an estimated 70 billion baby boomers who are nearing retirement. Planning for retirement is crucial to living a comfortable and healthy life. An annual estimate by Fidelity shows the average couple retiring at age 65 will need $280,000 to cover health-related costs. Fortunately, Medicare can help, but there is a set of guidelines and regulations regarding enrollment.
How Medicare and Retiree Coverage Work Together
Some employers may offer retiree health coverage, which can be a good option if you are not yet 65 and do not meet other Medicare eligibility requirements. If you are 65, it may be time to enroll in Medicare.
If you are already 65 when you retire and are interested in having both retiree coverage from your employer AND Medicare, the two can work together.
Your Medicare coverage will always come first. Your retiree coverage will work as extra coverage to backup your Medicare plan – kind of like a Medicare Supplement plan.
While retiree coverage is not a Medicare Supplement plan, it is very similar. It can cover things like copayments and deductibles, or even extra hospital stay days. All retiree plans are different, though, so look over your plan and call your insurance agent (or your former HR representative) to find out what it covers.
Do Retirees have to Pay for Medicare?
There are two parts to Original Medicare – Part A and B. If you have worked and paid Medicare taxes for at least 40 quarters (about 10 years), you can have premium-free Part A. If you did not work the 40 quarter minimum, then you will have to pay the Part A premium. For 2020, the Part A premium is $458 for 30+ quarters or $252 for 30-39 quarters.
The standard Part B premium for 2020 is $144.60, but you may pay more or less based on your own set of circumstances. An estimated 3.5% of beneficiaries will have a lower premium due to the Social Security “hold harmless” provision which prevents premiums from exceeding Social Security benefits. Plus, if you make more than $87,000 a year, your monthly Part B premium will be adjusted based on your income. The income-based 2019 Part B premiums are as follows:
2020 Medicare Part B Premiums
Do you Automatically get Medicare When you Turn 65?
If you currently receive Social Security benefits, you will be automatically enrolled in Medicare Parts A and B the month you turn 65. However, if you do not receive Social Security benefits, you will need to enroll yourself. Medicare enrollment begins three months before your 65th birthday and will end three months after. This is called your initial enrollment period.
It’s important to act right away because delaying your enrollment can result in a 10% Part B premium increase for every year you’re eligible but don’t enroll. If you don’t select prescription drug coverage and later enroll, you may have a penalty of 1% the national base Medicare Part D monthly premium for each month you were not enrolled.
Health Insurance After Retirement Before Medicare (Early Retirement)
Should you keep working or retire early? Your decision may be influenced by your age, health, budget, Medicare eligibility, social security benefits, and employer coverage.
Employer Retiree Coverage
Some employers offer retiree coverage after you leave the company. However, retiree coverage and Medicare are not the same. Retiree coverage is health coverage that is provided to former employees of a company. This typically pays second to Medicare, which means you still need to enroll in Medicare to be fully covered. However, retiree coverage can help with health-related expenses if you retire before 65.
Not every employer offers retiree coverage. Since it isn’t required, your employer (or former employer) can cancel or change your retiree plan at any time. It’s safest for you to have Medicare as well. Plus, if you don’t enroll in Medicare when you first become eligible, you will face a penalty fee. Some retiree plans automatically stop when you turn 65 and become eligible for Medicare.
If your employer does not offer retiree coverage, retiring or losing your job gives you a SEP. A Special Enrollment Period means that you don’t have to wait for AEP, the Annual Enrollment Period, to buy coverage. You will have 60 days from your last day of work to enroll in a marketplace health plan. After those 60 days are over, you’ll have to wait until AEP (October 15 – December 7) to buy a marketplace plan, at which point you will be charged a penalty fee for having a lapse in coverage.
FERS/CSRS Retirement and Medicare
The CSRS, or Civil Service Retirement Act, became effective on August 1, 1920. It was replaced by the Federal Employees Retirement System (FERS) on January 1, 1987. Some people may still belong to CSRS. Both programs are for government employees only.
Both FERS and CSRS allow you to retire at age 62 if you have five or more years of service or at age 60 if you have 20 or more years of experience. Under FERS, you can retire between ages 55 and 57 (depending on your birth year) if you have 30 or more years of service.
Regardless of your FERS or CSRS status, if you’re 65, you’ll qualify for Medicare. You’ll also qualify for Medicare if you have a qualifying disability. If you are under 65 and do not qualify for Medicare, you can receive your FERS or CSRS benefits but will have to wait until you reach Medicare qualifying age.
Until then, you may qualify for the Federal Employees Health Benefits Program (FEHB). Once you do become eligible for Medicare, you may want to enroll in Part A anyway because there is no premium if you’ve worked for at least 40 quarters.
COBRA
When you leave your job, you’ll also have the option to enroll in COBRA. COBRA allows you to continue to belong to your employer’s group plan for a temporary period after you leave the company. The company can “kick you off” at any time, so this is not a permanent option. However, COBRA can help you out while you figure out what your other options are.
Ask your employer or your HR representative to find out what COBRA might look like for you.
Can you get Medicare at age 62?
It’s important to understand the differences between Social Security and Medicare. You can start to receive Social Security retirement benefits at the age of 62. This amount is typically reduced until you reach the age of 65. The average person does not qualify for Medicare until age 65, but there are exceptions.
You are automatically enrolled in Medicare once you have received Social Security benefits for two consecutive years. This means if you started receiving benefits at age 62, you will qualify for Medicare at age 64. Plus, you may qualify for Medicare before 65 if you have Lou Gehrig’s Disease (ALS) or End-Stage Renal Disease.
Importance of PlanningforRetirement
It’s never too early to start planning for retirement and Medicare. Our licensed agents can help explain your coverage options and answer all of your questions. Plus, they can provide bias-free assistance with a wide range of plan options because they are licensed with all major carriers in your state. Start planning now! Call us at 844-431-1832 or fill out this form to arrange a no-cost, no-obligation appointment.
This post was originally published on December 27, 2018, and was last updated on November 15, 2019.